UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 6-K
REPORT OF FOREIGN PRIVATE ISSUER
PURSUANT TO RULE 13a-16 OR 15d-16 UNDER THE
SECURITIES EXCHANGE ACT OF 1934
For the month of October, 2026
Commission File Number 1-11414
BLADEX, INC.
(Translation of Registrant’s name into English)
Business Park Torre V, Ave. La Rotonda, Costa del Este
P.O. Box 0819-08730
Panama City, Republic of Panama
(Address of Principal Executive Office)
Indicate by check mark whether the registrant files or will file annual reports under cover of Form 20-F or Form 40-F.
Form 20-F x Form 40-F o
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
| BLADEX, INC. | ||||||||
| (Registrant) | ||||||||
| Date: October 28, 2026 | By: | /s/ Annette van Hoorde de Solís | ||||||
| Name: | Annette van Hoorde de Solís | |||||||
| Title: | Chief Financial Officer | |||||||
BLADEX ANNOUNCES NET PROFIT OF $63.2 MILLION FOR THE THIRD QUARTER 2026
PANAMA CITY, REPUBLIC OF PANAMA, OCTOBER 26, 2026
Bladex, Inc. (NYSE: BLX, or “the Bank”), a Panama-based multinational bank originally established by the central banks of 23 Latin-American and Caribbean countries to promote foreign trade and economic integration in the Region, announced today its results for the third quarter (“3Q26”) and the nine months (“9M26”) ended September 30, 2026.
The consolidated financial information in this document has been prepared in accordance with International Financial Reporting Standards (“IFRS”) as issued by the International Accounting Standards Board (“IASB”).
2 | ||
FINANCIAL & BUSINESS HIGHLIGHTS
•Strong profitability with Net Profits reaching $63.2 million in 3Q26 (+15% YoY) and $186.0 million in 9M26 (+9% YoY), driven by all-time high levels of Net Interest Income (“NII”), solid fee generation and continued funding optimization. Earnings per share totaled $1.48for 3Q26 and $4.56 for 9M26, reflecting the deduction of the AT1 coupon distribution from net profit attributable to common shareholders. This affects year-over-year EPS comparability, as the AT1 was issued in September 2025.
•Adjusted Annualized Return on Equity stood at 15.0% in 3Q26 and 15.2% in 9M26, reflecting increased top-line performance, disciplined commercial growth, enhanced revenue diversification and continued funding optimization. Including the effect of the AT1 issuance completed in late September 2025, the annualized Return on Equity (“ROE”) reached 14.2% in 3Q26 and 14.3% in 9M26.
•Record NII of $79.8 million in 3Q26 (+18% YoY) and $223.3 million in 9M26 (+11% YoY) mostly driven by higher average business volumes. Net Interest Margin (“NIM”) stood at 2.30% in 3Q26 and 2.29% in 9M26. The 6 bps QoQ improvement benefited from accelerated recognition of deferred fees following repayments of certain medium-term loans, along with improved funding spreads and efficient liquidity management. Competitive conditions across the Region continue to pressure underlying lending spreads, particularly for high-quality short-term assets, with the impact partially mitigated by continued optimization of funding costs and liquidity levels.
•Fees and non-interest income remained strong at $19.3 million in 3Q26 (+26% YoY), reflecting continued contributions across the Bank’s fee-generating businesses, including letters of credit and guarantees, credit commitments, structuring and distribution activities, and the growing contribution from client derivatives. Non-interest income represented 19% of total revenues in 3Q26, underscoring the diversified nature of the Bank’s revenue streams, supported by sustained client activity, broader product capabilities and continued execution of its strategic initiatives. Consequently, fees and non-interest income totaled $57.9 million in 9M26 (+15% YoY).
•Well-managed Efficiency Ratio of 25.8% in 3Q26 and 25.4% in 9M26, reflects continued cost discipline while supporting higher business volumes and ongoing investments in talent, technology and strategic initiatives. The Bank continues to balance its investments with its commitment to maintaining a highly efficient operating structure.
•Credit Portfolio reached a record level at $16,584 million as of September 30, 2026 (+35% YoY), resulting from:
◦Commercial Portfolio EoP balances reaching a peak of $14,976 million at the end of 3Q26 (+38% YoY), reflecting growth across loans and contingencies as the Bank continues to execute its commercial pipeline, including a significant short-term transaction with the Government of Panama that underscores the Bank’s execution capabilities and ability to manage its capital deployment and balance sheet resources.
◦Treasury Investment Portfolio of $1,608 million (+14% YoY), mostly consisting of investment-grade securities outside of Latin America held at amortized cost, further enhancing country and credit-risk diversification and providing contingent liquidity funding.
•Sound asset quality, with most of the credit portfolio (99.1%) remaining low-risk or Stage 1 at the end of 3Q26. Stage 2 exposures decreased to 0.5% of the portfolio at the end of 3Q26, reflecting credit quality improvements, scheduled amortizations, and the sale of a single exposure. Impaired credits or Stage 3 principal balance totaled $75.1 million or 0.4% of total Credit Portfolio, with a reserve coverage of 1.4x.
•Heightened and diversified deposit base, reaching historically high levels of $7,912 million at the end of 3Q26(+16% YoY), representing 56% of the Bank’s total funding sources. Average deposits continued to grow during the quarter, while the Bank leveraged its diversified funding platform and broad access to interbank and debt capital markets to support the significant expansion of its loan portfolio.
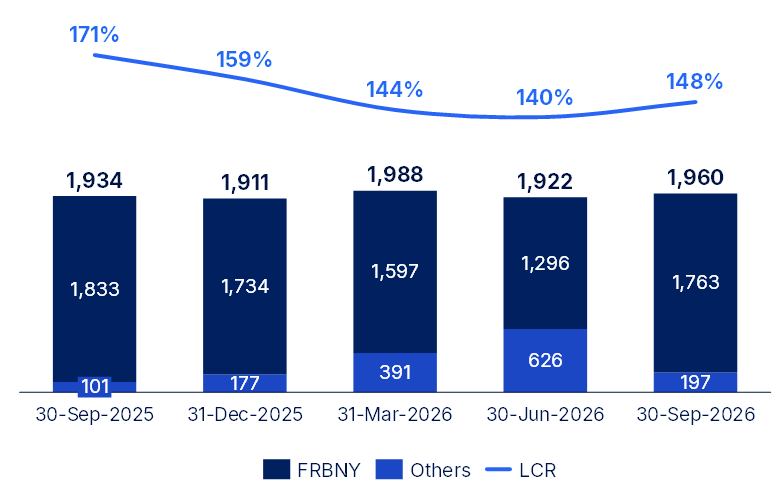
•Solid liquidity position at $1,960 million, or 12% of total assets as of September 30, 2026, mostly consisting of deposits placed with the Federal Reserve Bank of New York (90%). Liquidity Coverage Ratio reached 148% at the end of 3Q26.
•The Bank’s Tier 1 Basel III Capital and Regulatory Capital Adequacy Ratios resulted in 16.2% and 14.3% at the end of 3Q26, respectively, both well above internal targets and regulatory minimum, reflecting the strategic deployment of capital to support profitable business growth.
3 | ||
FINANCIAL SNAPSHOT
| (US$ million, except percentages and per share amounts) | 3Q26 | 2Q26 | 3Q25 | QoQ (var.) | YoY (var.) | 9M26 | 9M25 | YoY (var.) | |||||||||||||||||||||||||||||||||
| Key Income Statement Highlights | |||||||||||||||||||||||||||||||||||||||||
| Net Interest Income ("NII") | $ | 79.8 | $ | 73.3 | $ | 67.4 | 9 | % | 18 | % | $ | 223.3 | $ | 200.4 | 11 | % | |||||||||||||||||||||||||
| Fees and commissions, net | $ | 16.3 | $ | 23.3 | $ | 14.1 | -30 | % | 16 | % | $ | 52.8 | $ | 44.5 | 18 | % | |||||||||||||||||||||||||
| Gain on financial instruments, net | $ | 3.0 | $ | 2.2 | $ | 0.9 | 36 | % | 237 | % | $ | 4.8 | $ | 5.0 | -4 | % | |||||||||||||||||||||||||
| Other income, net | $ | 0.1 | $ | 0.1 | $ | 0.4 | -29 | % | -83 | % | $ | 0.3 | $ | 0.8 | -66 | % | |||||||||||||||||||||||||
| Total revenues | $ | 99.1 | $ | 98.9 | $ | 82.8 | 0 | % | 20 | % | $ | 281.1 | $ | 250.8 | 12 | % | |||||||||||||||||||||||||
| Impairment losses on financial instruments | $ | (10.4) | $ | (8.6) | $ | (6.5) | -21 | % | -61 | % | $ | (23.7) | $ | (16.7) | -42 | % | |||||||||||||||||||||||||
| Operating expenses | $ | (25.6) | $ | (23.8) | $ | (21.3) | -7 | % | -20 | % | $ | (71.4) | $ | (63.2) | -13 | % | |||||||||||||||||||||||||
| Profit for the period | $ | 63.2 | $ | 66.5 | $ | 55.0 | -5 | % | 15 | % | $ | 186.0 | $ | 170.9 | 9 | % | |||||||||||||||||||||||||
| Profitability Ratios | |||||||||||||||||||||||||||||||||||||||||
Earnings per Share ("EPS") (1) | $ | 1.48 | $ | 1.77 | $ | 1.48 | -16 | % | 0 | % | $ | 4.56 | $ | 4.60 | -1 | % | |||||||||||||||||||||||||
Return on Average Equity (“ROE”) (2) | 14.2 | % | 15.4 | % | 14.9 | % | -127bps | -76bps | 14.3 | % | 16.2 | % | -190bps | ||||||||||||||||||||||||||||
Adjusted ROE excluding other equity instruments (3) | 15.0 | % | 16.4 | % | 15.1 | % | -145bps | -7bps | 15.2 | % | 16.3 | % | -108bps | ||||||||||||||||||||||||||||
Return on Average Assets (ROA) (4) | 1.8 | % | 2.0 | % | 1.8 | % | -21bps | -4bps | 1.9 | % | 1.9 | % | -5bps | ||||||||||||||||||||||||||||
Net Interest Margin ("NIM") (5) | 2.30 | % | 2.24 | % | 2.32 | % | 6bps | -2bps | 2.29 | % | 2.35 | % | -5bps | ||||||||||||||||||||||||||||
Net Interest Spread ("NIS") (6) | 1.73 | % | 1.64 | % | 1.64 | % | 9bps | 10bps | 1.69 | % | 1.66 | % | 2bps | ||||||||||||||||||||||||||||
Efficiency Ratio (7) | 25.8 | % | 24.1 | % | 25.8 | % | 167bps | 2bps | 25.4 | % | 25.2 | % | 22bps | ||||||||||||||||||||||||||||
| Assets, Capital, Liquidity & Credit Quality | |||||||||||||||||||||||||||||||||||||||||
Credit Portfolio (8) | $ | 16,584 | $ | 14,466 | $ | 12,286 | 15 | % | 35 | % | $ | 16,584 | $ | 12,286 | 35 | % | |||||||||||||||||||||||||
Commercial Portfolio (9) | $ | 14,976 | $ | 13,029 | $ | 10,872 | 15 | % | 38 | % | $ | 14,976 | $ | 10,872 | 38 | % | |||||||||||||||||||||||||
| Treasury Investment Portfolio | $ | 1,608 | $ | 1,437 | $ | 1,414 | 12 | % | 14 | % | $ | 1,608 | $ | 1,414 | 14 | % | |||||||||||||||||||||||||
| Total assets | $ | 16,480 | $ | 14,437 | $ | 12,498 | 14 | % | 32 | % | $ | 16,480 | $ | 12,498 | 32 | % | |||||||||||||||||||||||||
| Total equity | $ | 1,790 | $ | 1,757 | $ | 1,646 | 2 | % | 9 | % | $ | 1,790 | $ | 1,646 | 9 | % | |||||||||||||||||||||||||
Market capitalization (10) | $ | 2,068 | $ | 2,311 | $ | 1,712 | -11 | % | 21 | % | $ | 2,068 | $ | 1,712 | 21 | % | |||||||||||||||||||||||||
Tier 1 Capital to Risk-Weighted Assets (Basel III – IRB) (11) | 16.2 | % | 16.6 | % | 18.1 | % | -48bps | -196bps | 16.2 | % | 18.1 | % | -196bps | ||||||||||||||||||||||||||||
Capital Adequacy Ratio (Regulatory) (12) | 14.3 | % | 14.3 | % | 15.8 | % | -1bps | -145bps | 14.3 | % | 15.8 | % | -145bps | ||||||||||||||||||||||||||||
| Total Assets / Total Equity (times) | 9.2 | 8.2 | 7.6 | 12 | % | 21 | % | 9.2 | 7.6 | 21 | % | ||||||||||||||||||||||||||||||
Liquid Assets / Total Assets (13) | 12 | % | 13 | % | 15 | % | -143bps | -359bps | 12 | % | 15 | % | -359bps | ||||||||||||||||||||||||||||
Liquidity Coverage Ratio ("LCR") (14) | 148 | % | 140 | % | 171 | % | 762bps | -2,368bps | 148 | % | 171 | % | -2,368bps | ||||||||||||||||||||||||||||
Credit-impaired loans to Loan Portfolio (15) | 0.6 | % | 0.7 | % | 0.2 | % | -11bps | 40bps | 0.6 | % | 0.2 | % | 40bps | ||||||||||||||||||||||||||||
Impaired credits (16) to Credit Portfolio | 0.4 | % | 0.5 | % | 0.2 | % | -8bps | 29bps | 0.4 | % | 0.2 | % | 29bps | ||||||||||||||||||||||||||||
Total Allowance for Losses to Credit Portfolio (17) | 0.6 | % | 0.6 | % | 0.8 | % | -2bps | -20bps | 0.6 | % | 0.8 | % | -20bps | ||||||||||||||||||||||||||||
Total Allowance for Losses to Impaired credits (times) (17) | 1.4 | 1.2 | 5.4 | 10 | % | -75 | % | 1.4 | 5.4 | -75 | % | ||||||||||||||||||||||||||||||
4 | ||
RESULTS BY BUSINESS SEGMENT
Bladex’s activities are comprised of two business segments, Commercial and Treasury. Information related to each segment is set out below. Business segment reporting is based on the Bank’s managerial accounting process, which assigns assets, liabilities, revenue, and expense items to each business segment on a systemic basis.
COMMERCIAL BUSINESS SEGMENT
The Commercial Business Segment encompasses the Bank’s core business of financial intermediation and fee generation activities developed to cater to corporations, financial institutions, and investors in Latin America. These activities include the origination of bilateral short-term and medium-term loans, structured and syndicated credits, loan commitments, and financial guarantee contracts such as issued and confirmed letters of credit, stand-by letters of credit, guarantees covering commercial risk, and other assets consisting of customers’ liabilities under acceptances and investment securities managed by the Commercial business unit (or “Commercial Bond Portfolio”).
The majority of the Bank’s core financial intermediation business, consisting of loans – principal balance (or the “Loan Portfolio”), amounted to $12,321 million at the end of 3Q26, representing an increase of 18% QoQ and 41% YoY, primarily driven by short-term lending growth, including sovereign exposures and financing opportunities within the Bank’s traditional client base. This expansion reflects the Bank’s ability to capture attractive market opportunities and deploy capital efficiently, while maintaining its established underwriting standards and sound credit quality. Higher average loan balances contributed to increased Net Interest Income (“NII”), while generating attractive risk-adjusted returns. Contingencies and acceptances amounted to $2,460 million at the end of 3Q26 (+5% QoQ and +16% YoY), supporting solid client demand and commercial activity across the Region. Additionally, the Bank’s Commercial Bond Portfolio reached principal balances of $195 million registered as securities at fair value through comprehensive income (“FVOCI”), as of September 30, 2026.
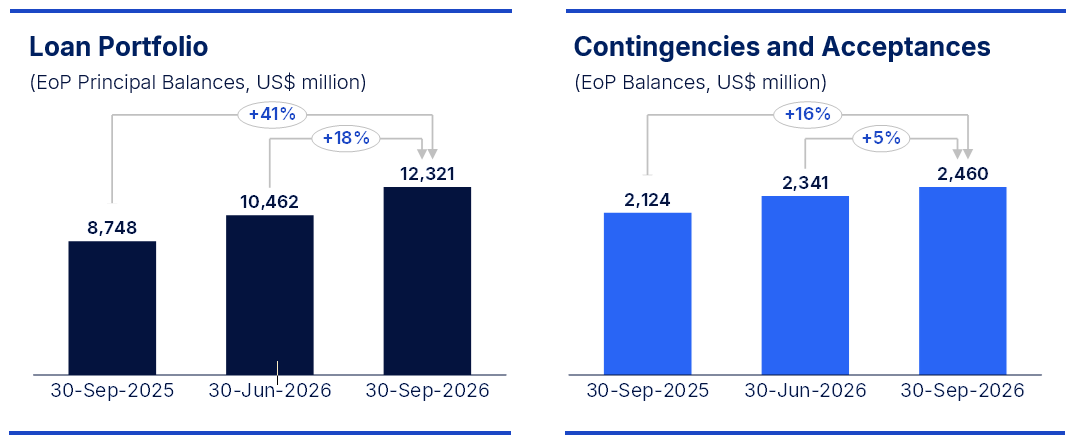
Consequently, the Bank’s Commercial Portfolio reached an all-time high of $14,976 million at the end of 3Q26, with increases of 15% from $13,029 million in the prior quarter and of 38% from $10,872 million a year ago, highlighting a significant short-term transaction with the Government of Panama that underscores the Bank’s capacity to underwrite and execute large transactions, while prudently managing its capital deployment and balance sheet resources. The expansion remained aligned with the Bank´s established risk appetite and disciplined approach to generating attractive risk-adjusted returns. In addition, the average Commercial Portfolio balances totaled $13,406 million in 3Q26 (+8% QoQ and +27% YoY) and $12,380 million in 9M26 (+18% YoY).
5 | ||
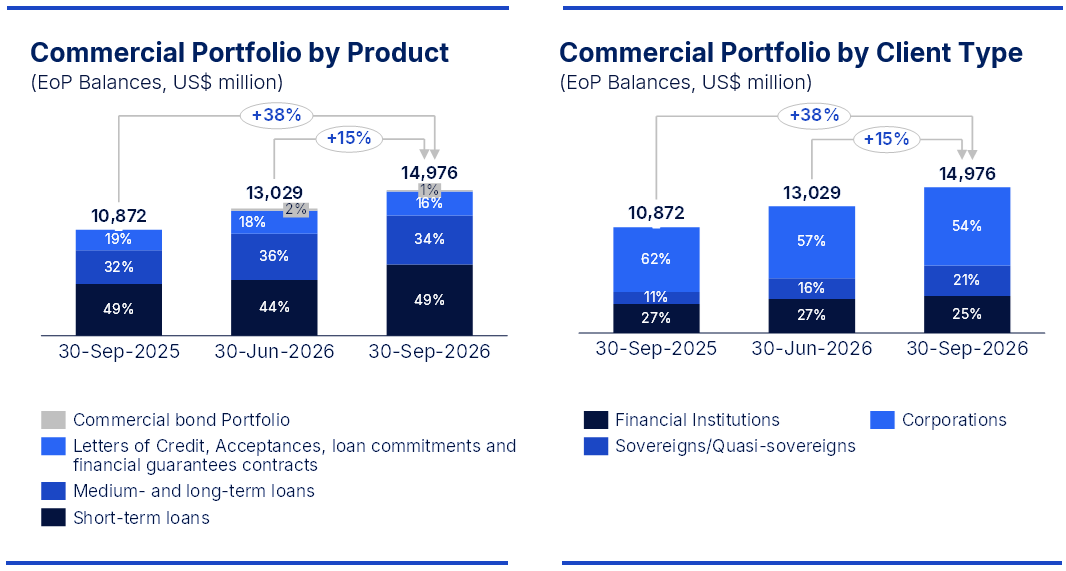
As of September 30, 2026, 68% of the Commercial Portfolio was scheduled to mature within a year, providing flexibility to reprice and redeploy capital as market conditions evolve, and trade finance transactions accounted for 43% of the Bank’s short-term book, based on original tenor.
Weighted average lending rates stood at 6.61% in 3Q26 (+4bps QoQ; -73bps YoY) and 6.63% for 9M26 (-80bps YoY). The quarterly improvement included a temporary benefit from the accelerated recognition of deferred fees following early repayments of a couple of medium-term loans. Underlying lending spreads continued to face pressure from elevated USD market liquidity and intensified competition for high-quality assets across the Region, with the impact on net interest margin partially mitigated by improved funding spreads and efficient liquidity management.
6 | ||
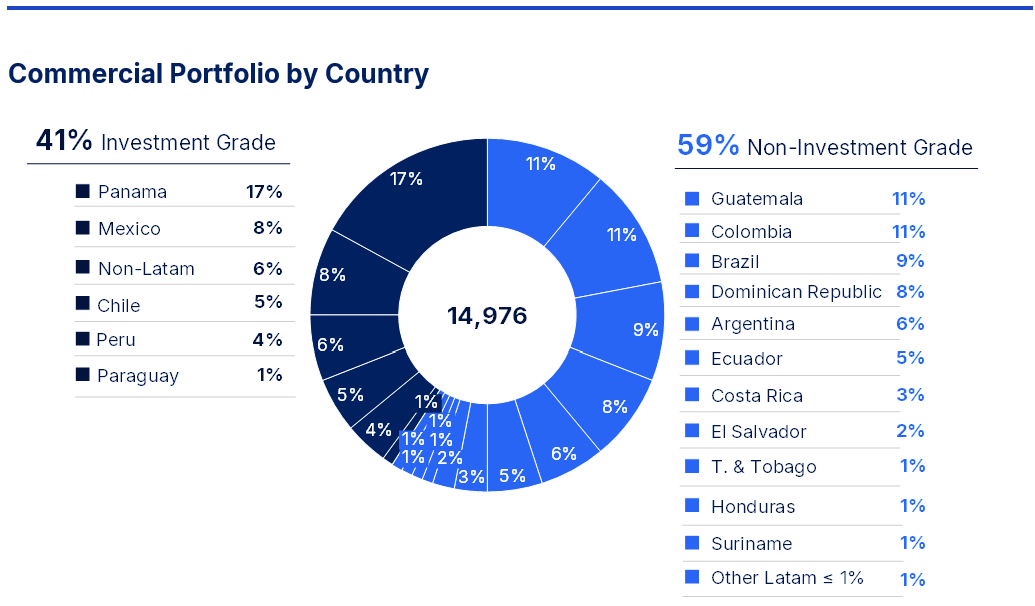
Bladex maintains well-diversified exposures across countries and industries. At the end of 3Q26, Panama represents the largest country-risk exposure of the total Commercial Portfolio at 17%, followed by Guatemala and Colombia, each at 11%, Brazil at 9%, Mexico and Dominican Republic, each at 8%, followed by Argentina and exposure to top-rated countries outside of Latin America, which relates to transactions carried out in the Region, each at 6%. As of September 30, 2026, 41% of the Commercial Portfolio was geographically distributed in investment grade countries.
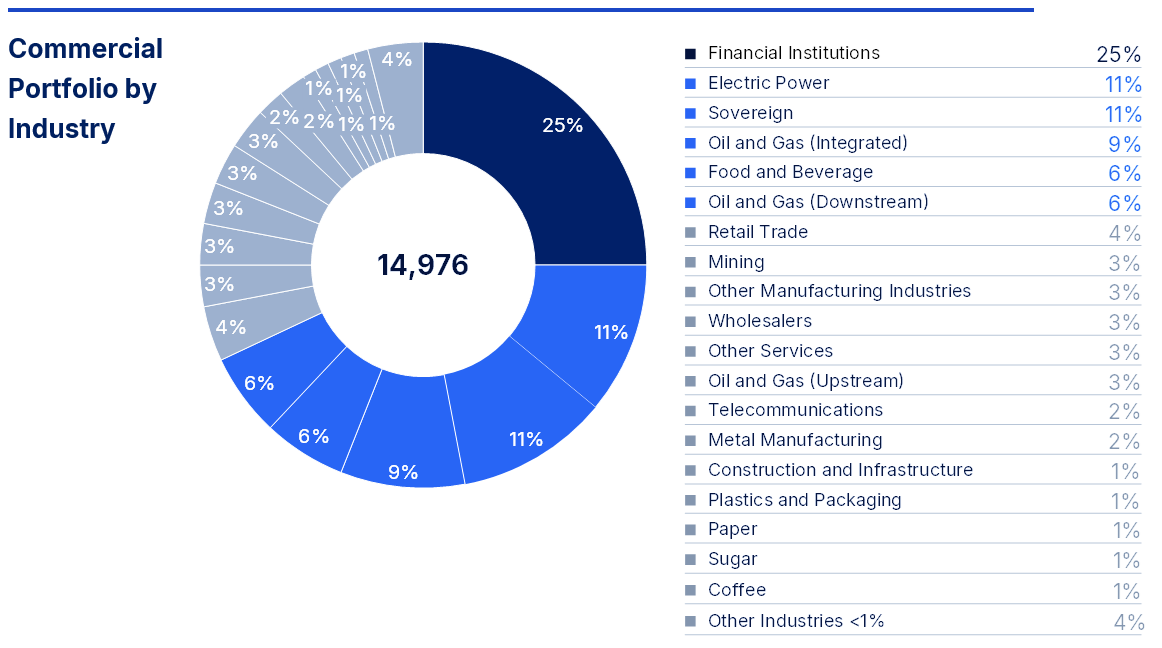
Exposures to the Bank’s traditional client base of financial institutions represented 25% of the Commercial Portfolio, while sovereign and quasi-sovereign exposures accounted for 21%, reflecting the increased contribution of this segment to portfolio growth. Corporate exposures represented the remaining 54% and were comprised of top-tier clients with a diversified sector profile. Excluding financial institutions, the largest concentrations within the Commercial Portfolio were in Electric Power and Sovereign, each representing 11% of the Commercial Portfolio, followed by Oil & Gas (Integrated) at 9%, Food and Beverage and Oil & Gas (Downstream), each at 6% at the end of 3Q26.
Refer to Exhibit IX for additional information related to the Bank’s Commercial Portfolio distribution by country.
Commercial Segment Profitability
Profits from the Commercial Business Segment include: (i) net interest income from loans and investment securities of the Commercial bond Portfolio; (ii) fees and commissions from the issuance, confirmation and negotiation of letters of credit, guarantees and loan commitments, as well as through loan structuring and syndication activities; (iii) gain on sale of loans generated through loan intermediation activities, such as sales and distribution in the primary market; (iv) gain (loss) on sale of loans measured at FVTPL; (v) impairment losses on financial instruments; and (vi) direct and allocated operating expenses.
7 | ||
| (US$ million) | 3Q26 | 2Q26 | 3Q25 | QoQ (%) | YoY (%) | 9M26 | 9M25 | YoY (%) | ||||||||||||||||||||||||||||||||||||||||||
| Commercial Business Segment: | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 74.7 | $ | 66.0 | $ | 60.0 | 13 | % | 24 | % | $ | 202.9 | $ | 178.7 | 14 | % | ||||||||||||||||||||||||||||||||||
| Non-interest income, net | 16.5 | 23.7 | 15.3 | -30 | % | 8 | % | 53.6 | 47.7 | 12 | % | |||||||||||||||||||||||||||||||||||||||
| Total revenues | 91.2 | 89.6 | 75.3 | 2 | % | 21 | % | 256.5 | 226.4 | 13 | % | |||||||||||||||||||||||||||||||||||||||
| Impairment losses on financial instruments | (10.5) | (8.7) | (6.5) | -21 | % | -62 | % | (24.4) | (16.8) | -46 | % | |||||||||||||||||||||||||||||||||||||||
| Operating expenses | (20.2) | (18.8) | (16.8) | -8 | % | -20 | % | (56.3) | (50.0) | -13 | % | |||||||||||||||||||||||||||||||||||||||
| Profit for the segment | $ | 60.5 | $ | 62.2 | $ | 52.0 | -3 | % | 16 | % | $ | 175.8 | $ | 159.6 | 10 | % | ||||||||||||||||||||||||||||||||||
Commercial Segment Profit totaled $60.5 million in 3Q26 (-3% QoQ and +16% YoY) and $175.8 million in 9M26 (+10% YoY). The results were primarily driven by strong top line performance in net interest income, supported by heightened average business volumes, and complemented by strong fee income generation mainly from the Bank’s off-balance sheet and structuring business, offsetting the effects of increasing operating expenses and impairment losses on financial instruments, mainly from Commercial Portfolio growth and the increase in reserve coverage of an exposure previously assigned to Stage 3.
TREASURY BUSINESS SEGMENT
The Treasury Business Segment manages the Bank’s Treasury investment portfolio and overall asset and liability structure to enhance funding efficiency and liquidity, mitigating the traditional financial risks associated with the balance sheet, such as interest rate, liquidity, price, and currency risks. Interest-earning assets managed by the Treasury Business Segment include liquidity positions in cash and cash equivalents, as well as highly liquid corporate debt securities rated ‘A-‘ or above, and financial instruments related to Treasury investment management activities, consisting of the principal balances of securities at fair value through other comprehensive income (“FVOCI”) and securities at amortized cost (the “Treasury Investment Portfolio”). The Treasury Business Segment also manages the Bank’s interest-bearing liabilities, consisting of deposits, securities sold under repurchased agreements, borrowed funds and floating and fixed rate debt placements.
Liquidity
The Bank’s liquid assets, mostly consisting of cash and due from banks, totaled $1,960 million as of September 30, 2026, compared to $1,922 million as of June 30, 2026, and $1,934 million as of September 30, 2025, highlighting the Bank’s proactive and prudent liquidity management approach in response to higher interest-bearing assets, also conforming with Basel methodology’s liquidity coverage ratio, as required by Panamanian banking regulator. At the end of those periods, liquidity balances to total assets represented 12%, 13% and 15%, respectively, while the liquidity balances to total deposits ratio was 25%, 24% and 28%, respectively. As of September 30, 2026, 90% of total liquid assets represented deposits placed with the Federal Reserve Bank of New York (“FRBNY”) and $180 million consists of highly rated corporate debt securities (‘A-‘ or above) classified as high quality liquid assets (“HQLA”) in accordance with the specifications of the Basel Committee.
8 | ||
Treasury Investment Portfolio
The Bank’s Treasury Investment Portfolio amounted to $1,608 million in principal amount as of September 30, 2026, up 12% from the previous quarter and 14% from a year ago, supporting two strategic investment objectives.
The high-quality liquid assets (“HQLA”) totaling $180 million, consisting of highly rated corporate debt securities (‘A-‘ or above) and reported as part of the Bank’s liquidity position. The remaining $1,428 million, primarily held at amortized cost, is focused on diversifying credit-risk exposures, mainly outside Latin America, while also providing an additional source of contingent liquidity through eligible securities that can be pledged at the Federal Reserve Bank of New York (“FRBNY”) discount window.
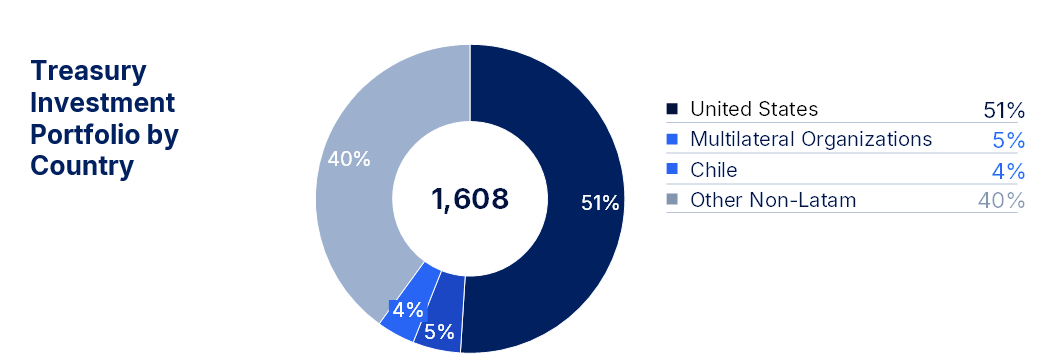
As of September 30, 2026, 99% of the Treasury Investment Portfolio consists of investment-grade credit securities. Refer to Exhibit X for a per-country risk distribution of the Treasury Investment Portfolio.

Funding
The Bank’s principal sources of funds are the principal balances of deposits, borrowed funds and floating and fixed rate debt placements. As of September 30, 2026, total net funding amounted to $14,100 million, representing an increase of 15% compared to $12,270 million a quarter ago, and of 36% compared to $10,372 million a year ago, demonstrating the Bank’s capacity to support significant Commercial Portfolio growth through a strong and diversified funding platform across products and geographies.
9 | ||
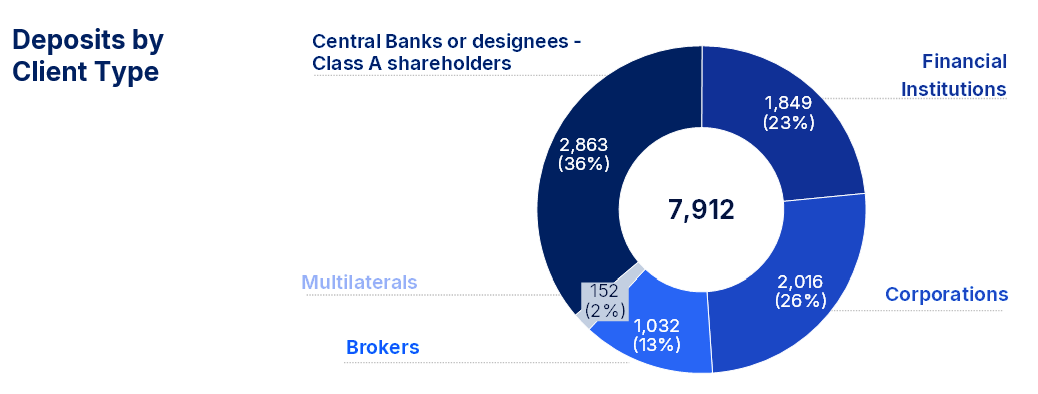
The Bank obtains deposits from central banks, as well as from multilaterals, commercial banks, brokers and corporations primarily located in the Region. The principal balance of deposits reached a record $7,912 million at the end of 3Q26 (+16% YoY), representing 56% of total funding sources. The Bank’s Yankee CD program also reached $1,942 million, or 14% of total funding sources. Average deposits increased to $7,660 million in 3Q26 (+6% QoQ and +22% YoY) and to $7,184 million in 9M26 (+19% YoY), supporting improved funding spreads. These results reflect continued progress in expanding and diversifying the Bank’s deposit base, supported by effective cross-selling efforts and long-standing relationships with central banks, financial institutions, corporations and other institutional depositors.
Class A shareholders (i.e.: central banks and their designees) represented 36% of total deposits at the end of 3Q26, continuing to provide an important and stable component of the Bank’s deposit franchise.
Funding through the principal balance of short and medium-term borrowings and debt, net of transaction costs and interest payable increased 44% QoQ and 74% YoY to $5,974 million at the end of 3Q26. This increase reflects the Bank’s ability to mobilize flexible funding to support the significant expansion of its short-term loan book, complementing its deposit franchise. The Bank’s ample and constant access to interbank and debt capital markets is clearly evidenced through public debt issuances in Mexico and Panama, coupled with private debt issuances placed in different markets primarily in Asia, Europe, the United States and Latin America. Funding through the principal balance of securities sold under repurchase agreements (“Repos”) reached $247 million at the end of 3Q26 (-10% QoQ; +77% YoY).
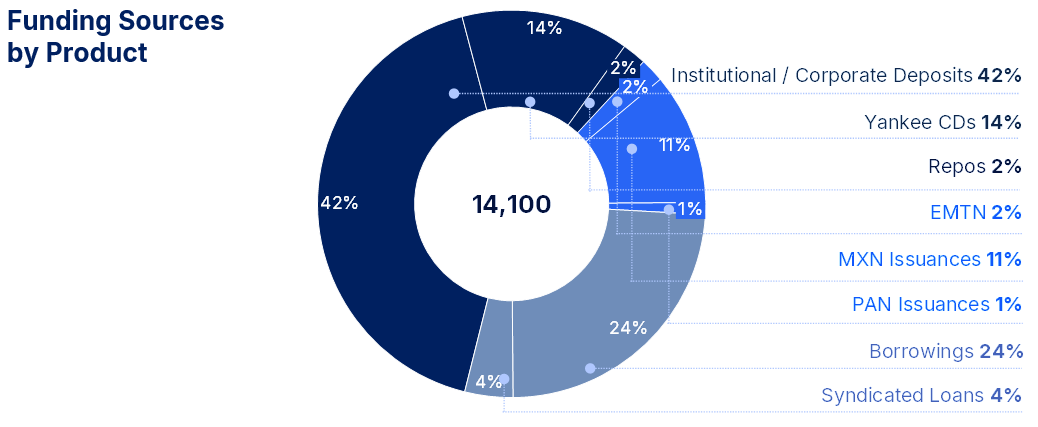
The Bank's funding sources are well diversified across products, geographies and currencies. The Bank maintained no significant foreign exchange risk and does not hold material open foreign exchange positions. Most funding obtained in currencies other than the U.S. dollar is hedged into U.S. dollars through derivative instruments, while a smaller portion is matched with assets denominated in the same currency, thereby avoiding currency mismatches.
10 | ||
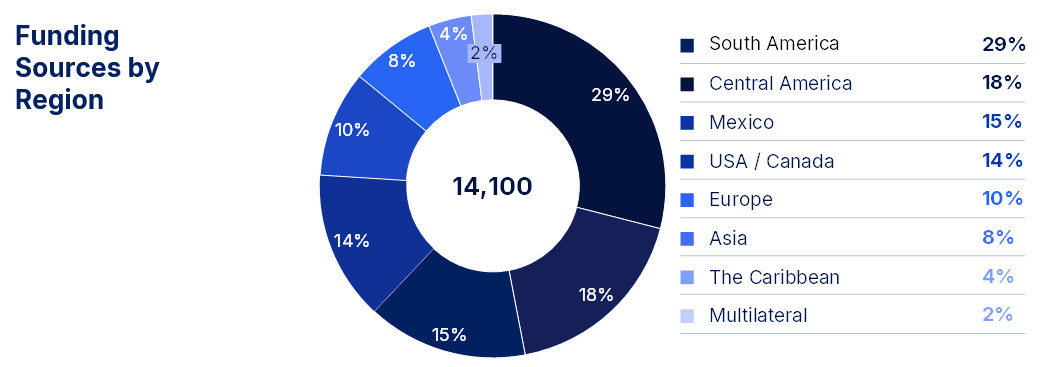
Weighted average funding costs resulted in 4.38% in 3Q26 (+1bps QoQ; -56bps YoY) and 4.39% for 9M26 (-62bps YoY). Higher average deposit supported improved funding spreads, while the Bank´s diversified access to short-term facilities provided flexibility to support Commercial Portfolio growth.
Treasury Segment Profitability
Profits from the Treasury Business Segment include net interest income derived from the above-mentioned Treasury assets and liabilities, and related net other income (net results from derivative financial instruments and foreign currency exchange, gain (loss) per financial instruments at fair value through profit or loss (“FVTPL”), gain (loss) on sale of securities, gain (loss) on intermediary derivatives and other income), recovery or impairment loss on financial instruments, and direct and allocated operating expenses.
| (US$ million) | 3Q26 | 2Q26 | 3Q25 | QoQ (%) | YoY (%) | 9M26 | 9M25 | YoY (%) | ||||||||||||||||||||||||||||||||||||||||||
| Treasury Business Segment: | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 5.1 | $ | 7.3 | $ | 7.4 | -30 | % | -31 | % | $ | 20.3 | $ | 21.7 | -6 | % | ||||||||||||||||||||||||||||||||||
| Non-interest income, net | 2.8 | 2.0 | 0.1 | 42 | % | 3682 | % | 4.3 | 2.7 | 59 | % | |||||||||||||||||||||||||||||||||||||||
| Total revenues | 7.9 | 9.3 | 7.5 | -15 | % | 5 | % | 24.6 | 24.4 | 1 | % | |||||||||||||||||||||||||||||||||||||||
| Reversals on financial instruments | 0.1 | 0.1 | 0.0 | 42 | % | 523 | % | 0.6 | 0.0 | 1,709 | % | |||||||||||||||||||||||||||||||||||||||
| Operating expenses | (5.4) | (5.1) | (4.5) | -6 | % | -18 | % | (15.1) | (13.2) | -14 | % | |||||||||||||||||||||||||||||||||||||||
| Profit for the segment | $ | 2.6 | $ | 4.2 | $ | 3.0 | -38 | % | -12 | % | $ | 10.1 | $ | 11.3 | -10 | % | ||||||||||||||||||||||||||||||||||
The Treasury Business Segment recorded $2.6 million profit for 3Q26 (-38% QoQ; -12% YoY) and $10.1 million profit for 9M26 (-10% YoY). The quarterly and yearly decrease was primarily driven by increased interest expenses from the effect of increased market rates, the use of short-term facilities to support asset growth and increased operating expenses, partly offset by gains resulting from the Bank’s intermediation of derivatives financial instruments.
11 | ||
NET INTEREST INCOME AND MARGINS
| (US$ million, except percentages) | 3Q26 | 2Q26 | 3Q25 | QoQ (%) | YoY (%) | 9M26 | 9M25 | YoY (%) | ||||||||||||||||||||||||||||||||||||||||||
| Net Interest Income | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest income | $215.0 | $199.2 | $193.7 | 8 | % | 11 | % | $600.2 | $577.5 | 4 | % | |||||||||||||||||||||||||||||||||||||||
| Interest expense | (135.2) | (125.9) | (126.3) | -7 | % | -7 | % | (376.9) | (377.1) | 0 | % | |||||||||||||||||||||||||||||||||||||||
| Net Interest Income ("NII") | $79.8 | $73.3 | $67.4 | 9 | % | 18 | % | $223.3 | $200.4 | 11 | % | |||||||||||||||||||||||||||||||||||||||
| Net Interest Spread ("NIS") | 1.73 | % | 1.64 | % | 1.64 | % | 9bps | 10bps | 1.69 | % | 1.66 | % | 2bps | |||||||||||||||||||||||||||||||||||||
| Net Interest Margin ("NIM") | 2.30 | % | 2.24 | % | 2.32 | % | 6bps | -2bps | 2.29 | % | 2.35 | % | -5bps | |||||||||||||||||||||||||||||||||||||
NII resulted in $79.8 million in 3Q26 (+9% QoQ; +18% YoY) and $223.3 million in 9M26 (+11% YoY). Record NII levels were primarily driven by higher average business volumes, including continued growth in short-term lending and the contribution from medium-term transactions with attractive risk-adjusted returns. The quarter also benefited from the accelerated recognition of deferred fees following early repayments of certain medium-term loans, temporarily supporting lending yields and NIM.
NIM increased by 6 bps QoQ to 2.30% in 3Q26, while reaching 2.29% for 9M26. This improvement, in addition to the benefit from accelerated fee recognition, also is due to improve funding spreads and efficient yet prudent liquidity management. These factors help mitigate continued compression in underlying lending spreads, driven by abundant U.S. Dollar liquidity and intensified competition from high-quality assets across the Region.
NON-INTEREST INCOME
Non-Interest Income comprises Fees and Commissions, net, including revenues associated with the letter of credit business and guarantees, credit commitments, structuring services, loan intermediation and distribution in the primary market, and other commissions, net of expenses; gains (losses) on financial instruments, net, including gains from the sales of financial instruments, as well as unrealized gains or losses on fair value valuations; and other income, net.
| (US$ million, except percentages) | 3Q26 | 2Q26 | 3Q25 | QoQ (%) | YoY (%) | 9M26 | 9M25 | YoY (%) | ||||||||||||||||||||||||||||||||||||||||||
| Fees and commissions | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Letters of credit and guarantees | 9.6 | 9.5 | 8.9 | 1 | % | 9 | % | 26.5 | 23.4 | 13 | % | |||||||||||||||||||||||||||||||||||||||
| Structuring services | 3.9 | 7.9 | 1.9 | -50 | % | 105 | % | 14.9 | 14.3 | 4 | % | |||||||||||||||||||||||||||||||||||||||
| Credit commitments | 3.6 | 5.2 | 4.0 | -30 | % | -8 | % | 12.4 | 8.2 | 52 | % | |||||||||||||||||||||||||||||||||||||||
| Other fees and commissions income | 0.4 | 1.9 | 0.2 | -79 | % | 70 | % | 2.7 | 0.8 | 259 | % | |||||||||||||||||||||||||||||||||||||||
| Total fee and commission income | 17.6 | 24.5 | 15.0 | -28 | % | 17 | % | 56.5 | 46.6 | 21 | % | |||||||||||||||||||||||||||||||||||||||
| Fees and commission expenses | (1.3) | (1.2) | (0.9) | -6 | % | -41 | % | (3.8) | (2.1) | -83 | % | |||||||||||||||||||||||||||||||||||||||
| Fees and Commissions, net | $ | 16.3 | $ | 23.3 | $ | 14.1 | -30 | % | 16 | % | $ | 52.8 | $ | 44.5 | 18 | % | ||||||||||||||||||||||||||||||||||
| Gain on financial instruments, net | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans | 0.0 | 0.1 | 0.9 | -66 | % | -97 | % | 0.1 | 2.2 | -96 | % | |||||||||||||||||||||||||||||||||||||||
| Investment securities | 0.0 | 0.2 | 0.5 | n.m. | -100 | % | 0.2 | 0.0 | 973 | % | ||||||||||||||||||||||||||||||||||||||||
| Derivatives - intermediation | 2.6 | 1.3 | 0.6 | 94 | % | 304 | % | 4.2 | 0.7 | 528 | % | |||||||||||||||||||||||||||||||||||||||
| Other financial instruments | 0.3 | 0.5 | (1.1) | -36 | % | 131 | % | 0.3 | 2.1 | -87 | % | |||||||||||||||||||||||||||||||||||||||
| Gain on financial instruments, net | 3.0 | 2.2 | 0.9 | 36 | % | 237 | % | 4.8 | 5.0 | -4 | % | |||||||||||||||||||||||||||||||||||||||
| Other income, net | 0.1 | 0.1 | 0.4 | -29 | % | -84 | % | 0.3 | 0.8 | -66 | % | |||||||||||||||||||||||||||||||||||||||
| Total other income, net | 19.3 | 25.6 | 15.4 | -25 | % | 26 | % | 57.9 | 50.3 | 15 | % | |||||||||||||||||||||||||||||||||||||||
| "n.m." means not meaningful. | ||||||||||||||||||||||||||||||||||||||||||||||||||
Non-interest income reached $19.3 million in 3Q26 (-25% QoQ; +26% YoY) and $57.9 million in 9M26 (+15% YoY), representing 19% of total revenues. Fees from letters of credit and guarantees totaled $9.6 million in 3Q26 and $26.5 million in 9M26, supported by increased trade finance activity and higher transaction volumes. The Bank’s syndication and structuring activities generated $3.9 million of fee income in 3Q26 and $14.9 million in 9M26, as the Bank completed four
12 | ||
structured transactions during the quarter, bringing the total to thirteen transactions during the first nine months of the year, mobilizing nearly $2.7 billion. Credit-commitment fees reached $3.6 million in 3Q26 and $12.4 million in 9M26, primarily from project finance transactions and medium-term committed facilities. As the Bank continues to diversify its sources of non-interest income, revenues from the intermediation of derivatives for clients contributed $2.6 million in 3Q26 and $4.2 million in 9M26.
PORTFOLIO QUALITY AND TOTAL ALLOWANCE FOR CREDIT LOSSES
| (US$ million, except percentages) | 3Q26 | 2Q26 | 1Q26 | 4Q25 | 3Q25 | 9M26 | 9M25 | |||||||||||||||||||||||||||||||||||||
| Allowance for loan losses | ||||||||||||||||||||||||||||||||||||||||||||
| Balance at beginning of the period | $ | 80.5 | $ | 98.0 | $ | 94.3 | $ | 87.0 | $ | 81.9 | $ | 94.3 | $ | 78.2 | ||||||||||||||||||||||||||||||
| Impairment losses (reversals) | 10.1 | (10.1) | 3.8 | 6.7 | 5.1 | 3.8 | 8.8 | |||||||||||||||||||||||||||||||||||||
| Recoveries (write-offs) | 0.3 | (7.5) | 0.0 | 0.6 | 0.0 | (7.2) | 0.0 | |||||||||||||||||||||||||||||||||||||
| End of period balance | $ | 90.9 | $ | 80.5 | $ | 98.0 | $ | 94.3 | $ | 87.0 | $ | 90.9 | $ | 87.0 | ||||||||||||||||||||||||||||||
| Allowance for loan commitments and financial guarantee contract losses | ||||||||||||||||||||||||||||||||||||||||||||
| Balance at beginning of the period | $ | 12.0 | $ | 12.8 | $ | 12.1 | $ | 13.3 | $ | 11.9 | $ | 12.1 | $ | 5.4 | ||||||||||||||||||||||||||||||
| (Reversals) impairment losses | (0.4) | (0.9) | 0.7 | (1.2) | 1.4 | (0.6) | 7.9 | |||||||||||||||||||||||||||||||||||||
| End of period balance | $ | 11.5 | $ | 12.0 | $ | 12.8 | $ | 12.1 | $ | 13.3 | $ | 11.5 | $ | 13.3 | ||||||||||||||||||||||||||||||
| Allowance for investment securities losses | ||||||||||||||||||||||||||||||||||||||||||||
| Balance at beginning of the period | $ | 1.2 | $ | 1.3 | $ | 1.0 | $ | 1.2 | $ | 1.2 | $ | 1.0 | $ | 1.3 | ||||||||||||||||||||||||||||||
| (Reversals) impairment losses | 0.0 | (0.1) | 0.3 | (0.2) | 0.0 | 0.2 | (0.1) | |||||||||||||||||||||||||||||||||||||
| End of period balance | $ | 1.2 | $ | 1.2 | $ | 1.3 | $ | 1.0 | $ | 1.2 | $ | 1.2 | $ | 1.2 | ||||||||||||||||||||||||||||||
| Total allowance for the Credit Portfolio losses | $ | 103.6 | $ | 93.7 | $ | 112.2 | $ | 107.4 | $ | 101.5 | $ | 103.6 | $ | 101.5 | ||||||||||||||||||||||||||||||
| Allowance for cash and due from banks losses | $ | 0.0 | $ | 0.2 | $ | 0.1 | $ | 0.2 | $ | 0.1 | $ | 0.0 | $ | 0.1 | ||||||||||||||||||||||||||||||
| Total allowance for losses | $ | 103.6 | $ | 93.8 | $ | 112.3 | $ | 107.6 | $ | 101.5 | $ | 103.6 | $ | 101.5 | ||||||||||||||||||||||||||||||
| (at the end of each period) | ||||||||||||||||||||||||||||||||||||||||||||
Total allowance for losses to Credit Portfolio | 0.6 | % | 0.6 | % | 0.8 | % | 0.9 | % | 0.8 | % | 0.6 | % | 0.8 | % | ||||||||||||||||||||||||||||||
| Credit-impaired loans to Loan Portfolio | 0.6 | % | 0.7 | % | 0.4 | % | 0.4 | % | 0.2 | % | 0.6 | % | 0.2 | % | ||||||||||||||||||||||||||||||
| Total allowance for losses to impaired credits (times) | 1.4 | 1.2 | 2.9 | 2.8 | 5.4 | 1.4 | 5.4 | |||||||||||||||||||||||||||||||||||||
| Stage 1 Exposure (low risk) to Total Credit Portfolio | 99.1 | % | 98.4 | % | 97.5 | % | 98.2 | % | 97.2 | % | 99.1 | % | 97.2 | % | ||||||||||||||||||||||||||||||
| Stage 2 Exposure (increased risk) to Total Credit Portfolio | 0.5 | % | 1.1 | % | 2.2 | % | 1.5 | % | 2.6 | % | 0.5 | % | 2.6 | % | ||||||||||||||||||||||||||||||
| Stage 3 Exposure (credit impaired) to Total Credit Portfolio | 0.4 | % | 0.5 | % | 0.3 | % | 0.3 | % | 0.2 | % | 0.4 | % | 0.2 | % | ||||||||||||||||||||||||||||||
13 | ||
As of September 30, 2026, the total allowance for losses stood at $103.6 million, compared to $93.8 million the previous quarter, and $101.5 million a year ago. The $9.8 million increase in allowance for credit losses in 3Q26 was mainly driven by the growth in Stage 1, and the increase in reserve coverage of existing Stage 3 positions, partly compensated by the reduction of Stage 2 exposures from the sale of one exposure, scheduled amortizations, and rating improvements.
Credits categorized as Stage 1 or low-risk credits under IFRS 9 accounted for 99.1% of total credits, while Stage 2 exposures decreased to 0.5% of the portfolio, reflecting the aforementioned credit quality improvements. Impaired credits or Stage 3 principal balance totaled $75.1 million, or 0.4% of the Credit Portfolio, unchanged compared to $75.1 million the previous quarter and compared to $18.7 million a year ago. Allowances for losses associated with the Credit Portfolio represented a coverage ratio of 0.6% at the end of 3Q26. Total allowance for credit losses to impaired credits resulted in 1.4 times.
OPERATING EXPENSES AND EFFICIENCY
| (US$ million, except percentages) | 3Q26 | 2Q26 | 3Q25 | QoQ (%) | YoY (%) | 9M26 | 9M25 | YoY (%) | ||||||||||||||||||||||||||||||||||||||||||
| Operating expenses | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Salaries and other employee expenses | 16.1 | 14.0 | 13.2 | 16 | % | 22 | % | 43.4 | 39.5 | 10 | % | |||||||||||||||||||||||||||||||||||||||
| Depreciation and amortization of equipment, right-of-use and leasehold improvements | 0.9 | 0.9 | 0.7 | 1 | % | 34 | % | 2.8 | 2.1 | 31 | % | |||||||||||||||||||||||||||||||||||||||
| Amortization of intangible assets | 0.7 | 0.7 | 0.4 | -2 | % | 99 | % | 2.1 | 1.0 | 108 | % | |||||||||||||||||||||||||||||||||||||||
| Other expenses | 7.8 | 8.2 | 7.1 | -6 | % | 10 | % | 23.1 | 20.5 | 13 | % | |||||||||||||||||||||||||||||||||||||||
| Total Operating Expenses | $ | 25.6 | $ | 23.8 | $ | 21.3 | 7 | % | 20 | % | $ | 71.4 | $ | 63.2 | 13 | % | ||||||||||||||||||||||||||||||||||
| Efficiency Ratio | 25.8 | % | 24.1 | % | 25.8 | % | 167bps | 2bps | 25.4 | % | 25.2 | % | 22bps | |||||||||||||||||||||||||||||||||||||
Operating expenses totaled $25.6 million in 3Q26 (+7% QoQ; +20% YoY) and $71.4 million in 9M26 (+13% YoY). The quarterly and yearly increases were mostly associated with increased personnel-related expenses, mostly related to the support of strategic initiatives and variable compensation reflecting the Bank’s performance, along with continuing investments in technology, modernization and other business initiatives related to the Bank’s strategic priorities, including its associated operating costs and depreciation and amortization.
The Efficiency Ratio stood at 25.8% in 3Q26 and 25.4% for 9M26, as higher total revenues nearly offset the continued pressure from ongoing operating expenses, demonstrating the Bank’s ability to absorb strategic investments while preserving cost discipline, balancing investments in growth, modernization and transformation with a continued focus on operating leverage and efficiency.
14 | ||
CAPITAL RATIOS AND CAPITAL MANAGEMENT
The following table shows capital amounts and ratios as of the dates indicated:
| (US$ million, except percentages and shares outstanding) | 30-Sep-26 | 30-Jun-26 | 30-Sep-25 | QoQ (%) | YoY (%) | |||||||||||||||||||||||||||
| Common equity | $ | 1,592 | $ | 1,559 | $ | 1,448 | 2 | % | 10 | % | ||||||||||||||||||||||
| Other equity instruments | $ | 198 | $ | 198 | $ | 198 | 0 | % | 0 | % | ||||||||||||||||||||||
| Total equity | $ | 1,790 | $ | 1,757 | $ | 1,646 | 2 | % | 9 | % | ||||||||||||||||||||||
| Total assets / Total equity (times) | 9.2 | 8.2 | 7.6 | 12 | % | 21 | % | |||||||||||||||||||||||||
| Shares outstanding (in thousand) | 37,593 | 37,599 | 37,231 | 0 | % | 1 | % | |||||||||||||||||||||||||
Basel III International Framework (11) | ||||||||||||||||||||||||||||||||
| Risk-Weighted Assets (Basel III – IRB) | $ | 11,102 | $ | 10,545 | $ | 9,078 | 5 | % | 22 | % | ||||||||||||||||||||||
| Tier 1 capital to risk weighted assets (Basel III – IRB) | 16.2 | % | 16.6 | % | 18.1 | % | -48bps | -196bps | ||||||||||||||||||||||||
Panama's Banking Regulation (12) | ||||||||||||||||||||||||||||||||
| Risk-Weighted Assets | $ | 12,432 | $ | 12,132 | $ | 10,387 | 2 | % | 20 | % | ||||||||||||||||||||||
| Ordinary Common Tier 1 Capital Ratio | 11.3 | % | 11.3 | % | 12.5 | % | 5bps | -117bps | ||||||||||||||||||||||||
| Total Common Tier 1 Capital Ratio | 12.9 | % | 12.9 | % | 14.4 | % | 1bps | -148bps | ||||||||||||||||||||||||
| Capital Adequacy Ratio | 14.3 | % | 14.3 | % | 15.8 | % | -1bps | -145bps | ||||||||||||||||||||||||
The Bank’s equity mainly consists of issued and fully paid ordinary common stock, with 37.6 million common shares outstanding as of September 30, 2026. In addition, the Bank’s capital position considers the US$200 million inaugural Additional Tier 1 (AT1) capital issuance, registered in the Bank’s statement of financial position as other equity instruments, net of transaction costs.
As of September 30, 2026, the Tier 1 Basel III Capital Ratio, in which risk-weighted assets are calculated under the advanced internal ratings-based approach (IRB) for credit risk, resulted in 16.2%. Similarly, the Bank’s Capital Adequacy Ratio, as defined by Panama’s banking regulator under Basel’s standardized approach, was 14.3% as of September 30, 2026, well above the regulatory minimum of 10.5%. Additionally, the Bank’s Ordinary Common Tier 1 Capital Ratio, as defined by the Panama’s banking regulator, was 11.3% as of September 30, 2026, well above the regulatory minimum of 7%.
Recent Events:
•Quarterly dividend payment: The Board of Directors approved a quarterly common dividend of $0.6875 per share corresponding to 3Q26. The cash dividend will be paid on November 24, 2026, to shareholders registered as of November 6, 2026.
Notes:
•Numbers and percentages set forth in this earnings release have been rounded and accordingly may not total exactly.
•QoQ and YoY refer to quarter-on-quarter and year-on-year variations, respectively.
Footnotes:
1.Earnings per Share (“EPS”) calculation is based on profit attributable to common shareholders, after deducting distributions accrued on AT1 instruments, divided by the weighted-average number of common shares outstanding during the period.
15 | ||
2.ROE refers to return on average stockholders’ equity which is calculated based on unaudited daily average balances.
3.ROE excluding other equity instruments refers to the adjusted net profit after AT1 distributions over average stockholders’ equity excluding other equity instruments, which is calculated based on unaudited daily average balances.
4.ROA refers to return on average assets which is calculated based on unaudited daily average balances.
5.NIM refers to net interest margin which constitutes to Net Interest Income (“NII”) divided by the average balance of interest-earning assets.
6.NIS refers to net interest spread which constitutes the average yield earned on interest-earning assets, minus the average yield paid on interest-bearing liabilities.
7.Efficiency Ratio refers to consolidated operating expenses as a percentage of total revenues.
8.The Bank’s “Credit Portfolio” includes (i) loans – principal balance, which excludes interest receivable, allowance for loan losses, and unearned interest and deferred fees (or the “Loan Portfolio”); (ii) principal balance of securities at FVOCI and at amortized cost, which excludes interest receivable and allowance for expected credit losses; and (iii) loan commitments and financial guarantee contracts, such as confirmed and stand-by letters of credit and guarantees covering commercial risk and other assets consisting of customers’ liabilities under acceptances.
9.The Bank’s “Commercial Portfolio” includes loans – principal balance (or the “Loan Portfolio”), loan commitments and financial guarantee contracts, such as issued and confirmed letters of credit, stand-by letters of credit, guarantees covering commercial risk and other assets consisting of customers’ liabilities under acceptances; and the principal balance of investment securities managed by the Bank’s Commercial Unit (or the “Commercial Bond Portfolio”).
10.Market capitalization corresponds to total outstanding common shares multiplied by market close price at the end of each corresponding period.
11.Tier 1 Capital ratio is calculated according to Basel III capital adequacy guidelines, and as a percentage of risk-weighted assets. Risk-weighted assets are estimated based on Basel III capital adequacy guidelines, utilizing internal-ratings based approach or “IRB” for credit risk and standardized approach for operational risk.
12.As defined by the Superintendency of Banks of Panama (“SBP”) through Rules No. 01-2015, 03-2016 and 05-2023, based on Basel III standardized approach. The capital adequacy ratio is defined as the ratio of capital funds to risk-weighted assets, rated according to the asset’s categories for credit risk. In addition, risk-weighted assets consider calculations for market risk and operating risk.
13.Liquid assets consist of total cash and due from banks, excluding time deposits with original maturity over 90 days and other restricted deposits, as well as corporate debt securities rated A- or above. Liquidity ratio refers to liquid assets as a percentage of total assets.
14.The liquidity coverage ratio (“LCR”) is established by the Superintendency of Banks of Panama as the stock of high-quality liquid assets over total net cash outflows over the next 30 calendar days. The definition is based on the Basel III Liquidity Coverage Ratio and liquidity risk monitoring tools published by the Basel Committee on Banking Supervision and adjusted by the Superintendency of Banks of Panama.
15.Loan Portfolio refers to loans – principal balance, which excludes interest receivable, allowance for loan losses, and unearned interest and deferred fees. Credit-impaired loans are also commonly referred to as Non-Performing Loans or NPLs.
16.Impaired Credits refers to the principal balance of Non-Performing Loans or NPLs and non-performing securities at FVOCI and at amortized cost.
17.Total allowance for losses refers to allowance for loan losses plus allowance for loan commitments and financial guarantee contract losses, allowance for investment securities losses and allowance for cash and due from banks losses.
16 | ||
SAFE HARBOR STATEMENT
This press release contains forward-looking statements of expected future developments within the meaning of the Private Securities Litigation Reform Act of 1995 and Section 21E of the Securities Exchange Act of 1934. Forward-looking statements can be identified by words such as: “anticipate”, “intend”, “plan”, “goal”, “seek”, “believe”, “project”, “estimate”, “expect”, “strategy”, “future”, “likely”, “may”, “should”, “will” and similar references to future periods. The forward-looking statements in this press release include the Bank’s financial position, asset quality and profitability, among others. These forward-looking statements reflect the expectations of the Bank’s management and are based on currently available data; however, actual performance and results are subject to future events and uncertainties, which could materially impact the Bank’s expectations. Among the factors that can cause actual performance and results to differ materially are as follows: pandemic and geopolitical events; the anticipated changes in the Bank’s credit portfolio; the continuation of the Bank’s preferred creditor status; the impact of increasing/decreasing interest rates and of the macroeconomic environment in the Region on the Bank’s financial condition; the execution of the Bank’s strategies and initiatives, including its revenue diversification strategy; the adequacy of the Bank’s allowance for expected credit losses; the need for additional allowance for expected credit losses; the Bank’s ability to achieve future growth, to reduce its liquidity levels and increase its leverage; the Bank’s ability to maintain its investment-grade credit ratings; the availability and mix of future sources of funding for the Bank’s lending operations; potential trading losses; the possibility of fraud; and the adequacy of the Bank’s sources of liquidity to replace deposit withdrawals. Factors or events that could cause our actual results to differ may emerge from time to time, and it is not possible for us to predict all of them. Readers are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date hereof. We undertake no obligation to publicly update any forward-looking statement, whether as a result of new information, future developments or otherwise, except as may be required by law.
ABOUT BLADEX
Bladex, a multinational bank originally established by the central banks of Latin-American and Caribbean countries, began operations in 1979 to promote foreign trade and economic integration in the Region. The Bank, headquartered in Panama, also has offices in Argentina, Brazil, Colombia, Mexico, and the United States of America, and a Representative License in Peru, supporting the regional expansion and servicing its customer base, which includes financial institutions and corporations.
Bladex is listed on the NYSE in the United States of America (NYSE: BLX), since 1992, and its shareholders include: central banks and state-owned banks and entities representing 23 Latin American countries; commercial banks and financial institutions; and institutional and retail investors through its public listing.
CONFERENCE CALL INFORMATION
There will be a conference call to discuss the Bank’s quarterly results on Tuesday, October 27, 2026, at 11:00 a.m. New York City time (Eastern Time). For those interested in participating, please click here to pre-register to our conference call or visit our website at https://bladex.com/. Participants should register five minutes before the call is set to begin. The webcast presentation will be available for viewing and downloads on https://bladex.com/. The conference call will become available for review one hour after its conclusion.
For more information, please access https://bladex.com or contact:
 | Mr. Carlos Daniel Raad Chief Investor Relations Officer Tel: +507 366-4925 ext. 7925 E-mail: [email protected] / [email protected] | ||||
17 | ||
EXHIBIT I
CONSOLIDATED STATEMENTS OF FINANCIAL POSITION
| AT THE END OF, | |||||||||||||||||||||||||||||||||||||||||
| (A) | (B) | (C) | (A) - (B) | (A) - (C) | |||||||||||||||||||||||||||||||||||||
| September 30, 2026 | June 30, 2026 | September 30, 2025 | CHANGE | % | CHANGE | % | |||||||||||||||||||||||||||||||||||
| (In US$ thousand) | |||||||||||||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | $ | 1,841,669 | $ | 1,888,971 | $ | 1,961,507 | $ | (47,302) | (3) | % | $ | (119,838) | (6) | % | |||||||||||||||||||||||||||
| Investment securities | 1,821,093 | 1,683,153 | 1,426,520 | 137,940 | 8 | 394,573 | 28 | ||||||||||||||||||||||||||||||||||
| Loans | 12,321,300 | 10,465,018 | 8,726,282 | 1,856,282 | 18 | 3,595,018 | 41 | ||||||||||||||||||||||||||||||||||
| Customers' liabilities under acceptances | 318,933 | 198,040 | 260,173 | 120,893 | 61 | 58,760 | 23 | ||||||||||||||||||||||||||||||||||
| Trading derivative - assets | 31,587 | 6,317 | 1,079 | 25,270 | 400 | 30,508 | 2,827 | ||||||||||||||||||||||||||||||||||
| Hedging derivative financial instruments - assets | 78,888 | 96,886 | 64,810 | (17,998) | (19) | 14,078 | 22 | ||||||||||||||||||||||||||||||||||
| Equipment, right-of-use assets and leasehold improvements, net | 20,891 | 21,749 | 18,888 | (858) | (4) | 2,003 | 11 | ||||||||||||||||||||||||||||||||||
| Intangible assets | 9,277 | 9,906 | 11,553 | (629) | (6) | (2,276) | (20) | ||||||||||||||||||||||||||||||||||
| Other assets | 36,335 | 66,805 | 26,990 | (30,470) | (46) | 9,345 | 35 | ||||||||||||||||||||||||||||||||||
| Total assets | $ | 16,479,973 | $ | 14,436,845 | $ | 12,497,802 | $ | 2,043,128 | 14 | % | $ | 3,982,171 | 32 | % | |||||||||||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||||||||||||||
| Customer deposits | $ | 7,964,564 | $ | 7,934,541 | $ | 6,879,709 | $ | 30,023 | 0 | $ | 1,084,855 | 16 | |||||||||||||||||||||||||||||
| Securities sold under repurchase agreements | 248,514 | 275,310 | 141,922 | (26,796) | (10) | 106,592 | 75 | ||||||||||||||||||||||||||||||||||
| Borrowings and debt | 5,973,878 | 4,148,884 | 3,431,120 | 1,824,994 | 44 | 2,542,758 | 74 | ||||||||||||||||||||||||||||||||||
| Lease liabilities | 18,962 | 19,329 | 18,377 | (367) | (2) | 585 | 3 | ||||||||||||||||||||||||||||||||||
| Acceptance outstanding | 318,933 | 198,040 | 260,173 | 120,893 | 61 | 58,760 | 23 | ||||||||||||||||||||||||||||||||||
| Trading derivative - liabilities | 26,305 | 3,601 | 406 | 22,704 | 630 | 25,899 | 6,379 | ||||||||||||||||||||||||||||||||||
| Hedging derivative financial instruments - liabilities | 73,623 | 46,463 | 57,708 | 27,160 | 58 | 15,915 | 28 | ||||||||||||||||||||||||||||||||||
| Provisions for losses on loan commitments and financial guarantee contract | 11,548 | 11,967 | 13,311 | (419) | (4) | (1,763) | (13) | ||||||||||||||||||||||||||||||||||
| Other liabilities | 53,438 | 41,391 | 48,603 | 12,047 | 29 | 4,835 | 10 | ||||||||||||||||||||||||||||||||||
| Total liabilities | $ | 14,689,765 | $ | 12,679,526 | $ | 10,851,329 | $ | 2,010,239 | 16 | % | $ | 3,838,436 | 35 | % | |||||||||||||||||||||||||||
| Equity | |||||||||||||||||||||||||||||||||||||||||
| Common stock | $ | 279,980 | $ | 279,980 | $ | 279,980 | $ | 0 | 0 | % | $ | 0 | 0 | % | |||||||||||||||||||||||||||
| Treasury stock | (91,028) | (90,879) | (97,581) | (149) | 0 | 6,553 | 7 | ||||||||||||||||||||||||||||||||||
| Other equity instruments | 197,976 | 197,976 | 197,976 | 0 | 0 | 0 | 0 | ||||||||||||||||||||||||||||||||||
| Additional paid-in capital in excess of value assigned to common stock | 125,503 | 123,157 | 122,994 | 2,346 | 2 | 2,509 | 2 | ||||||||||||||||||||||||||||||||||
| Capital reserves | 95,210 | 95,210 | 95,210 | 0 | 0 | 0 | 0 | ||||||||||||||||||||||||||||||||||
| Regulatory reserves | 181,949 | 189,969 | 151,469 | (8,020) | (4) | 30,480 | 20 | ||||||||||||||||||||||||||||||||||
| Retained earnings | 987,029 | 949,206 | 891,325 | 37,823 | 4 | 95,704 | 11 | ||||||||||||||||||||||||||||||||||
| Other comprehensive income | 13,589 | 12,700 | 5,100 | 889 | 7 | 8,489 | 166 | ||||||||||||||||||||||||||||||||||
| Total equity | $ | 1,790,208 | $ | 1,757,319 | $ | 1,646,473 | $ | 32,889 | 2 | % | $ | 143,735 | 9 | % | |||||||||||||||||||||||||||
| Total liabilities and equity | $ | 16,479,973 | $ | 14,436,845 | $ | 12,497,802 | $ | 2,043,128 | 14 | % | $ | 3,982,171 | 32 | % | |||||||||||||||||||||||||||
18 | ||
EXHIBIT II
CONSOLIDATED STATEMENTS OF PROFIT OR LOSS
(In US$ thousand, except per share amounts and ratios)
| FOR THE THREE MONTHS ENDED | |||||||||||||||||||||||||||||||||||||||||
| (A) | (B) | (C) | (A) - (B) | (A) - (C) | |||||||||||||||||||||||||||||||||||||
| September 30, 2026 | June 30, 2026 | September 30, 2025 | CHANGE | % | CHANGE | % | |||||||||||||||||||||||||||||||||||
| Net Interest Income: | |||||||||||||||||||||||||||||||||||||||||
| Interest income | $ | 215,026 | $ | 199,217 | $ | 193,680 | $ | 15,809 | 8 | % | $ | 21,346 | 11 | % | |||||||||||||||||||||||||||
| Interest expense | (135,245) | (125,938) | (126,253) | (9,307) | (7) | (8,992) | (7) | ||||||||||||||||||||||||||||||||||
| Net Interest Income | 79,781 | 73,279 | 67,427 | 6,502 | 9 | 12,354 | 18 | ||||||||||||||||||||||||||||||||||
| Other income (expense): | |||||||||||||||||||||||||||||||||||||||||
| Fees and commissions, net | 16,299 | 23,335 | 14,052 | (7,036) | (30) | 2,247 | 16 | ||||||||||||||||||||||||||||||||||
| Gain on financial instruments, net | 2,971 | 2,191 | 882 | 780 | 36 | 2,089 | 237 | ||||||||||||||||||||||||||||||||||
| Other income | 69 | 97 | 416 | (28) | (29) | (347) | (83) | ||||||||||||||||||||||||||||||||||
| Total other income, net | 19,339 | 25,623 | 15,350 | (6,284) | (25) | 3,989 | 26 | ||||||||||||||||||||||||||||||||||
| Total revenues | 99,120 | 98,902 | 82,777 | 218 | 0 | 16,343 | 20 | ||||||||||||||||||||||||||||||||||
| Impairment losses on financial instruments | (10,412) | (8,599) | (6,482) | (1,813) | (21) | (3,930) | (61) | ||||||||||||||||||||||||||||||||||
| Operating expenses: | |||||||||||||||||||||||||||||||||||||||||
| Salaries and other employee expenses | (16,139) | (13,953) | (13,196) | (2,186) | (16) | (2,943) | (22) | ||||||||||||||||||||||||||||||||||
| Depreciation and amortization of equipment, right-of-use and leasehold improvements | (937) | (928) | (697) | (9) | (1) | (240) | (34) | ||||||||||||||||||||||||||||||||||
| Amortization of intangible assets | (708) | (726) | (355) | 18 | 2 | (353) | (99) | ||||||||||||||||||||||||||||||||||
| Other expenses | (7,774) | (8,242) | (7,079) | 468 | 6 | (695) | (10) | ||||||||||||||||||||||||||||||||||
| Total operating expenses | (25,558) | (23,849) | (21,327) | (1,709) | (7) | (4,231) | (20) | ||||||||||||||||||||||||||||||||||
| Profit for the period | $ | 63,150 | $ | 66,454 | $ | 54,968 | $ | (3,304) | (5) | % | $ | 8,182 | 15 | % | |||||||||||||||||||||||||||
| PER COMMON SHARE DATA: | |||||||||||||||||||||||||||||||||||||||||
| Basic earnings per share | $ | 1.48 | $ | 1.77 | $ | 1.48 | |||||||||||||||||||||||||||||||||||
| Book value (period average) | $ | 41.82 | $ | 40.71 | $ | 38.52 | |||||||||||||||||||||||||||||||||||
| Book value (period end) | $ | 42.35 | $ | 41.47 | $ | 38.91 | |||||||||||||||||||||||||||||||||||
| Weighted average basic shares (in thousands of shares) | 37,597 | 37,579 | 37,231 | ||||||||||||||||||||||||||||||||||||||
| Basic shares period end (in thousands of shares) | 37,593 | 37,599 | 37,231 | ||||||||||||||||||||||||||||||||||||||
| PERFORMANCE RATIOS: | |||||||||||||||||||||||||||||||||||||||||
| Return on average assets | 1.8 | % | 2.0 | % | 1.8 | % | |||||||||||||||||||||||||||||||||||
| Return on average equity | 14.2 | % | 15.4 | % | 14.9 | % | |||||||||||||||||||||||||||||||||||
| Net interest margin | 2.30 | % | 2.24 | % | 2.32 | % | |||||||||||||||||||||||||||||||||||
| Net interest spread | 1.73 | % | 1.64 | % | 1.64 | % | |||||||||||||||||||||||||||||||||||
| Efficiency Ratio | 25.8 | % | 24.1 | % | 25.8 | % | |||||||||||||||||||||||||||||||||||
| Operating expenses to total average assets | 0.71 | % | 0.71 | % | 0.70 | % | |||||||||||||||||||||||||||||||||||
19 | ||
EXHIBIT III
CONSOLIDATED STATEMENTS OF PROFIT OR LOSS
(In US$ thousand, except per share amounts and ratios)
| FOR THE NINE MONTHS ENDED | |||||||||||||||||||||||
| (A) | (B) | (A) - (B) | |||||||||||||||||||||
| September 30, 2026 | September 30, 2025 | CHANGE | % | ||||||||||||||||||||
| Net Interest Income: | |||||||||||||||||||||||
| Interest income | $ | 600,191 | $ | 577,531 | $ | 22,660 | 4 | % | |||||||||||||||
| Interest expense | (376,925) | (377,109) | 184 | 0 | |||||||||||||||||||
| Net Interest Income | 223,266 | 200,422 | 22,844 | 11 | |||||||||||||||||||
| Other income (expense): | |||||||||||||||||||||||
| Fees and commissions, net | 52,764 | 44,547 | 8,217 | 18 | |||||||||||||||||||
| Gain on financial instruments, net | 4,832 | 5,027 | (195) | (4) | |||||||||||||||||||
| Other income | 260 | 772 | (512) | (66) | |||||||||||||||||||
| Total other income, net | 57,856 | 50,346 | 7,510 | 15 | |||||||||||||||||||
| Total revenues | 281,122 | 250,768 | 30,354 | 12 | |||||||||||||||||||
| Impairment losses on financial instruments | (23,745) | (16,717) | (7,028) | (42) | |||||||||||||||||||
| Operating expenses: | |||||||||||||||||||||||
| Salaries and other employee expenses | (43,441) | (39,518) | (3,923) | (10) | |||||||||||||||||||
| Depreciation and amortization of equipment, right-of-use and leasehold improvements | (2,764) | (2,111) | (653) | (31) | |||||||||||||||||||
| Amortization of intangible assets | (2,136) | (1,029) | (1,107) | (108) | |||||||||||||||||||
| Other expenses | (23,077) | (20,509) | (2,568) | (13) | |||||||||||||||||||
| Total operating expenses | (71,418) | (63,167) | (8,251) | (13) | |||||||||||||||||||
| Profit for the period | $ | 185,959 | $ | 170,884 | $ | 15,075 | 9 | % | |||||||||||||||
| PER COMMON SHARE DATA: | |||||||||||||||||||||||
| Basic earnings per share | $ | 4.56 | $ | 4.60 | |||||||||||||||||||
| Book value (period average) | $ | 40.90 | $ | 37.62 | |||||||||||||||||||
| Book value (period end) | $ | 42.35 | $ | 38.91 | |||||||||||||||||||
| Weighted average basic shares (in thousands of shares) | 37,521 | 37,126 | |||||||||||||||||||||
| Basic shares period end (in thousands of shares) | 37,593 | 37,231 | |||||||||||||||||||||
| PERFORMANCE RATIOS: | |||||||||||||||||||||||
| Return on average assets | 1.9 | % | 1.9 | % | |||||||||||||||||||
| Return on average equity | 14.3 | % | 16.2 | % | |||||||||||||||||||
| Net interest margin | 2.29 | % | 2.35 | % | |||||||||||||||||||
| Net interest spread | 1.69 | % | 1.66 | % | |||||||||||||||||||
| Efficiency Ratio | 25.4 | % | 25.2 | % | |||||||||||||||||||
| Operating expenses to total average assets | 0.71 | % | 0.70 | % | |||||||||||||||||||
20 | ||
EXHIBIT IV
CONSOLIDATED NET INTEREST INCOME AND AVERAGE BALANCES
| FOR THE THREE MONTHS ENDED | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| September 30, 2026 | June 30, 2026 | September 30, 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| (In US$ thousand, except percentages) | AVERAGE BALANCE | INTEREST | AVG. RATE | AVERAGE BALANCE | INTEREST | AVG. RATE | AVERAGE BALANCE | INTEREST | AVG. RATE | ||||||||||||||||||||||||||||||||||||||||||||
| (In US$ thousand) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| INTEREST EARNING ASSETS | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Cash and due from banks (1) | $ | 1,261,125 | $ | 12,084 | 3.75 | % | $ | 1,525,657 | $ | 14,075 | 3.65 | % | $ | 1,776,862 | $ | 19,413 | 4.28 | % | |||||||||||||||||||||||||||||||||||
| Securities at fair value through OCI | 362,954 | 4,936 | 5.32 | 296,011 | 4,196 | 5.61 | 98,851 | 1,551 | 6.14 | ||||||||||||||||||||||||||||||||||||||||||||
Securities at amortized cost (2) | 1,427,382 | 17,021 | 4.67 | 1,377,221 | 16,198 | 4.65 | 1,292,714 | 15,860 | 4.80 | ||||||||||||||||||||||||||||||||||||||||||||
Loans, net of unearned interest (2) | 10,706,612 | 180,985 | 6.61 | 9,922,103 | 164,748 | 6.57 | 8,362,075 | 156,856 | 7.34 | ||||||||||||||||||||||||||||||||||||||||||||
| TOTAL INTEREST EARNING ASSETS | $ | 13,758,072 | $ | 215,026 | 6.12 | % | $ | 13,120,991 | $ | 199,217 | 6.01 | % | $ | 11,530,503 | $ | 193,680 | 6.57 | % | |||||||||||||||||||||||||||||||||||
| Allowance for loan losses | (78,410) | (98,322) | (70,423) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Non interest earning assets | 550,759 | 489,632 | 670,515 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| TOTAL ASSETS | $ | 14,230,422 | $ | 13,512,301 | $ | 12,130,594 | |||||||||||||||||||||||||||||||||||||||||||||||
| INTEREST BEARING LIABILITIES | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Deposits | 7,659,991 | $ | 80,689 | 4.12 | % | 7,206,231 | $ | 74,203 | 4.07 | % | $ | 6,266,028 | $ | 75,177 | 4.69 | % | |||||||||||||||||||||||||||||||||||||
| Securities sold under repurchase agreement | 190,268 | 2,082 | 4.28 | 197,557 | 2,200 | 4.40 | 138,854 | 1,752 | 4.94 | ||||||||||||||||||||||||||||||||||||||||||||
| Short-term borrowings and debt | 1,556,030 | 17,237 | 4.33 | 1,334,634 | 15,076 | 4.47 | 986,521 | 12,314 | 4.88 | ||||||||||||||||||||||||||||||||||||||||||||
Long-term borrowings and debt, net (3) | 2,668,315 | 35,237 | 5.17 | 2,672,089 | 34,459 | 5.10 | 2,617,867 | 37,010 | 5.53 | ||||||||||||||||||||||||||||||||||||||||||||
| TOTAL INTEREST BEARING LIABILITIES | $ | 12,074,604 | $ | 135,245 | 4.38 | % | $ | 11,410,511 | $ | 125,938 | 4.37 | % | $ | 10,009,270 | $ | 126,253 | 4.94 | % | |||||||||||||||||||||||||||||||||||
| Non interest bearing liabilities and other liabilities | $ | 385,614 | $ | 373,833 | $ | 659,304 | |||||||||||||||||||||||||||||||||||||||||||||||
| TOTAL LIABILITIES | 12,460,218 | 11,784,343 | 10,668,574 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| TOTAL EQUITY | 1,770,204 | 1,727,958 | 1,462,020 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| TOTAL LIABILITIES AND EQUITY | $ | 14,230,422 | $ | 13,512,301 | $ | 12,130,594 | |||||||||||||||||||||||||||||||||||||||||||||||
| NET INTEREST SPREAD | 1.73 | % | 1.64 | % | 1.64 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| NET INTEREST INCOME AND NET INTEREST MARGIN | $ | 79,781 | 2.30 | % | $ | 73,279 | 2.24 | % | $ | 67,427 | 2.32 | % | |||||||||||||||||||||||||||||||||||||||||
(1)Gross of interest receivable and the allowance for losses relating to deposits.
(2)Gross of interest receivable and the allowance for losses relating to financial instruments at amortized cost.
(3)Includes lease liabilities, net of prepaid commissions.
Note: Interest income and/or expense includes the effect of derivative financial instruments used for hedging.
21 | ||
EXHIBIT V
CONSOLIDATED NET INTEREST INCOME AND AVERAGE BALANCES
| FOR THE NINE MONTHS ENDED | |||||||||||||||||||||||||||||||||||
| September 30, 2026 | September 30, 2025 | ||||||||||||||||||||||||||||||||||
| (In US$ thousand, except percentages) | AVERAGE BALANCE | INTEREST | AVG. RATE | AVERAGE BALANCE | INTEREST | AVG. RATE | |||||||||||||||||||||||||||||
| (In US$ thousand) | |||||||||||||||||||||||||||||||||||
| INTEREST EARNING ASSETS | |||||||||||||||||||||||||||||||||||
Cash and due from banks (1) | $ | 1,402,566 | $ | 39,351 | 3.70 | % | $ | 1,692,594 | $ | 55,106 | 4.29 | % | |||||||||||||||||||||||
| Securities at fair value through OCI | 275,420 | 11,264 | 5.39 | 115,229 | 5,119 | 5.86 | |||||||||||||||||||||||||||||
Securities at amortized cost (2) | 1,392,397 | 49,483 | 4.69 | 1,188,775 | 42,773 | 4.74 | |||||||||||||||||||||||||||||
Loans, net of unearned interest (2) | 9,947,216 | 500,093 | 6.63 | 8,422,429 | 474,533 | 7.43 | |||||||||||||||||||||||||||||
| TOTAL INTEREST EARNING ASSETS | $ | 13,017,598 | $ | 600,191 | 6.08 | % | $ | 11,419,027 | $ | 577,531 | 6.67 | % | |||||||||||||||||||||||
| Allowance for loan losses | (90,490) | (63,446) | |||||||||||||||||||||||||||||||||
| Non interest earning assets | 490,092 | 650,187 | |||||||||||||||||||||||||||||||||
| TOTAL ASSETS | $ | 13,417,201 | $ | 12,005,769 | |||||||||||||||||||||||||||||||
| INTEREST BEARING LIABILITIES | |||||||||||||||||||||||||||||||||||
| Deposits | $ | 7,183,567 | $ | 223,531 | 4.10 | % | $ | 6,037,605 | $ | 217,563 | 4.75 | % | |||||||||||||||||||||||
| Securities sold under repurchase agreement | 176,960 | $ | 5,922 | 4.41 | 187,325 | $ | 7,013 | 4.94 | |||||||||||||||||||||||||||
| Short-term borrowings and debt | 1,326,758 | $ | 44,414 | 4.41 | 1,008,049 | $ | 38,067 | 4.98 | |||||||||||||||||||||||||||
Long-term borrowings and debt, net (3) | 2,628,399 | 103,058 | 5.17 | 2,698,946 | 114,466 | 5.59 | |||||||||||||||||||||||||||||
| TOTAL INTEREST BEARING LIABILITIES | $ | 11,315,684 | $ | 376,925 | 4.39 | % | $ | 9,931,925 | $ | 377,109 | 5.01 | % | |||||||||||||||||||||||
| Non interest bearing liabilities and other liabilities | $ | 368,807 | $ | 667,576 | |||||||||||||||||||||||||||||||
| TOTAL LIABILITIES | 11,684,491 | 10,599,501 | |||||||||||||||||||||||||||||||||
| TOTAL EQUITY | 1,732,709 | 1,406,268 | |||||||||||||||||||||||||||||||||
| TOTAL LIABILITIES AND EQUITY | $ | 13,417,201 | $ | 12,005,769 | |||||||||||||||||||||||||||||||
| NET INTEREST SPREAD | 1.69 | % | 1.66 | % | |||||||||||||||||||||||||||||||
| NET INTEREST INCOME AND NET INTEREST MARGIN | $ | 223,266 | 2.29 | % | $ | 200,422 | 2.35 | % | |||||||||||||||||||||||||||
(1)Gross of interest receivable and the allowance for losses relating to deposits.
(2)Gross of interest receivable and the allowance for losses relating to financial instruments at amortized cost.
(3)Includes lease liabilities, net of prepaid commissions.
Note: Interest income and/or expense includes the effect of derivative financial instruments used for hedging.
22 | ||
EXHIBIT VI
CONSOLIDATED STATEMENT OF PROFIT OR LOSS
(In US$ thousand, except per share amounts and ratios)
| NINE MONTHS ENDED | FOR THE THREE MONTHS ENDED | NINE MONTHS ENDED | |||||||||||||||||||||||||||||||||||||||
| SEP 30/26 | SEP 30/26 | JUN 30/26 | MAR 31/26 | DEC 31/25 | SEP 30/25 | SEP 30/25 | |||||||||||||||||||||||||||||||||||
| Net Interest Income: | |||||||||||||||||||||||||||||||||||||||||
| Interest income | $ | 600,191 | $ | 215,026 | $ | 199,217 | $ | 185,948 | $ | 190,933 | $ | 193,680 | $ | 577,531 | |||||||||||||||||||||||||||
| Interest expense | (376,925) | (135,245) | (125,938) | (115,742) | (120,173) | (126,253) | (377,109) | ||||||||||||||||||||||||||||||||||
| Net Interest Income | 223,266 | 79,781 | 73,279 | 70,206 | 70,760 | 67,427 | 200,422 | ||||||||||||||||||||||||||||||||||
| Other income (expense): | |||||||||||||||||||||||||||||||||||||||||
| Fees and commissions, net | 52,764 | 16,299 | 23,335 | 13,130 | 14,466 | 14,052 | 44,547 | ||||||||||||||||||||||||||||||||||
| Gain (loss) on financial instruments, net | 4,832 | 2,971 | 2,191 | (330) | 3,204 | 882 | 5,027 | ||||||||||||||||||||||||||||||||||
| Other income | 260 | 69 | 97 | 94 | 372 | 416 | 772 | ||||||||||||||||||||||||||||||||||
| Total other income, net | 57,856 | 19,339 | 25,623 | 12,894 | 18,042 | 15,350 | 50,346 | ||||||||||||||||||||||||||||||||||
| Total revenues | 281,122 | 99,120 | 98,902 | 83,100 | 88,802 | 82,777 | 250,768 | ||||||||||||||||||||||||||||||||||
| Impairment losses on financial instruments | (23,745) | (10,412) | (8,599) | (4,734) | (5,402) | (6,482) | (16,717) | ||||||||||||||||||||||||||||||||||
| Total operating expenses | (71,418) | (25,558) | (23,849) | (22,011) | (27,402) | (21,327) | (63,167) | ||||||||||||||||||||||||||||||||||
| Profit for the period | $ | 185,959 | $ | 63,150 | $ | 66,454 | $ | 56,355 | $ | 55,998 | $ | 54,968 | $ | 170,884 | |||||||||||||||||||||||||||
| SELECTED FINANCIAL DATA | |||||||||||||||||||||||||||||||||||||||||
| PER COMMON SHARE DATA | |||||||||||||||||||||||||||||||||||||||||
| Basic earnings per share | $ | 4.56 | $ | 1.48 | $ | 1.77 | $ | 1.31 | $ | 1.50 | $ | 1.48 | $ | 4.60 | |||||||||||||||||||||||||||
| PERFORMANCE RATIOS | |||||||||||||||||||||||||||||||||||||||||
| Return on average assets | 1.9 | % | 1.8 | % | 2.0 | % | 1.8 | % | 1.8 | % | 1.8 | % | 1.9 | % | |||||||||||||||||||||||||||
| Return on average equity | 14.3 | % | 14.2 | % | 15.4 | % | 13.5 | % | 13.4 | % | 14.9 | % | 16.2 | % | |||||||||||||||||||||||||||
| Net interest margin | 2.29 | % | 2.30 | % | 2.24 | % | 2.34 | % | 2.39 | % | 2.32 | % | 2.35 | % | |||||||||||||||||||||||||||
| Net interest spread | 1.69 | % | 1.73 | % | 1.64 | % | 1.69 | % | 1.68 | % | 1.64 | % | 1.66 | % | |||||||||||||||||||||||||||
| Efficiency Ratio | 25.4 | % | 25.8 | % | 24.1 | % | 26.5 | % | 30.9 | % | 25.8 | % | 25.2 | % | |||||||||||||||||||||||||||
| Operating expenses to total average assets | 0.71 | % | 0.71 | % | 0.71 | % | 0.71 | % | 0.90 | % | 0.70 | % | 0.70 | % | |||||||||||||||||||||||||||
23 | ||
EXHIBIT VII
BUSINESS SEGMENT ANALYSIS
(In US$ thousand)
| FOR THE NINE MONTHS ENDED | FOR THE THREE MONTHS ENDED | ||||||||||||||||||||||||||||
| SEP 30/26 | SEP 30/25 | SEP 30/26 | JUN 30/26 | SEP 30/25 | |||||||||||||||||||||||||
| COMMERCIAL BUSINESS SEGMENT: | |||||||||||||||||||||||||||||
| Net interest income | $ | 202,926 | $ | 178,679 | $ | 74,664 | $ | 65,985 | $ | 59,993 | |||||||||||||||||||
| Other income, net | 53,605 | 47,675 | 16,540 | 23,657 | 15,276 | ||||||||||||||||||||||||
| Total revenues | 256,531 | 226,354 | 91,204 | 89,642 | 75,269 | ||||||||||||||||||||||||
| Impairment losses on financial instruments | (24,378) | (16,752) | (10,493) | (8,656) | (6,495) | ||||||||||||||||||||||||
| Operating expenses | (56,335) | (49,979) | (20,192) | (18,764) | (16,787) | ||||||||||||||||||||||||
| Profit for the segment | $ | 175,818 | $ | 159,623 | $ | 60,519 | $ | 62,222 | $ | 51,987 | |||||||||||||||||||
| Segment assets | 12,860,971 | 9,013,269 | 12,860,971 | 10,916,767 | 9,013,269 | ||||||||||||||||||||||||
| TREASURY BUSINESS SEGMENT: | |||||||||||||||||||||||||||||
| Net interest income | $ | 20,340 | $ | 21,743 | $ | 5,117 | $ | 7,294 | $ | 7,434 | |||||||||||||||||||
| Other income, net | 4,251 | 2,671 | 2,799 | 1,966 | 74 | ||||||||||||||||||||||||
| Total revenues | 24,591 | 24,414 | 7,916 | 9,260 | 7,508 | ||||||||||||||||||||||||
| Reversals on financial instruments | 633 | 35 | 81 | 57 | 13 | ||||||||||||||||||||||||
| Operating expenses | (15,083) | (13,188) | (5,366) | (5,085) | (4,540) | ||||||||||||||||||||||||
| Profit for the segment | $ | 10,141 | $ | 11,261 | $ | 2,631 | $ | 4,232 | $ | 2,981 | |||||||||||||||||||
| Segment assets | 3,582,667 | 3,455,819 | 3,582,667 | 3,453,273 | 3,455,819 | ||||||||||||||||||||||||
| TOTAL: | |||||||||||||||||||||||||||||
| Net interest income | $ | 223,266 | $ | 200,422 | $ | 79,781 | $ | 73,279 | $ | 67,427 | |||||||||||||||||||
| Other income, net | 57,856 | 50,346 | 19,339 | 25,623 | 15,350 | ||||||||||||||||||||||||
| Total revenues | 281,122 | 250,768 | 99,120 | 98,902 | 82,777 | ||||||||||||||||||||||||
| Impairment losses on financial instruments | (23,745) | (16,717) | (10,412) | (8,599) | (6,482) | ||||||||||||||||||||||||
| Operating expenses | (71,418) | (63,167) | (25,558) | (23,849) | (21,327) | ||||||||||||||||||||||||
| Profit for the period | $ | 185,959 | $ | 170,884 | $ | 63,150 | $ | 66,454 | $ | 54,968 | |||||||||||||||||||
| Total segment assets | 16,443,638 | 12,469,088 | 16,443,638 | 14,370,040 | 12,469,088 | ||||||||||||||||||||||||
| Unallocated assets | 36,335 | 28,714 | 36,335 | 66,805 | 28,714 | ||||||||||||||||||||||||
| Total assets | 16,479,973 | 12,497,802 | 16,479,973 | 14,436,845 | 12,497,802 | ||||||||||||||||||||||||
24 | ||
EXHIBIT VIII
CREDIT PORTFOLIO
DISTRIBUTION BY COUNTRY
(principal balance in US$ million)
| AT THE END OF, | ||||||||||||||||||||||||||||||||||||||||||||||||||
| (A) | (B) | (C) | ||||||||||||||||||||||||||||||||||||||||||||||||
| September 30, 2026 | June 30, 2026 | September 30, 2025 | Change in Amount | |||||||||||||||||||||||||||||||||||||||||||||||
| COUNTRY | Amount | % of Total Outstanding | Amount | % of Total Outstanding | Amount | % of Total Outstanding | (A) - (B) | (A) - (C) | ||||||||||||||||||||||||||||||||||||||||||
| ARGENTINA | $ | 905 | 5 | $ | 659 | 5 | $ | 394 | 3 | $ | 246 | $ | 511 | |||||||||||||||||||||||||||||||||||||
| BRAZIL | 1,407 | 8 | 1,533 | 11 | 1,435 | 12 | (126) | (28) | ||||||||||||||||||||||||||||||||||||||||||
| CHILE | 743 | 4 | 684 | 5 | 576 | 5 | 59 | 167 | ||||||||||||||||||||||||||||||||||||||||||
| COLOMBIA | 1,701 | 10 | 1,340 | 9 | 826 | 7 | 361 | 875 | ||||||||||||||||||||||||||||||||||||||||||
| COSTA RICA | 528 | 3 | 479 | 3 | 492 | 4 | 49 | 36 | ||||||||||||||||||||||||||||||||||||||||||
| DOMINICAN REPUBLIC | 1,213 | 7 | 1,166 | 8 | 952 | 8 | 47 | 261 | ||||||||||||||||||||||||||||||||||||||||||
| ECUADOR | 727 | 4 | 656 | 5 | 516 | 4 | 71 | 211 | ||||||||||||||||||||||||||||||||||||||||||
| EL SALVADOR | 255 | 2 | 231 | 2 | 117 | 1 | 24 | 138 | ||||||||||||||||||||||||||||||||||||||||||
| GUATEMALA | 1,621 | 10 | 1,777 | 12 | 1,455 | 12 | (156) | 166 | ||||||||||||||||||||||||||||||||||||||||||
| HONDURAS | 137 | 1 | 168 | 1 | 179 | 1 | (31) | (42) | ||||||||||||||||||||||||||||||||||||||||||
| JAMAICA | 76 | 1 | 40 | 0 | 43 | 0 | 36 | 33 | ||||||||||||||||||||||||||||||||||||||||||
| MEXICO | 1,254 | 8 | 1,323 | 9 | 1,345 | 11 | (69) | (91) | ||||||||||||||||||||||||||||||||||||||||||
| PANAMA | 2,482 | 15 | 1,219 | 8 | 602 | 5 | 1,263 | 1,880 | ||||||||||||||||||||||||||||||||||||||||||
| PARAGUAY | 191 | 1 | 144 | 1 | 192 | 2 | 47 | (1) | ||||||||||||||||||||||||||||||||||||||||||
| PERU | 575 | 3 | 529 | 4 | 481 | 4 | 46 | 94 | ||||||||||||||||||||||||||||||||||||||||||
| PUERTO RICO | 1 | 0 | 2 | 0 | 26 | 0 | (1) | (25) | ||||||||||||||||||||||||||||||||||||||||||
| SURINAME | 150 | 1 | 150 | 1 | 150 | 1 | 0 | 0 | ||||||||||||||||||||||||||||||||||||||||||
| TRINIDAD & TOBAGO | 111 | 1 | 199 | 1 | 180 | 1 | (88) | (69) | ||||||||||||||||||||||||||||||||||||||||||
| UNITED STATES OF AMERICA | 923 | 6 | 885 | 6 | 1,026 | 8 | 38 | (103) | ||||||||||||||||||||||||||||||||||||||||||
| URUGUAY | 29 | 0 | 58 | 0 | 191 | 2 | (29) | (162) | ||||||||||||||||||||||||||||||||||||||||||
| MULTILATERAL ORGANIZATIONS | 76 | 1 | 76 | 1 | 77 | 1 | 0 | (1) | ||||||||||||||||||||||||||||||||||||||||||
OTHER NON-LATAM (1) | 1,479 | 9 | 1,148 | 8 | 1,031 | 8 | 331 | 448 | ||||||||||||||||||||||||||||||||||||||||||
TOTAL CREDIT PORTFOLIO (2) | $ | 16,584 | 100 | % | $ | 14,466 | 100 | % | $ | 12,286 | 100 | % | $ | 2,118 | $ | 4,298 | ||||||||||||||||||||||||||||||||||
| INTEREST RECEIVABLE | 144 | 137 | 109 | 7 | 35 | |||||||||||||||||||||||||||||||||||||||||||||
| UNEARNED INTEREST AND DEFERRED FEES | (39) | (34) | (31) | (5) | (8) | |||||||||||||||||||||||||||||||||||||||||||||
| TOTAL CREDIT PORTFOLIO, NET OF INTEREST RECEIVABLE, UNEARNED INTEREST & DEFERRED FEES | $ | 16,689 | $ | 14,569 | $ | 12,364 | $ | 2,120 | $ | 4,325 | ||||||||||||||||||||||||||||||||||||||||
(1)Risk in highly rated countries outside the Region related to transactions carried out in the Region. As of September 30, 2026, “Other Non-Latam” was comprised of Canada ($93 million), European countries ($693 million) and Asian-Pacific countries ($693 million).
(2)Includes (i) loans - principal balance (or the "Loan Portfolio"); (ii) principal balance of securities at FVOCI and at amortized cost, gross of interest receivable and the allowance for expected credit losses; and (iii) loan commitments and financial guarantee contracts, such as confirmed and stand-by letters of credit, and guarantees covering commercial risk; and other assets consisting of customers liabilities under acceptances.
25 | ||
EXHIBIT IX
COMMERCIAL PORTFOLIO
DISTRIBUTION BY COUNTRY
(principal balance in US$ million)
| AT THE END OF, | ||||||||||||||||||||||||||||||||||||||||||||||||||
| (A) | (B) | (C) | ||||||||||||||||||||||||||||||||||||||||||||||||
| September 30, 2026 | June 30, 2026 | September 30, 2025 | Change in Amount | |||||||||||||||||||||||||||||||||||||||||||||||
| COUNTRY | Amount | % of Total Outstanding | Amount | % of Total Outstanding | Amount | % of Total Outstanding | (A) - (B) | (A) - (C) | ||||||||||||||||||||||||||||||||||||||||||
| ARGENTINA | $ | 905 | 6 | $ | 659 | 5 | $ | 394 | 4 | $ | 246 | $ | 511 | |||||||||||||||||||||||||||||||||||||
| BRAZIL | 1,407 | 9 | 1,533 | 12 | 1,428 | 13 | (126) | (21) | ||||||||||||||||||||||||||||||||||||||||||
| CHILE | 679 | 5 | 620 | 5 | 546 | 5 | 59 | 133 | ||||||||||||||||||||||||||||||||||||||||||
| COLOMBIA | 1,701 | 11 | 1,340 | 10 | 770 | 7 | 361 | 931 | ||||||||||||||||||||||||||||||||||||||||||
| COSTA RICA | 528 | 3 | 479 | 4 | 484 | 4 | 49 | 44 | ||||||||||||||||||||||||||||||||||||||||||
| DOMINICAN REPUBLIC | 1,213 | 8 | 1,166 | 9 | 952 | 9 | 47 | 261 | ||||||||||||||||||||||||||||||||||||||||||
| ECUADOR | 727 | 5 | 656 | 5 | 516 | 5 | 71 | 211 | ||||||||||||||||||||||||||||||||||||||||||
| EL SALVADOR | 255 | 2 | 231 | 2 | 117 | 1 | 24 | 138 | ||||||||||||||||||||||||||||||||||||||||||
| GUATEMALA | 1,621 | 11 | 1,777 | 14 | 1,455 | 13 | (156) | 166 | ||||||||||||||||||||||||||||||||||||||||||
| HONDURAS | 137 | 1 | 168 | 1 | 179 | 2 | (31) | (42) | ||||||||||||||||||||||||||||||||||||||||||
| JAMAICA | 76 | 1 | 40 | 0 | 43 | 0 | 36 | 33 | ||||||||||||||||||||||||||||||||||||||||||
| MEXICO | 1,254 | 8 | 1,323 | 10 | 1,342 | 12 | (69) | (88) | ||||||||||||||||||||||||||||||||||||||||||
| PANAMA | 2,477 | 17 | 1,214 | 9 | 528 | 5 | 1,263 | 1,949 | ||||||||||||||||||||||||||||||||||||||||||
| PARAGUAY | 191 | 1 | 144 | 1 | 192 | 2 | 47 | (1) | ||||||||||||||||||||||||||||||||||||||||||
| PERU | 573 | 4 | 527 | 4 | 471 | 4 | 46 | 102 | ||||||||||||||||||||||||||||||||||||||||||
| PUERTO RICO | 1 | 0 | 2 | 0 | 26 | 0 | (1) | (25) | ||||||||||||||||||||||||||||||||||||||||||
| SURINAME | 150 | 1 | 150 | 1 | 150 | 1 | 0 | 0 | ||||||||||||||||||||||||||||||||||||||||||
| TRINIDAD & TOBAGO | 111 | 1 | 199 | 2 | 180 | 2 | (88) | (69) | ||||||||||||||||||||||||||||||||||||||||||
| URUGUAY | 29 | 0 | 58 | 0 | 191 | 2 | (29) | (162) | ||||||||||||||||||||||||||||||||||||||||||
OTHER NON-LATAM (1) | 941 | 6 | 743 | 6 | 908 | 8 | 198 | 33 | ||||||||||||||||||||||||||||||||||||||||||
TOTAL COMMERCIAL PORTFOLIO (2) | $ | 14,976 | 100 | % | $ | 13,029 | 100 | % | $ | 10,872 | 100 | % | $ | 1,947 | $ | 4,104 | ||||||||||||||||||||||||||||||||||
| INTEREST RECEIVABLE | 125 | 116 | 96 | 9 | 29 | |||||||||||||||||||||||||||||||||||||||||||||
| UNEARNED INTEREST AND DEFERRED FEES | (39) | (34) | (31) | (5) | (8) | |||||||||||||||||||||||||||||||||||||||||||||
| TOTAL COMMERCIAL PORTFOLIO, NET OF INTEREST RECEIVABLE, UNEARNED INTEREST & DEFERRED FEES | $ | 15,062 | $ | 13,111 | $ | 10,937 | $ | 1,951 | $ | 4,125 | ||||||||||||||||||||||||||||||||||||||||
(1)Risk in highly rated countries outside the Region related to transactions carried out in the Region. As of September 30, 2026, “Other Non-Latam” was comprised of United States of America ($100 million), Canada ($42 million), European countries ($454 million) and Asian-Pacific countries ($345 million).
(2)Includes loans - principal balance (or the “Loan Portfolio”), loan commitments and financial guarantee contracts, such as confirmed and stand-by letters of credit, guarantees covering commercial risk and other assets consisting of customers’ liabilities under acceptances; and investment securities managed by the Commercial business unit (or “Commercial Bond Portfolio”).
26 | ||
EXHIBIT X
TREASURY INVESTMENT PORTFOLIO
DISTRIBUTION BY COUNTRY
(principal balance in US$ million)
| AT THE END OF, | ||||||||||||||||||||||||||||||||||||||||||||||||||
| (A) | (B) | (C) | ||||||||||||||||||||||||||||||||||||||||||||||||
| September 30, 2026 | June 30, 2026 | September 30, 2025 | Change in Amount | |||||||||||||||||||||||||||||||||||||||||||||||
| COUNTRY | Amount | % of Total Outstanding | Amount | % of Total Outstanding | Amount | % of Total Outstanding | (A) - (B) | (A) - (C) | ||||||||||||||||||||||||||||||||||||||||||
| BRAZIL | $ | 0 | 0 | $ | 0 | 0 | $ | 7 | 1 | $ | 0 | $ | (7) | |||||||||||||||||||||||||||||||||||||
| CHILE | 64 | 4 | 64 | 5 | 30 | 2 | 0 | 34 | ||||||||||||||||||||||||||||||||||||||||||
| COLOMBIA | 0 | 0 | 0 | 0 | 56 | 4 | 0 | (56) | ||||||||||||||||||||||||||||||||||||||||||
| COSTA RICA | 0 | 0 | 0 | 0 | 8 | 1 | 0 | (8) | ||||||||||||||||||||||||||||||||||||||||||
| MEXICO | 0 | 0 | 0 | 0 | 3 | 0 | 0 | (3) | ||||||||||||||||||||||||||||||||||||||||||
| PANAMA | 5 | 0 | 5 | 0 | 74 | 5 | 0 | (69) | ||||||||||||||||||||||||||||||||||||||||||
| PERU | 2 | 0 | 2 | 0 | 10 | 1 | 0 | (8) | ||||||||||||||||||||||||||||||||||||||||||
| UNITED STATES OF AMERICA | 823 | 51 | 783 | 55 | 750 | 53 | 40 | 73 | ||||||||||||||||||||||||||||||||||||||||||
| MULTILATERAL ORGANIZATIONS | 76 | 5 | 76 | 5 | 77 | 5 | 0 | (1) | ||||||||||||||||||||||||||||||||||||||||||
OTHER NON-LATAM (1) | 638 | 40 | 507 | 35 | 399 | 28 | 131 | 239 | ||||||||||||||||||||||||||||||||||||||||||
TOTAL TREASURY INVESTMENT PORTFOLIO (2) | $ | 1,608 | 100 | % | $ | 1,437 | 100 | % | $ | 1,414 | 100 | % | $ | 171 | $ | 194 | ||||||||||||||||||||||||||||||||||
| INTEREST RECEIVABLE | 19 | 21 | 14 | (2) | 5 | |||||||||||||||||||||||||||||||||||||||||||||
| TOTAL TREASURY INVESTMENT PORTFOLIO, NET OF INTEREST RECEIVABLE | $ | 1,627 | 100 | % | $ | 1,458 | 100 | % | $ | 1,428 | 100 | % | $ | 169 | $ | 199 | ||||||||||||||||||||||||||||||||||
(1)Risk in highly rated countries outside the Region. As of September 30, 2026, “Other Non-Latam” was comprised of Canada ($51 million), European countries ($239 million) and Asian-Pacific countries ($348 million).
(2)Includes financial instruments related to Treasury investment management activities such as the principal balance of securities at FVOCI and at amortized cost, gross of interest receivable and the allowance for losses.
27 | ||
28 | ||