SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 6-K
REPORT OF FOREIGN PRIVATE ISSUER PURSUANT
TO RULE 13A-16
OR 15D-16 OF THE SECURITIES EXCHANGE ACT OF 1934
For the month of October, 2026
(Commission File No. 1-14862 )
BRASKEM S.A.
(Exact Name as Specified in its Charter)
N/A
(Translation of registrant's name into English)
Rua Eteno, 1561, Polo Petroquimico de Camacari
Camacari, Bahia - CEP 42810-000 Brazil
(Address of principal executive offices)
Indicate by check mark whether the registrant
files or will file annual reports under cover Form 20-F or Form 40-F.
Form 20-F ___X___ Form 40-F ______
Indicate by check mark if the registrant is
submitting the Form 6-K
in paper as permitted by Regulation S-T Rule 101(b)(1). _____
Indicate by check mark if the registrant is
submitting the Form 6-K
in paper as permitted by Regulation S-T Rule 101(b)(7). _____
Indicate by check mark whether the
registrant by furnishing the information contained in this Form is also thereby furnishing the information to the Commission pursuant
to Rule 12g3-2(b) under the Securities Exchange Act of 1934.
Yes ______ No ___X___
If "Yes" is marked, indicate below the file number assigned to the registrant in connection with Rule 12g3-2(b): 82- _____.
 |
BRASKEM S.A.
Corporate Taxpayer ID (C.N.P.J.): 42.150.391/0001-70
State Registration (NIRE): 29.300.006.939
Publicly Held Company
MATERIAL FACT
PRODUCTION & SALES REPORT
THIRD QUARTER 2026
São Paulo, October 29, 2026 – Braskem S.A. (“Braskem” or “Company”) reports to its shareholders and the market its Production & Sales Report for the third quarter of 2026. The data and information herein are preliminary and were not reviewed by the Company's independent auditor.
For more information, contact Braskem’s Investor Relations Department by calling +55 11 3576-9531 or emailing braskem-ri@braskem.com.br.
TABLE OF CONTENTS
| 1. OPERATIONAL OVERVIEW 3Q26 | 2 |
| 2. PERFORMANCE BY SEGMENT | 3 |
| 2.1 BRAZIL/SOUTH AMERICA | 3 |
| 2.2 UNITED STATES AND EUROPE | 6 |
| 2.3 MEXICO | 7 |
| 3. PETROCHEMICAL SPREADS | 9 |
| |
| 1. | OPERATIONAL OVERVIEW 3Q26 |
| Key Operational Indicators | 3Q26 | 2Q26 | 3Q25 | Chg. | Chg. | 9M26 | 9M25 | Chg. | |
| Unit | (A) | (B) | (C) | (A)/(B) | (A)/(C) | (D) | (E) | (D)/(E) | |
| Brazil | |||||||||
| Utilization Rate of Ethylene | % | 69% | 70% | 65% | -1 p.p. | 4 p.p. | 69% | 71% | -2 p.p. |
| Sales Volume of Main Chemicals | kt | 574 | 598 | 700 | -4% | -18% | 1,794 | 1,964 | -9% |
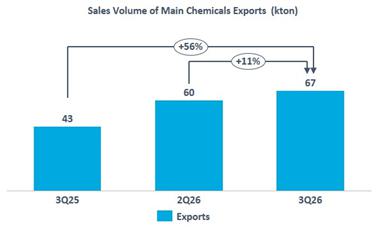
| Sales Volume of Main Chemicals Exports | kt | 67 | 60 | 43 | 11% | 56% | 166 | 146 | 14% |
| Sales Volume of Resins | kt | 854 | 763 | 787 | 12% | 9% | 2,399 | 2,423 | -1% |
| Sales Volume of Resins Exports | kt | 240 | 175 | 229 | 37% | 5% | 597 | 646 | -8% |
| Utilization Rate of Green Ethylene | % | 47% | 66% | 40% | -19 p.p. | 7 p.p. | 59% | 66% | -7 p.p. |
| Sales of Green PE | kt | 31 | 39 | 44 | -19% | -29% | 96 | 130 | -26% |
| Resins Spreads | US$/t | 372 | 653 | 355 | -43% | 5% | 461 | 375 | 23% |
| Spreads on Main Chemicals | US$/t | 539 | 620 | 360 | -13% | 50% | 491 | 362 | 35% |
| United States and Europe | |||||||||
| Utilization Rate | % | 74% | 76% | 79% | -2 p.p. | -5 p.p. | 76% | 75% | 1 p.p. |
| Sales Volume | kt | 489 | 499 | 495 | -2% | -1% | 1,485 | 1,497 | -1% |
| PP US and Europe Average Spread | US$/t | 402 | 469 | 361 | -14% | 11% | 413 | 371 | 11% |
| Mexico | |||||||||
| Utilization Rate | % | 62% | 43% | 47% | 19 p.p. | 15 p.p. | 53% | 56% | -3 p.p. |
| Sales Volume | kt | 159 | 125 | 146 | 28% | 9% | 424 | 487 | -13% |
| PE Mexico Spread | US$/t | 921 | 1,425 | 724 | -35% | 27% | 1,057 | 752 | 41% |
During the third quarter of 2026, expectations of a resolution to the conflict in the Middle East, combined with a more moderate global demand environment, contributed to a reduction in the prices of the main petrochemical feedstocks. These combined movements led to the normalization of petrochemical spreads in the international market, which returned to levels closer to those observed before the onset of geopolitical tensions, following the increase recorded in the previous quarter.
In the Brazil/South America segment, the average cracker utilization rate remained in line compared to 2Q26. Resins sales volume in the Brazilian market was higher compared to 2Q26, due to the execution of the commercial strategy focused on increasing market share in priority segments in Brazil.
In the United States and Europe segment, the average PP plant utilization rate was lower compared to 2Q26, mainly due to the lower production volume in Europe resulting from the climatic event that impacted the logistics chain, restricting propylene availability in the region. The sales volume of PP was lower in the period, explained by inventory management across the downstream plastics value chain in Europe and, in the United States, by uncertainties regarding the effects of the conflict in the Middle East.
In the Mexico segment, the quarter was marked by progress in Braskem Idesa’s financial restructuring, with the announcement of a comprehensive and consensual agreement with its main stakeholders. In this context, the average PE plant utilization rate was higher compared to 2Q26, due to the acquisition of a higher volume of imported ethane and the higher volume of ethane supplied by PEMEX. PE sales volume was higher during the period, due to higher product availability for sale.
| 2 |
| |
| 2. | PERFORMANCE BY SEGMENT |
| 2.1 | BRAZIL/SOUTH AMERICA |
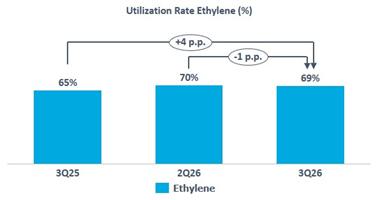
Average utilization rate of petrochemical crackers: in line (-1 p.p.) compared to 2Q26, mainly explained by lower production at the Bahia and São Paulo crackers due to the inventory level optimization process. This effect was partially offset by higher production at the Rio Grande do Sul cracker, explained by (i) higher feedstock availability; and (ii) the normalization of operations following scheduled maintenance carried out in 2Q26.
Compared to 3Q25, the average cracker utilization rate was higher (+4 p.p.), mainly explained by the normalization of operations at the Rio de Janeiro cracker following a scheduled maintenance shutdown carried out in 3Q25.
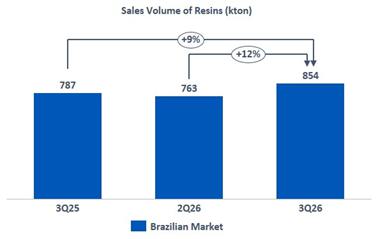
Resin sales volume: in the Brazilian market, the increase compared to 2Q26 (+12%) and 3Q25 (+9%) is mainly explained by the execution of the commercial strategy focused on expanding market share in priority segments in Brazil.
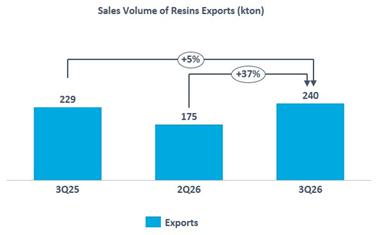
Exports were higher compared to 2Q26 (+37%) and 3Q25 (+5%), mainly explained by the increase in product availability for export.
| 3 |
| |
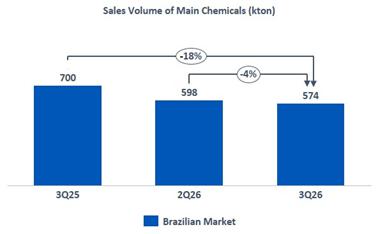
Main chemicals sales volume1: in the Brazilian market, was lower (-4%) compared to 2Q26, mainly due to the lower sales volume of (i) gasoline, explained by the prioritization of higher value-added sales; and (ii) paraxylene, explained by lower product availability for sale. These effects were partially offset by the higher sales volume of (i) cumene, following a customer's scheduled maintenance shutdown in 2Q26; and (ii) ethylene, explained by higher demand in the Brazilian market.
Compared to 3Q25, Main Chemicals sales volume in the Brazilian market was lower (-18%) due to the lower sales volume of (i) gasoline, explained by the prioritization of higher value-added sales, as previously mentioned; (ii) benzene, explained by the permanent shutdown of a customer asset; and (iii) paraxylene, explained by lower product availability for sale, as previously mentioned.
Main Chemicals export volume was higher compared to 2Q26 (+11%) and 3Q25 (+56%), mainly due to the higher export volume of benzene, gasoline and paraxylene, explained by higher product availability for sale, resulting from lower demand in the Brazilian market and one-off commercial opportunities.
1 Main chemicals refer to: ethylene, propylene, butadiene, cumene, gasoline, benzene, toluene and paraxylene based on their relevance to the segment’s net revenue.
| 4 |
| |
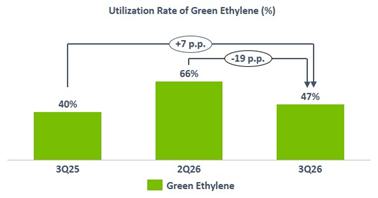
Average utilization rate of green ethylene: was lower (-19 p.p.) compared to 2Q26, mainly due to a scheduled shutdown at the Rio Grande do Sul cracker, completed in October 2026, with a duration of 33 days.
Compared to 3Q25, the increase (+7 p.p.) is mainly explained by the normalization of operations following the optimization of inventory levels carried out in 3Q25.
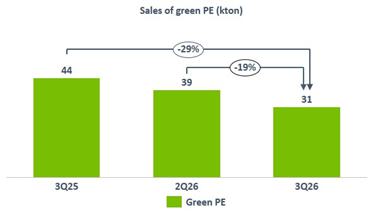
Green PE (I'm greenTM bio-based) sales volume: was lower (-19%) compared to 2Q26, mainly due to (i) lower product availability for sale; and (ii) lower demand.
Compared to 3Q25, the sales volume of Green PE was lower (-29%), mainly due to (i) continued inventory management across the downstream plastics value chain; and (ii) volatile macroeconomic conditions impacting demand in the period.
| 5 |
| |
| 2.2 | UNITED STATES AND EUROPE |
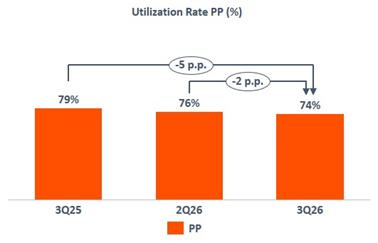
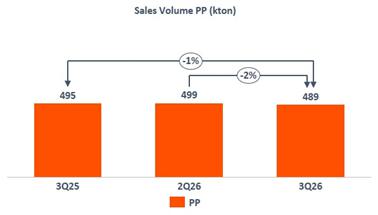
Average utilization rate of PP plants: lower (-2 p.p.) compared to 2Q26, mainly due to the lower production volume in Europe, explained by the weather event that impacted the logistics chain, restricting the availability of propylene in the region.
Compared to 3Q25, the average utilization rate was lower (-5 p.p.), mainly due to the lower production volume (i) in Europe, as previously mentioned; and (ii) in the United States, following the replenishment of inventory levels that occurred in 3Q25.
PP sales volume: was lower (-2%) compared to 2Q26, mainly explained by the lower sales volume (i) in Europe, due to lower product availability for sale; and (ii) in the United States, due to customer purchase anticipations made in the previous quarter given the uncertainties related to the conflict in the Middle East.
Compared to 3Q25, PP sales volume remained in line.
| 6 |
| |
| 2.3 | MEXICO |
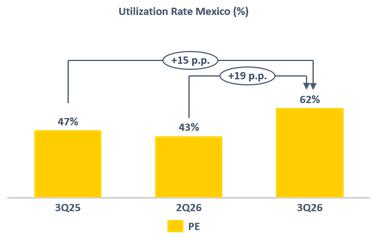
Average utilization rate of PE plants: higher compared to 2Q26 (+19 p.p.) and 3Q25 (+15 p.p.), mainly due to (i) the higher volume of imported ethane acquired; and (ii) the higher volume of ethane supplied by PEMEX.
The average volume of imported ethane through TQPM was 27.3 thousand barrels per day in 3Q26, higher when compared to the volume of 14.7 thousand barrels per day in 2Q26. The average ethane supply by PEMEX in the quarter was 13.2 thousand barrels per day, higher when compared to the average volume of 11.8 thousand barrels per day in 2Q26, due to the higher volume of ethane available during the period.
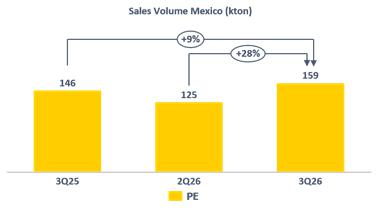
PE sales volume: higher compared to 2Q26 (+28%) and 3Q25 (+9%), mainly due to higher product availability for sale, explained by the higher PE plant utilization rate during the period, as previously mentioned.
| 7 |
| |
| 8 |
| |
| 3. | PETROCHEMICAL SPREADS |
| International References2 | Unit | 3Q26 | 2Q26 | 3Q25 | Chg. | Chg. | 9M26 | 9M25 | Chg. |
| (A) | (B) | (C) | (A)/(B) | (A)/(C) | (D) | (E) | (D)/(E) | ||
| Brent | US$/bbl | 97 | 104 | 69 | -7% | 41% | 94 | 71 | 33% |
| Natural Gas | US$/MMBtu | 2.87 | 2.95 | 3.03 | -3% | -5% | 3.54 | 3.46 | 2% |
| Brazil | |||||||||
| Prices | |||||||||
| Naphtha | US$/t | 763 | 808 | 558 | -6% | 37% | 736 | 583 | 26% |
| Ethane | US$/t | 180 | 158 | 172 | 14% | 5% | 171 | 184 | -7% |
| Propane | US$/t | 384 | 407 | 358 | -6% | 7% | 379 | 411 | -8% |
| EDC US | US$/t | 213 | 229 | 75 | -7% | 183% | 199 | 112 | 78% |
| Resins3 | US$/t | 1,073 | 1,397 | 870 | -23% | 23% | 1,135 | 908 | 25% |
| PE US (Brazil Mix)4 | US$/t | 1,097 | 1,581 | 915 | -31% | 20% | 1,227 | 960 | 28% |
| PP Asia | US$/t | 1,148 | 1,265 | 868 | -9% | 32% | 1,114 | 907 | 23% |
| PVC Asia | US$/t | 785 | 963 | 690 | -19% | 14% | 802 | 697 | 15% |
| Main Chemicals5 | US$/t | 1,302 | 1,428 | 918 | -9% | 42% | 1,227 | 945 | 30% |
| Resins Spread6 | US$/t | 372 | 653 | 355 | -43% | 5% | 461 | 375 | 23% |
| PE US Spread (Brazil Mix)7 | US$/t | 419 | 866 | 408 | -52% | 3% | 572 | 427 | 34% |
| PP Asia Spread | US$/t | 385 | 457 | 309 | -16% | 24% | 378 | 324 | 17% |
| PVC Asia Spread8 | US$/t | 219 | 333 | 323 | -34% | -32% | 261 | 301 | -14% |
| Main Chemicals Spread9 | US$/t | 539 | 620 | 360 | -13% | 50% | 491 | 362 | 35% |
| US & Europe | |||||||||
| PP US | US$/t | 1,540 | 1,731 | 1,238 | -11% | 24% | 1,520 | 1,320 | 15% |
| PP Europe | US$/t | 1,627 | 1,930 | 1,334 | -16% | 22% | 1,625 | 1,365 | 19% |
| Average PP Price - US and Europe10 | US$/t | 1,564 | 1,786 | 1,265 | -12% | 24% | 1,549 | 1,333 | 16% |
| Propylene Polymer Grade US | US$/t | 988 | 1,135 | 797 | -13% | 24% | 991 | 879 | 13% |
| Propylene Polymer Grade Europe | US$/t | 1,609 | 1,785 | 1,178 | -10% | 37% | 1,510 | 1,175 | 29% |
| Average Propylene Price - US and Europe11 | US$/t | 1,162 | 1,317 | 904 | -12% | 29% | 1,136 | 962 | 18% |
| PP US Spread | US$/t | 551 | 595 | 441 | -7% | 25% | 529 | 441 | 20% |
| PP Europe Spread | US$/t | 18 | 145 | 155 | -88% | -88% | 114 | 190 | -40% |
| Average Spread - US and Europe PP | US$/t | 402 | 469 | 361 | -14% | 11% | 413 | 371 | 11% |
| Mexico | |||||||||
| PE US (Mexico Mix)12 | US$/t | 1,101 | 1,583 | 895 | -30% | 23% | 1,228 | 936 | 31% |
| Ethane US | US$/t | 180 | 158 | 172 | 14% | 5% | 171 | 184 | -7% |
| US PE Spread (Mexico Mix) | US$/t | 921 | 1,425 | 724 | -35% | 27% | 1,057 | 752 | 41% |
2 Source: External consulting.
3 PE US (Brazil Mix) (54%), PP Asia (33%) and PVC Asia (13%)
4 HDPE US (40%), LDPE US (30%) and LLDPE US (30%)
5 Ethylene (20%), butadiene (10%), propylene (10%), cumene (5%), benzene (20%), paraxylene (5%), gasoline (25%), and toluene (5%), according to Braskem's sales volume mix.
6 PE US Spread (Brazil Mix) (54%), PP Asia Spread (33%) and PVC Asia Spread (13%)
7 PE US (Brazil Mix) - naphtha (82%) + (PE US (Brazil Mix) - 0.5 * US ethane - 0.5 * US propane) (18%).
8 PVC Asia - (0.832 * EDC US + 0.23 * ethylene Europe)
9 Main Chemicals - Naphtha
10 PP US (72%) and PP Europe (28%)
11 Propylene US (72%) and Propylene Europe (28%)
12 HDPE US (71%) and LDPE US (29%).
| 9 |
| |
BRAZIL/SOUTH AMERICA
| • | PE Spread13: lower compared to 2Q26 (-52%). |
| ○ | PE price in the United States was lower (-31%) compared to 2Q26, mainly impacted by oversupply and high inventory levels in North America. |
| ○ | Naphtha ARA price was lower (-6%) compared to 2Q26, mainly explained by the lower oil price (-7%), due to market expectations regarding developments in the Middle East conflict, which reduced the geopolitical risk premium. |
| ○ | Compared to 3Q25, the spread was higher (+3%), mainly due to the higher PE price in the United States (+20%), driven by higher production costs for Asian producers, which impacted PE prices in the international market. |
| · | PP Spread14: lower compared to 2Q26 (-16%). |
| o | PP price in Asia was lower (-9%) compared to 2Q26, mainly explained by (i) higher PP supply in China; and (ii) moderate global demand. |
| o | Naphtha ARA price was lower (-6%) compared to 2Q26, as previously mentioned. |
| o | Compared to 3Q25, the spread was higher (+24%), due to the higher PP price (+32%), mainly explained by (i) higher production costs for Asian producers, which impacted PP prices in the international market; and (ii) the effects of the Middle East conflict on the global industry. |
| · | PVC Spread15: lower compared to 2Q26 (-34%). |
| ○ | PVC price was lower compared to 2Q26 (-19%), mainly explained by (i) lower demand in Asia, especially in construction-related sectors; and (ii) the effects of the Middle East conflict. |
| ○ | EDC price, a feedstock for PVC production, was lower (-7%) compared to the previous quarter, mainly explained by (i) the normalization of ethylene production, which increased supply and lowered prices; and (ii) lower PVC demand. |
| ○ | Compared to 3Q25, the PVC spread was lower (-32%), due to the higher EDC price (+183%), mainly explained by (i) strong international demand for EDC from the United States; and (ii) supply constraints resulting from the conflict in the Middle East. |
| · | Main Chemicals Spread16: lower compared to 2Q26 (-13%). |
| ○ | Main Chemicals prices were lower (-9%) compared to the previous quarter, mainly due to lower prices of (i) butadiene (-27%); (ii) propylene (-13%); and (iii) ethylene (-12%), mainly explained by lower oil prices in the international market and lower demand from the petrochemical industry. |
| ○ | Naphtha ARA price was lower (-6%), as previously mentioned. |
| ○ | Compared to 3Q25, the Main Chemicals spread was higher (+50%), mainly explained by higher international prices of (i) toluene (+61%); (ii) gasoline (+57%); (iii) benzene (+55%); |
| ○ | and (iv) butadiene (+35%), mainly due to supply constraints resulting from the Middle East conflict. |
13 (US PE Price – ARA Naphtha Price) *82%+(US PE Price – 50% US Ethane Price – 50% US Propane Price) *18%.
14 Asia PP price – ARA naphtha price.
15 PVC Asia - (0.832 US EDC+0.23 EU Ethylene).
16 Average price of main chemicals (Ethylene (20%), Butadiene (10%), Propylene (10%), Cumene (5%), Benzene (20%), Paraxylene (5%), Gasoline (25%) and Toluene (5%), based on Braskem's sales volume mix) – naphtha ARA price.
| 10 |
| |
UNITED STATES AND EUROPE
| • | PP Spread US17: lower compared to 2Q26 (-7%). |
| ○ | PP price was lower (-11%) compared to 2Q26, due to the lower propylene price in the US (-13%), mainly explained by (i) increased supply following the restart of plants in the United States after scheduled maintenance shutdowns; and (ii) lower demand in the region. |
| ○ | Compared to 3Q25, the spread was higher (+25%), mainly due to the higher US PP price (+24%), explained by higher international demand for North American product amid supply constraints in other regions resulting from the Middle East conflict. |
| • | PP Spread Europe18: lower compared to 2Q26 (-88%). |
| ○ | PP price in Europe was lower (-16%), mainly due to lower demand from the construction, automotive and packaging sectors, combined with reduced industrial activity during the summer holiday period in Europe. |
| ○ | Propylene price was lower (-10%), mainly due to lower international prices of oil (-7%) and naphtha (-6%), as previously explained. |
| ○ | Compared to 3Q25, the spread was lower (-88%), impacted by the higher propylene price in Europe (+37%), mainly explained by (i) lower product availability due to logistics constraints in Europe; and (ii) higher petrochemical feedstock costs. |
MEXICO
| · | PE Spread North America19: lower compared to 2Q26 (-35%). |
| ○ | The PE price in the US was lower (-30%) compared to the previous quarter, as previously explained. The ethane price was higher (+14%) compared to 2Q26, mainly explained by higher operating rates of PE producers in the US. |
| ○ | Compared to 3Q25, the spread was higher (+27%), mainly impacted by the higher PE price in the US (+23%), as previously explained. |
17 US PP Price – US propylene price
18 Price of PP Europe – Europe propylene price
19 PE Price US – US ethane price
| 11 |
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
Date: October 29, 2026
| BRASKEM S.A. | |||
| By: | /s/ Carlos Augusto Machado Pereira de Almeida Brandão | ||
| Name: | Carlos Augusto Machado Pereira de Almeida Brandão | ||
| Title: | Chief Financial Officer | ||
FORWARD-LOOKING STATEMENTS
This Material Fact may contain forward-looking statements. These statements are not historical facts but rather are based on the current view and estimates of the Company's management regarding future economic and other circumstances, industry conditions, financial performance, and results, including any potential or projected impact regarding the geological event in Alagoas and related legal procedures on the Company's business, financial condition, and operating results. The words “project,” “believe,” “estimate,” “expect,” “plan,” “objective,” and other similar expressions, when referring to the Company, are used to identify forward-looking statements. Statements related to the possible outcome of legal and administrative proceedings, implementation of operational and financing strategies and investment plans, guidance on future operations, the objective of expanding its efforts to achieve the sustainable macro-objectives disclosed by the Company, as well as factors or trends that affect the financial condition, liquidity or operating results of the Company are examples of forward-looking statements. Such statements reflect the current views of the Company's management and are subject to various risks and uncertainties, many of which are beyond the Company’s control. There is no guarantee that the events, trends, or expected results will actually occur. The statements are based on various assumptions and factors, including, but not limited to, general economic and market conditions, industry conditions and operating factors, availability, development, and financial access to new technologies. Any change in these assumptions or factors, including the projected impact from the geological event in Alagoas and related legal procedures, and the unprecedented impact on businesses, employees, service providers, shareholders, investors, and other stakeholders of the Company could cause effective results to differ significantly from current expectations. For a comprehensive description of the risks and other factors that could impact any forward-looking statements in this document, especially the factors discussed in the sections, see the reports filed with the Brazilian Securities and Exchange Commission (CVM). This Material Fact does not constitute any offer of securities for sale in Brazil. No securities may be offered or sold in Brazil without being registered or exempted from registration, and any public offer of securities carried out in Brazil must be made through a prospectus, which would be made available by Braskem and contain detailed information on Braskem and its management, as well as its financial statements.