SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 6-K
Report of Foreign Private Issuer
Pursuant to Rule 13a-16 or 15d-16 of the
Securities Exchange Act of 1934
For the month of October, 2026
Commission File Number 1565025
AMBEV S.A.
(Exact name of registrant as specified in its charter)
AMBEV S.A.
(Translation of Registrant's name into English)
Rua Dr. Renato Paes de Barros, 1017 - 3rd
Floor
04530-000 São Paulo, SP
Federative Republic of Brazil
(Address of principal executive office)
Indicate by check mark whether the registrant files or will file annual reports under cover Form 20-F or Form 40-F.
Form 20-F ___X___ Form 40-F _______
Indicate by check mark whether the registrant by furnishing the information contained in this Form is also thereby furnishing the information to the Commission pursuant to Rule 12g3-2(b) under the Securities Exchange Act of 1934.
Yes _______ No ___X____
Contents
AMBEV S.A. |
INTERIM CONSOLIDATED BALANCE SHEET
All amounts in thousands of Brazilian Reais
| Assets | Note | 09/30/2026 | 12/31/2025 |
| Cash and cash equivalents | 5.1 | 19,188,249 | 18,638,228 |
| Investment securities | 5.2 | 2,725,865 | 1,681,692 |
| Trade receivables | 6,253,951 | 6,351,608 | |
| Derivative financial instruments | 20 | 689,633 | 769,212 |
| Inventories | 6 | 9,982,779 | 10,520,090 |
| Recoverable taxes | 7 | 1,680,689 | 3,623,379 |
| Other assets | 2,384,168 | 1,911,942 | |
| 42,905,334 | 43,496,151 | ||
| Assets held for sale | 1.3.4 | 247,666 | 379,445 |
| Current assets | 43,153,000 | 43,875,596 | |
| Investment securities | 5.2 | 90,930 | 123,256 |
| Derivative financial instruments | 20 | 1,910 | 8,904 |
| Recoverable taxes | 7 | 10,987,380 | 10,149,140 |
| Deferred tax assets | 8.1 | 8,542,226 | 8,404,412 |
| Other assets | 1,811,563 | 1,784,707 | |
| Employee benefits | 23,896 | 29,936 | |
| Long term assets | 21,457,905 | 20,500,355 | |
| Investments in associates and joint ventures | 1,166,876 | 485,792 | |
| Property, plant and equipment | 9 | 25,299,791 | 27,644,317 |
| Intangible assets | 10,426,615 | 11,042,703 | |
| Goodwill | 40,070,512 | 41,538,388 | |
| Non-current assets | 98,421,699 | 101,211,555 | |
| Total assets | 141,574,699 | 145,087,151 |
The accompanying notes are an integral part of these interim consolidated financial statements.
AMBEV S.A. |
INTERIM CONSOLIDATED BALANCE SHEET (CONTINUED)
All amounts in thousands of Brazilian Reais
| Equity and liabilities | Note | 09/30/2026 | 12/31/2025 |
| Trade payables | 10 | 21,176,116 | 23,742,835 |
| Derivative financial instruments | 20 | 894,255 | 925,127 |
| Interest-bearing loans and borrowing | 11 | 997,097 | 1,167,325 |
| Payroll and social security payables | 2,504,973 | 2,200,729 | |
| Dividends and interest on capital payables | 4,119,652 | 4,927,786 | |
| Income tax and social contribution payable | 1,076,218 | 1,437,314 | |
| Taxes and contributions payable | 4,457,359 | 6,003,145 | |
| Other liabilities, including obligations related to the acquisition of non-controlling interest | 4,836,592 | 4,623,681 | |
| Provisions | 12.1 | 662,412 | 571,365 |
| Current liabilities | 40,724,674 | 45,599,307 | |
| Trade payables | 10 | 229,992 | 312,959 |
| Derivative financial instruments | 20 | 1,056 | 274 |
| Interest-bearing loans and borrowing | 11 | 1,717,662 | 2,219,599 |
| Deferred tax liabilities | 8.1 | 3,793,425 | 3,912,270 |
| Income tax and social contribution payable | 498,468 | 713,614 | |
| Taxes and contributions payable | 695,319 | 659,665 | |
| Other liabilities | 3,739 | 4,307 | |
| Provisions | 12.1 | 722,981 | 877,690 |
| Employee benefits | 1,745,436 | 2,012,685 | |
| Non-current liabilities | 9,408,078 | 10,713,063 | |
| Total liabilities | 50,132,752 | 56,312,370 | |
| Equity | 13 | ||
| Issued capital | 58,308,102 | 58,275,079 | |
| Reserves | 104,939,226 | 108,003,463 | |
| Carrying value adjustments | (83,543,857) | (78,364,503) | |
| Retained earnings/(losses) | 11,192,252 | - | |
| Equity attributable to Ambev’s shareholders | 90,895,723 | 87,914,039 | |
| Non-controlling interest | 546,224 | 860,742 | |
| Total equity | 91,441,947 | 88,774,781 | |
| Total equity and liabilities | 141,574,699 | 145,087,151 |
The accompanying notes are an integral part of these interim consolidated financial statements.
AMBEV S.A. |
INTERIM CONSOLIDATED INCOME STATEMENT
For the nine and three-month periods ended September 30
All amounts in thousands of Brazilian Reais unless otherwise stated
| Nine-month period ended: | Three-month period ended: | |||||
| Note | 2026 | 2025 | 2026 | 2025 | ||
| Net sales | 15 | 64,207,969 | 63,434,834 | 21,594,570 | 20,847,262 | |
| Cost of sales | (31,170,344) | (31,111,860) | (10,588,297) | (10,120,005) | ||
| Gross profit | 33,037,625 | 32,322,974 | 11,006,273 | 10,727,257 | ||
| Distribution expenses | (8,064,311) | (8,016,710) | (2,594,372) | (2,559,668) | ||
| Commercial expenses | (6,405,190) | (6,162,739) | (2,067,645) | (1,919,906) | ||
| Administrative expenses | (4,238,455) | (4,270,205) | (1,446,408) | (1,355,011) | ||
| Other operating income/(expenses) | 16 | 2,048,384 | 1,768,182 | 683,196 | 567,129 | |
| Exceptional items | 17 | (37,346) | 772,901 | (42,983) | 845,476 | |
| Income from operations | 16,340,707 | 16,414,403 | 5,538,061 | 6,305,277 | ||
| Finance income (i) | 18 | 1,822,919 | 1,451,356 | 627,023 | 389,716 | |
| Finance expenses (i) | 18 | (3,184,600) | (3,142,210) | (992,688) | (1,143,102) | |
| Other net financial results (i) | 18 | (493,358) | (1,225,506) | 53,276 | (332,607) | |
| Net financial results | (1,855,039) | (2,916,360) | (312,389) | (1,085,993) | ||
| Share of results of associates and joint ventures | 33,439 | (8,130) | 22,768 | (5,392) | ||
| Income before income tax | 14,519,107 | 13,489,913 | 5,248,440 | 5,213,892 | ||
| Income tax expenses | 8.2 | (2,792,549) | (2,030,978) | (882,125) | (350,172) | |
| Net income | 11,726,558 | 11,458,935 | 4,366,315 | 4,863,720 | ||
| Attributable to: | ||||||
| Equity holders of Ambev | 11,400,571 | 11,156,796 | 4,245,393 | 4,745,128 | ||
| Non-controlling interest | 325,987 | 302,139 | 120,922 | 118,592 | ||
| Basic earnings per share – common – R$ | 0.7349 | 0.7141 | 0.2754 | 0.3041 | ||
| Diluted earnings per share – common – R$ | 0.7321 | 0.7109 | 0.2743 | 0.3028 | ||
(i) As from the fourth quarter of 2025, the other financial income and other financial expense line items, which had previously been presented separately, were combined into the line item “Other net financial results”. The same treatment has been applied on a comparative basis.
The accompanying notes are an integral part of these interim consolidated financial statements.
AMBEV S.A. |
INTERIM CONSOLIDATED STATEMENT OF COMPREHENSIVE INCOME
For the nine and three-month periods ended September 30
All amounts in thousands of Brazilian Reais
| Nine-month period ended: | Three-month period ended: | ||||
| 2026 | 2025 | 2026 | 2025 | ||
| Net income | 11,726,558 | 11,458,935 | 4,366,315 | 4,863,720 | |
| Items that may be subsequently reclassified to profit or loss: | |||||
| Exchange differences on the translation of foreign operations (gains/(losses)) | |||||
| Investment hedges – obligations related to the acquisition of a non-controlling interest | 5,151 | 122,029 | 1,262 | 47,607 | |
| Gains/losses on translation of other foreign operations | (5,374,507) | (10,713,752) | (682,116) | (3,482,641) | |
| Gains/losses on translation of foreign operations | (5,369,356) | (10,591,723) | (680,854) | (3,435,034) | |
| Cash flow hedge – gains/(losses) | |||||
| Recognized in equity (Hedge reserve) | 219,267 | (924,368) | 229,256 | (102,234) | |
| Reclassified from equity (hedge reserve) to profit or loss | (132,696) | (587,838) | (89,782) | (65,683) | |
| Total cash flow hedge | 86,571 | (1,512,206) | 139,474 | (167,917) | |
| Items that will not be reclassified to profit or loss: | |||||
| Re-measurements of post-employment benefits | 890 | (537) | 49 | 499 | |
| Other comprehensive (loss)/income | (5,281,895) | (12,104,466) | (541,331) | (3,602,452) | |
| Total comprehensive (loss)/income | 6,444,663 | (645,531) | 3,824,984 | 1,261,268 | |
| Attributable to: | |||||
| Equity holders of Ambev | 6,245,134 | (798,971) | 3,640,641 | 1,166,716 | |
| Non-controlling interest | 199,529 | 153,440 | 184,343 | 94,552 | |
The consolidated statement of comprehensive income is presented net of income tax. The income tax effects of these items are disclosed in note 8 –Income tax and social contribution.
The accompanying notes are an integral part of these interim consolidated financial statements.
AMBEV S.A. |
INTERIM CONSOLIDATED STATEMENT OF CHANGES IN EQUITY
For the nine-month periods ended September 30
All amounts in thousands of Brazilian Reais
| Attributable to the equity holders of Ambev | ||||||||||
| Issued capital | Capital reserves | Profit reserves | Retained earnings | Carrying value adjustments | Total | Non-controlling interest | Total equity | |||
| At January 1, 2025 | Note | 58,226,036 | 55,336,410 | 53,637,019 | - | (68,557,326) | 98,642,139 | 938,375 | 99,580,514 | |
| Net Income | - | - | - | 11,156,796 | - | 11,156,796 | 302,139 | 11,458,935 | ||
| Comprehensive income: | ||||||||||
| Gains/(losses) on cumulative translation adjustment [CTA] | 13.4 | - | - | - | - | (10,440,425) | (10,440,425) | (151,298) | (10,591,723) | |
| Cash flow hedges | 13.4 | - | - | - | - | (1,514,838) | (1,514,838) | 2,632 | (1,512,206) | |
| Actuarial gains/(losses) | 13.4 | - | - | - | - | (504) | (504) | (33) | (537) | |
| Total comprehensive income | - | - | - | 11,156,796 | (11,955,767) | (798,971) | 153,440 | (645,531) | ||
| Capital increase | 13.1 | 49,660 | - | - | - | - | 49,660 | (28,007) | 21,653 | |
| Effects of the application of IAS 29 (hyperinflation) | - | - | - | 1,725,302 | - | 1,725,302 | (3,065) | 1,722,237 | ||
| Gains/(losses) of controlling interest | 13.4 | - | - | - | - | 1,828 | 1,828 | (1,774) | 54 | |
| Taxes on deemed dividends | - | - | - | - | (62,230) | (62,230) | - | (62,230) | ||
| Dividends | 13.3 | - | - | (496,600) | (5,502,126) | - | (5,998,726) | (313,121) | (6,311,847) | |
| Share buybacks, results from treasury shares and share-based payments | 13.2 | - | (1,569,433) | - | - | - | (1,569,433) | 1,112 | (1,568,321) | |
| Statute-barred /(additional) dividends | - | - | - | 37,866 | - | 37,866 | - | 37,866 | ||
| Others | - | - | - | 11,728 | (11,728) | - | (45,983) | (45,983) | ||
| At September 30, 2025 | 58,275,696 | 53,766,977 | 53,140,419 | 7,429,566 | (80,585,223) | 92,027,435 | 700,977 | 92,728,412 | ||
The accompanying notes are an integral part of these interim consolidated financial statements.
AMBEV S.A. |
INTERIM CONSOLIDATED STATEMENT OF CHANGES IN EQUITY (CONTINUED)
For the nine-month periods ended September 30
All amounts in thousands of Brazilian Reais
| Attributable to the equity holders of Ambev | ||||||||||
| Issued capital | Capital reserves | Profit reserves | Retained earnings | Carrying value adjustments | Total | Non-controlling interest | Total equity | |||
| At January 1, 2026 | Note | 58,275,079 | 53,781,385 | 54,222,078 | - | (78,364,503) | 87,914,039 | 860,742 | 88,774,781 | |
| Net Income | - | - | - | 11,400,571 | - | 11,400,571 | 325,987 | 11,726,558 | ||
| Comprehensive income: | ||||||||||
| Gains/(losses) on cumulative translation adjustment [CTA] | 13.4 | - | - | - | - | (5,244,642) | (5,244,642) | (124,714) | (5,369,356) | |
| Cash flow hedges | 13.4 | - | - | - | - | 88,315 | 88,315 | (1,744) | 86,571 | |
| Actuarial gains/(losses) | 13.4 | - | - | - | - | 890 | 890 | - | 890 | |
| Total comprehensive income | - | - | - | 11,400,571 | (5,155,437) | 6,245,134 | 199,529 | 6,444,663 | ||
| Capital increases/(reduction) in associates and subsidiaries | 13.1 | 33,023 | - | - | - | - | 33,023 | 19,190 | 52,213 | |
| Effects of the application of IAS 29 (hyperinflation) | - | - | - | 1,910,836 | - | 1,910,836 | 2,378 | 1,913,214 | ||
| Gains/(losses) of controlling interest | - | - | - | (333,014) | - | (333,014) | (167,174) | (500,188) | ||
| Taxes on deemed dividends | 13.4 | - | - | - | - | (23,917) | (23,917) | - | (23,917) | |
| Dividends | - | - | - | - | - | - | (370,902) | (370,902) | ||
| Interest on capital | - | - | - | (1,793,837) | - | (1,793,837) | - | (1,793,837) | ||
| Share buybacks, results from treasury shares and share-based payments | 13.2 | - | (3,064,237) | - | - | - | (3,064,237) | 2,461 | (3,061,776) | |
| Statute-barred /(additional) dividends | - | - | - | 7,696 | - | 7,696 | - | 7,696 | ||
| At September 30, 2026 | 58,308,102 | 50,717,148 | 54,222,078 | 11,192,252 | (83,543,857) | 90,895,723 | 546,224 | 91,441,947 | ||
The accompanying notes are an integral part of these interim consolidated financial statements.
AMBEV S.A. |
INTERIM CONSOLIDATED STATEMENT OF CASH FLOWS
For the nine and three-month periods ended September 30
All amounts in thousands of Brazilian Reais
| Nine-month period ended: | Three-month period ended: | |||||
| Note | 2026 | 2025 | 2026 | 2025 | ||
| Net income | 11,726,558 | 11,458,935 | 4,366,315 | 4,863,720 | ||
| Adjustments: | ||||||
| Depreciation, amortization and impairment | 4,824,460 | 5,015,001 | 1,689,843 | 1,599,347 | ||
| Impairment losses on receivables and inventory | 165,078 | 200,657 | 63,457 | 61,573 | ||
| Additions to/(reversals of) provisions and employee benefits | 116,701 | 274,822 | 61,073 | 75,245 | ||
| Net financial results | 18 | 1,855,039 | 2,916,360 | 312,389 | 1,085,993 | |
| Losses/(gains) on sales of property, plant and equipment and intangible assets | 16 | (96,129) | (71,948) | (33,574) | (9,870) | |
| Losses/(gains) on sales of operations in subsidiaries and associates | (81,352) | (884,467) | 4,951 | (884,467) | ||
| Share-based payment expenses | 19.3 | 304,777 | 306,106 | 114,222 | 99,999 | |
| Income tax expenses | 8.2 | 2,792,549 | 2,030,978 | 882,125 | 350,172 | |
| Share of results of associates and joint ventures | (33,439) | 8,130 | (22,768) | 5,392 | ||
| Hedge operations | 20.3 | (247,110) | (794,848) | (130,163) | (97,392) | |
| Cash flow from operating activities before changes in working capital | 21,327,132 | 20,459,726 | 7,307,870 | 7,149,712 | ||
| (Increase)/decrease in trade and other receivables | 411,583 | 784,361 | (250,490) | (136,982) | ||
| (Increase)/decrease in inventories | (200,895) | (35,871) | 262,185 | 519,315 | ||
| Increase/(decrease) in trade and other payables | (3,679,719) | (6,665,001) | 1,051,941 | 311,273 | ||
| Cash generated from operations | 17,858,101 | 14,543,215 | 8,371,506 | 7,843,318 | ||
| Interest paid | (453,105) | (607,173) | (97,168) | (227,871) | ||
| Interest received | 1,248,338 | 986,178 | 455,740 | 336,721 | ||
| Dividends received | 139,263 | 21,992 | 27,117 | 14,980 | ||
| Income tax paid | (3,242,332) | (3,745,856) | (1,079,250) | (1,048,162) | ||
| Cash flow from operating activities | 15,550,265 | 11,198,356 | 7,677,945 | 6,918,986 | ||
| Proceeds from sales of property, plant and equipment and intangible assets | 116,696 | 105,129 | 38,588 | 38,415 | ||
| Acquisitions of property, plant and equipment and intangible assets | (2,479,756) | (2,960,298) | (1,133,024) | (1,043,944) | ||
| Sale/(acquisition) and others related to subsidiaries and associates, net of cash | (1,894,881) | 201,611 | 57,250 | 241,824 | ||
| Investments in short-term debt securities and net proceeds/(acquisitions) of debt securities | (1,092,965) | (268,856) | (1,045,836) | (411,267) | ||
| Net proceeds/(acquisitions) of other assets | (1,086) | 6,713 | (718) | 4,979 | ||
| Cash flow from/(used in) investing activities | (5,351,992) | (2,915,701) | (2,083,740) | (1,169,993) | ||
| Capital increases(reduction)/ in associates and subsidiaries | 35,604 | (3,704) | 64,427 | 27 | ||
| Proceeds from/(buybacks of) treasury shares | (3,333,022) | (1,831,123) | (680,408) | - | ||
| Acquisitions of non-controlling interest | - | (23) | - | - | ||
| Proceeds from borrowing | 40,587 | 9,514 | 14,912 | (41,168) | ||
| Repayments of borrowing | (133,646) | (131,248) | (30,329) | (39,835) | ||
| Cash net of finance costs other than interest | (1,910,216) | (2,457,623) | (735,837) | (807,502) | ||
| Payments of lease liabilities | (827,819) | (847,236) | (272,254) | (252,982) | ||
| Dividends and interest on capital paid | (2,561,657) | (10,773,743) | (1,377,225) | (2,081,745) | ||
| Cash flow from/(used in) financing activities | (8,690,169) | (16,035,186) | (3,016,714) | (3,223,205) | ||
| Net increase/(decrease) in cash and cash equivalents | 1,508,104 | (7,752,531) | 2,577,491 | 2,525,788 | ||
| Cash and cash equivalents at the beginning of the period | 18,638,228 | 28,595,666 | 16,610,779 | 16,404,025 | ||
| Effects of exchange rate fluctuations on cash and cash equivalents | (958,083) | (2,535,436) | (21) | (622,114) | ||
| Cash and cash equivalents at the end of the period | 19,188,249 | 18,307,699 | 19,188,249 | 18,307,699 | ||
The accompanying notes are an integral part of these interim consolidated financial statements.
AMBEV S.A. |
| 1. | CORPORATE INFORMATION |
1.1 Description of business
Ambev S.A. (referred to as the “Company” or “Ambev”) together with its subsidiaries (the “Group” or “Consolidated”), headquartered in São Paulo, São Paulo State, Brazil, has as its corporate purpose the production and sale of beer, draft beer, soft drinks, other non-alcoholic beverages, malt and food in general, either directly or through participation in other companies, as well as the advertising of both its own and of third party products, the sale of promotional and advertising materials, and the direct or indirect exploitation of bars, restaurants, snack bars and similar establishments, among others.
The Group’s main own brands are Brahma®, Skol®, Antarctica®, Original®, Quilmes®, Andes Origen®, Patricia®, Paceña®, Huari®, Pilsen®, Presidente®, Balboa®, Guaraná Antarctica® and Beats® among others. The main licensed brands by Anheuser-Busch InBev N.V. (“AB InBev”) to the Group are Budweiser®, Corona®, Spaten®, Stella Artois®, Beck’s®, Modelo®, Bud Light®, Busch® and Michelob Ultra® among others. In addition, the Company is one of the largest independent bottlers of PepsiCo in the world. The Group produces, sells and distributes in Brazil and in other countries in Latin America, products such as Pepsi®, H2OH! ®, Lipton IceTea® and the sports drink Gatorade® under a license from PepsiCo. The Group also has a licensing agreement with Red Bull® and other companies to distribute of its portifolio some sales channels and specific regions in Brazil and other markets.
The Company’s shares and American Depositary Receipts (“ADRs”) are listed on the Brasil, Bolsa, Balcão S.A. (“B3”) exchange under the ticker “ABEV3” as well as on the New York Stock Exchange (“NYSE”) under the ticker “ABEV”, respectively. The Company’s direct controlling shareholders are Interbrew International GmbH (“ITW International”), and AmBrew S.à.r.l (“Ambrew”), both of which are subsidiaries of AB InBev.
1.2 Key operating countries
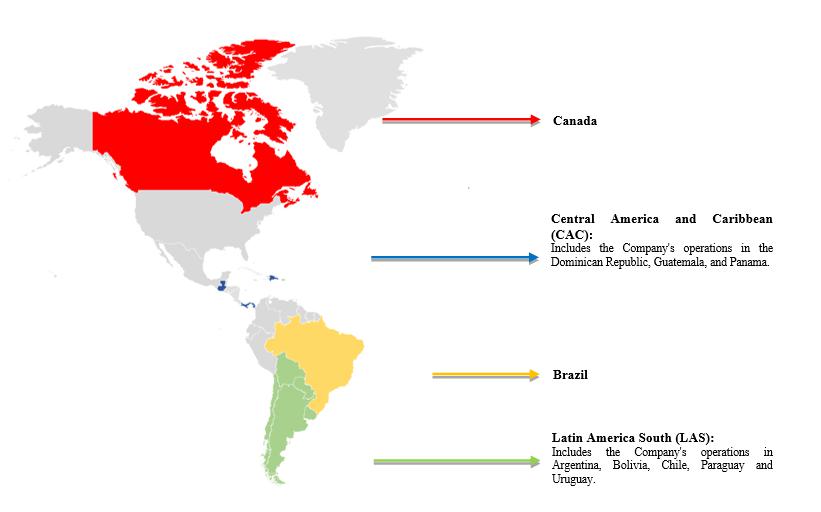
The Company operates its business across four reportable segments based on the geographical zones shown below:
AMBEV S.A. |
1.3 Major corporate events in the three-month period ended September 30, 2026
1.3.1 Resolution on the payment date of the third and final installment of IOC December 2025
At a meeting held on July 29, 2026, the Board of Directors approved the payment date of the third and final installment of the interest on capital, the distribution of which had been approved at the Board of Directors' meeting held on December 9, 2025 ("IOC December 2025"). The payment was made on October 6, 2026, in the gross amount of R$0.1185 per share, corresponding to an estimated net amount of R$0.1007 per share of the Company, after the withholding income tax in accordance with applicable tax legislation, totaling an aggregate gross amount of approximately R$1.9 billion. The record dates considered at the time the distribution was approved remain unchanged.
1.3.2 Distribution of IOC July 2026
At a meeting held on July 29, 2026, the Board of Directors approved the distribution of interest on capital in the gross amount of R$0.0713 per share, corresponding to an estimated net amount of R$0.0588 per share of the Company, after the withholding of income tax, in accordance with applicable legislation, totaling an aggregate gross amount of approximately R$ 1.1 billion ("IOC July 2026"). The July 2026 IOC was offset against the mandatory minimum dividend for the fiscal year and calculated based on the profit for the period and the available balances reflected in the extraordinary balance sheet dated June 30, 2026. The distribution of the July 2026 IOC was taxed in accordance with the legislation in force. Such payment will be made by December 31, 2026, on a date to be determined by the Company's Management, based on the shareholder position as of September 21, 2026, with respect to B3 S.A. – Brasil, Bolsa, Balcão, and September 23, 2026, with respect to the New York Stock Exchange (NYSE), without monetary adjustment. The Company's shares and ADRs were trade ex-IOC beginning on September 22, 2026 (including).
1.3.3 Completion of the Share Buyback Program and Cancellation of Shares
In October 2025, the Board of Directors approved a share buyback program for the Company's own shares, up to the limit of 208,000,000 common shares, with the primary purpose of cancelation, and the shares not canceled may be held in treasury, transferred and/or used to cover any share delivery requirements contemplated in the Company's share-based compensation plans.
In August 2026, the Company completed aforementioned program, having acquired all of the shares contemplated thereunder, for a total acquisition cost of R$ 3,333 million. Additionally, at a meeting held on August 12 and 13, 2026, the Board of Directors, in line with the primary objective of the share buyback program, approved the cancellation of 279,000,000 registered common shares, in book-entry form and with no par value, issued by the Company and held in treasury, with no reduction in the Company’s share capital.
1.3.4 Completion of the third tranche – Sale of subsidiary
On December 26, 2024, the Company's subsidiary, Cervecería Nacional Dominicana, S.A. ("CND"), and Koscab Holdings Limited ("Koscab") entered into a Share Purchase Agreement (“Agreement”) pursuant to which CND agreed to transfer to Koscab its entire equity interest in SLU Beverages LTD. ("SLU"). SLU is the majority shareholder of Banks Holdings Limited, Saint Vincent Brewery Limited, Antigua Brewery Limited, and Dominica Brewery & Beverages Limited, all of which were part of the CAC reportable segment.
The transfer of the entire interest will be made in up to five tranches, with maturities through 2028, in consideration of a minimum estimated amount of US$186 million, equivalent, for reference purposes, to R$964 million. The first two tranches were completed on July 31, 2025, with the transfer of 61.72% of CND's interest in SLU. In August 2026, the third tranche was completed, corresponding to the transfer of an additional 12.76%. As a result, as of September 30, 2026, CND had transferred to Koscab 74.48% of its interest in SLU, for an accumulated amount of US$139 million, equivalent to R$720 million.
AMBEV S.A. |
The loss of control over SLU occurred in July 2025, following the completion of the first two tranches. Consequently, the Group ceased to consolidate SLU as of that date and recognized, for the nine-month period ended September 30, 2025, a gain of R$884 million under exceptional items as further detailed in note 17 – Exceptional items.
This amount included reclassification to the profit or loss of accumulated foreign exchange differences related to SLU, previously recognized in other comprehensive income in equity, in line with IAS 21 – The Effects of Changes in Foreign Exchange Rates.
As of September 30, 2026, the remaining 25.52% interest, to be transferred in subsequent tranches, was recorded in the amount of R$247.7 million under assets held for sale in the balance sheet, in accordance with IFRS 5 – Non-current Assets Held for Sale and Discontinued Operations.
| 2. | BASIS OF PREPARATION AND PRESENTATION OF THE INTERIM CONSOLIDATED FINANCIAL STATEMENTS |
The interim consolidated financial statements at September 30, 2026 have been prepared using the going concern basis of accounting and are being presented in accordance with IAS 34 – Interim Financial Reporting as issued by the International Accounting Standards Board (“IASB®”).
The information does not meet all disclosure requirements for the presentation of full annual consolidated financial statements and are disclosed with relevant information and changes in the period, without the level of detail in certain notes previously disclosed, avoiding repetition. In Management's view the interim consolidated financial statements provide sufficient understanding of the Company's equity position and performance during the interim period. Therefore, it should be read in conjunction with the consolidated financial statements for the year ended December 31, 2025, prepared in accordance with International Financial Reporting Standards (“IFRS®”) issued by the IASB®.
The following notes are not disclosed in the interim consolidated financial statements:
| Name of note in the 2025 annual financial statements | Note number | |
| (a) | Payroll and related benefits | 9 |
| (b) | Additional information on cost of sales and operating expenses by nature | 10 |
| (c) | Earnings per share | 12 |
| (d) | Goodwill | 15 |
| (e) | Impairment of non-financial assets | 16 |
| (f) | Intangibles | 17 |
| (g) | Trade receivables | 20 |
| (h) | Employee benefits | 24 |
In addition, the material accounting policies presented in the respective accompanying notes are not disclosed in these interim consolidated financial statements. The following notes are not in the same level of detail presented in the annual consolidated financial statements, for the year ended December 31, 2025:
AMBEV S.A. |
| Name of note in the 2025 annual financial statements | Note | |
| (a) | Basis of preparation and presentation of the interim consolidated financial statements | 2 |
| (b) | Summary of material accounting policies | 3 |
| (c) | Use of estimates and judgments | 4 |
| (d) | Income tax and social contribution | 13 |
| (f) | Changes in equity | 22 |
| (g) | Interest-bearing loans and borrowing | 23 |
| (h) | Share-based payments | 25 |
| (i) | Provisions, contingent liabilities and contingent asset | 27 |
| (j) | Financial instruments and risks | 28 |
| (k) | Related parties | 30 |
In preparing the interim consolidated financial statements, management uses judgments, estimates and assumptions that affect the application of accounting practices and the reported amounts of assets, liabilities, income and expenses. The relevant estimates and judgments are disclosed in note 4 - Use of estimates and judgments.
The interim consolidated financial statements relating to the period ended September 30, 2026 were approved by the Executive Board of Officers on October 28, 2026.
2.1 Functional and presentation currency
The functional and presentation currency of the Company interim consolidated financial statements is the Brazilian Real, which is the currency of its main economic operating environment. For presentation purposes, the interim consolidated financial statements are presented in thousands of Brazilian Reais (“R$”), unless otherwise indicated, and the balances are rounded to the nearest thousand.
2.1.1 Exchange rates
The most significant exchange rates used for the preparation of the Company’s interim consolidated financial statements are as follow:
| Closing rate | Average rate | ||||||
| Nine-month period ended: | |||||||
| Currency | Name | Country | 09/30/2026 | 12/31/2025 | 09/30/2026 | 09/30/2025 | |
| ARS | Argentinian Peso | Argentina | 0.0034 | 0.0038 | 0.0034 | 0.0048 | |
| BOB | Bolivian Peso | Bolivia | 0.4310 | 0.7906 | 0.6326 | 0.8206 | |
| CAD | Canadian Dollar | Canada | 3.6528 | 4.0187 | 3.7381 | 4.0801 | |
| CLP | Chilean Peso | Chile | 0.0053 | 0.0061 | 0.0057 | 0.0059 | |
| GTQ | Quetzal | Guatemala | 0.6794 | 0.7185 | 0.6768 | 0.7426 | |
| USD | US Dollar | Panamá | 5.1809 | 5.5024 | 5.1782 | 5.7111 | |
| PYG | Guarani | Paraguay | 0.0009 | 0.0008 | 0.0008 | 0.0007 | |
| DOP | Dominican Peso | Dominican Republic | 0.0862 | 0.0869 | 0.0859 | 0.0932 | |
| UYU | Uruguayan Peso | Uruguay | 0.1286 | 0.1409 | 0.1307 | 0.1370 | |
| 3. | SUMMARY OF MATERIAL ACCOUNTING POLICIES |
The accounting practices adopted by the Company are consistent for all the years and periods presented. There were no changes to the accounting policies or calculation methods used for the interim consolidated financial statements at September 30, 2026 compared to those used for the consolidated financial statements for the years ended December 31, 2025.
AMBEV S.A. |
3.1 Recently issued IFRS
The amendments and new standards that became effective in 2026 were either not applicable to, or did not have a material impact on, these interim separate and consolidated financial statements, as summarized below.
| Standard | Effective date | Highlights |
| IFRS 9 and IFRS 7 – Classify and Measurement of Financial Instruments |
January 1, 2026 |
The changes clarify the criteria for the classification and measurement of financial assets and liabilities, with an emphasis on the assessment of the contractual cash flows characteristics and the entity's business model. In addition, they enhance disclosure requirements, aiming to increase transparency regarding significant judgments, financial risks, and the impacts arising from the classification and measurement of financial instruments. |
The following is the main change in accounting standard that, based on Management's assessment, will have an impact on the Company's disclosures in subsequent periods.
Beyond the above, the Company does not anticipate that any other standards or amendments to IFRS® standards or IFRIC® interpretations that have not yet come into force could have a material impact on the Group's financial statements. The Company has not opted for the early adoption of any standards.
3.1.1 IFRS 18 - Presentation and Disclosure in Financial Statements
In April 2024, the IASB issued IFRS 18 Presentation and Disclosures in Financial Statements, which replaces IAS 1 and introduces new requirements aimed at improving the comparability of financial performance reporting and enhancing the transparency of the information provided to users. IFRS 18 is effective for annual reporting periods beginning on or after 1 January 2027, with early adoption permitted. The standard is required to be applied retrospectively.
While IFRS 18 does not affect the recognition or measurement of assets, liabilities, income or expenses, it’s expected to have a significant impact on the presentation of the primary financial statements and the related disclosures. IFRS 18 introduces new requirements to:
| · | present specified categories in the statement of profit or loss, including the introduction of new operating, investing and financing categories, as well as defined subtotals; |
| · | require disclosures of management-defined performance measures (MPMs) in the notes to the financial statements; and |
| · | strengthen the principles of aggregation and disaggregation across primary financial statements and the notes. |
The company anticipates that the adoption of the standard will primarily affect the presentation of the statement of profit or loss and the statement of cash flows, the disclosure of management performance measures, and the structure of the related notes.
The company does not intend to early adopt IFRS 18 and is currently in the process of preparing for the impacts arising from its application to the individual and consolidated financial statements. The Company has assessed that the main change in presentation will be the reclassification of foreign exchange gains and losses and gains and losses on certain hedging instruments from “financial income and expenses,” as presented under IAS 1, to “operating profit,” as required under IFRS 18, when the underlying exposure measured or hedged is related to operating activities.
| 4. | USE OF ESTIMATES AND JUDGMENTS |
The preparation of interim consolidated financial statements in compliance with IFRS requires Management to make use of judgments, estimates and assumptions that affect both the application of accounting practices and the reported amounts of assets and liabilities, income and expenses. The estimates and significant judgment are based on past experience and on other factors that are believed to be reasonable under the circumstances, the results of which form the basis for making judgments regarding the carrying amounts of assets and liabilities that cannot readily be determined based on other sources. The actual results achieved may differ from these estimates.
AMBEV S.A. |
Such estimates and assumptions are reviewed on a regular basis. Changes in accounting estimates may affect the results for the period during which they are realized, or for future periods.
The impairment test is performed annually considering the most accurate estimates calculated by Management. The Company’s Management has not identified any relevant indications of impairment in the nine-month period ended September 30, 2026.
The accounting policy which reflects significant estimates and judgments used in the preparation of these interim consolidated financial statements for the nine-month period ended September 30, 2026 has not changed from those valid on December 31, 2025.
| 5. | CASH AND CASH EQUIVALENTS AND INVESTMENT SECURITIES |
5.1 Cash and cash equivalents
| 09/30/2026 | 12/31/2025 | |
| Cash | 67,741 | 33,360 |
| Current bank accounts | 5,508,190 | 7,824,261 |
| Short-term bank deposits (i) | 13,612,318 | 10,780,607 |
| Net cash and cash equivalents | 19,188,249 | 18,638,228 |
(i) The balance refers mostly to Bank Deposit Certificates (“CDBs”) and highly liquid short-term deposits, which are readily convertible into known amounts of cash and are subject to an insignificant risk of changes in value.
Effective January 2026, the Company ceased to consolidate its subsidiary in Cuba and started to account for as an associate using the equity method, in line with the application of the consolidation criteria under applicable accounting standards. As a result, the cash and cash equivalents balances of this investee are no longer included in the consolidated financial statements from that date. This effect is reflected in the line “Sale/(acquisition) and others related to subsidiaries and associates, net of cash” in the Statements of Cash Flows.
The cash and cash equivalents balance includes the amount of R$821,225 at September 30, 2026 (R$4,070,595 in December 31, 2025), in the consolidated financial statements, which is not freely remittable to the Parent Company. As of September 30, 2026, such restriction arises from the unavailability of foreign currency in Bolivia, although the funds remain available for use in the local operations of the respective subsidiary. As of December 31, 2025, the restricted balance also included amounts related to the operation in Cuba, totaling R$2,017,094.
AMBEV S.A. |
5.2 Investment securities
| 09/30/2026 | 12/31/2025 | |
| Financial assets at fair value through profit or loss | 2,725,865 | 1,667,391 |
| Investments in debt securities (i) | - | 14,301 |
| Current assets | 2,725,865 | 1,681,692 |
| Investments in debt securities | 90,930 | 123,256 |
| Non-current assets | 90,930 | 123,256 |
| Total | 2,816,795 | 1,804,948 |
(i) The balance refers substantially to financial investments linked to tax incentives that are not immediately convertible into a known amount of cash.
| 6. | INVENTORIES |
| 09/30/2026 | 12/31/2025 | |
| Finished goods | 3,719,584 | 3,218,469 |
| Work in progress | 708,487 | 619,904 |
| Raw materials and consumables | 4,581,644 | 5,297,699 |
| Spare parts and others | 784,287 | 865,375 |
| Inventory in transit and prepayments | 293,055 | 629,705 |
| Impairment losses | (104,278) | (111,062) |
| 9,982,779 | 10,520,090 |
The changes in impairment losses on inventory are as follow:
| 09/30/2026 | 12/31/2025 | |
| Balance at the end of the previous year | (111,062) | (141,046) |
| Effects of cumulative translation adjustments (CTA) | 8,392 | 6,911 |
| Restructuring of subsidiaries (i) | 6,432 | 4,007 |
| Provisions | (123,967) | (195,476) |
| Write-offs/reversal of provisions | 115,927 | 214,542 |
| Balance at the end of the period | (104,278) | (111,062) |
(i) Effect related to the deconsolidation of balance sheet amounts, including the sale of a subsidiary.
AMBEV S.A. |
| 7. | RECOVERABLE TAXES |
| 09/30/2026 | 12/31/2025 | |
| Exclusion of ICMS from PIS/COFINS (i) | 186,769 | 436,593 |
| PIS/COFINS | 149,408 | 143,553 |
| ICMS | 463,525 | 407,345 |
| IPI | 106,951 | 120,665 |
| Income tax and social contributions | 718,672 | 2,480,759 |
| Other | 55,364 | 34,464 |
| Current | 1,680,689 | 3,623,379 |
| Exclusion of ICMS from PIS/COFINS (i) | 7,408,012 | 7,118,090 |
| PIS/COFINS | 7,766 | 28,315 |
| ICMS | 281,085 | 320,380 |
| Income tax and social contributions | 3,117,930 | 2,455,452 |
| Other | 172,587 | 226,903 |
| Non-current | 10,987,380 | 10,149,140 |
| Total | 12,668,069 | 13,772,519 |
(i) Over the past few years, as previously disclosed, the Company has recognized PIS/COFINS credits arising from the exclusion of ICMS, including in the form of tax substitution, from the calculation bases of these contributions. These tax credits were recorded against the recoverable taxes in the balance sheet, in the PIS/COFINS – ICMS exclusion line, as shown in the table above. The amounts that have not yet been offset substantially refer to tax credits from Regime Especial de Tributação de Bebidas Frias (“REFRI”), for the period from 2009 to 2015, in relation to which the lawsuit is currently in the final expert evaluation phase.
| 8. | INCOME TAX AND SOCIAL CONTRIBUTION |
8.1 Deferred income tax and social contribution
The amounts of deferred income tax and social contribution for each type of temporary difference are as shown below:
| 09/30/2026 | 12/31/2025 | ||||||
| Assets | Liabilities | Net | Assets | Liabilities | Net | ||
| Investment securities | 7,823 | - | 7,823 | 6,842 | - | 6,842 | |
| Intangibles | - | (1,767,539) | (1,767,539) | - | (1,836,483) | (1,836,483) | |
| Employee benefits | 916,347 | - | 916,347 | 786,297 | - | 786,297 | |
| Trade payables | 2,965,830 | (2,432) | 2,963,398 | 3,462,227 | (2,135) | 3,460,092 | |
| Trade receivables | 99,045 | (2,606) | 96,439 | 8,513 | (11,018) | (2,505) | |
| Derivative financial instruments | 29,605 | (158,003) | (128,398) | 64,997 | (171,696) | (106,699) | |
| Interest-bearing loans and borrowings | 4,593 | - | 4,593 | 7,649 | - | 7,649 | |
| Inventories | 348,023 | (153,927) | 194,096 | 390,446 | (120,188) | 270,258 | |
| Property, plant and equipment | 978,424 | (2,005,844) | (1,027,420) | 1,092,185 | (1,951,498) | (859,313) | |
| Withholding tax on undistributed profits and royalties | - | (1,769,744) | (1,769,744) | - | (2,136,201) | (2,136,201) | |
| Investments in associates and joint ventures | 340 | (383,678) | (383,338) | - | (383,678) | (383,678) | |
| Interest on capital | 652,629 | - | 652,629 | - | - | - | |
| Tax losses carried forward (i) | 3,821,433 | - | 3,821,433 | 3,715,493 | - | 3,715,493 | |
| Provisions | 1,456,592 | (3,227) | 1,453,365 | 1,606,370 | (553) | 1,605,817 | |
| Complement of income tax of foreign subsidiaries due in Brazil | - | (160,040) | (160,040) | - | - | - | |
| Impact of IFRS 16 (Leases) | 4,790 | (83,769) | (78,979) | 2,861 | (78,249) | (75,388) | |
| Exclusion of ICMS from PIS/COFINS calculation basis | - | (8,093) | (8,093) | - | (82,550) | (82,550) | |
| Other items | 168,871 | (206,642) | (37,771) | 286,065 | (163,554) | 122,511 | |
| Gross deferred tax assets/(liabilities) | 11,454,345 | (6,705,544) | 4,748,801 | 11,429,945 | (6,937,803) | 4,492,142 | |
| Netting by taxable entity | (2,912,119) | 2,912,119 | - | (3,025,533) | 3,025,533 | - | |
| Net deferred tax assets/(liabilities) | 8,542,226 | (3,793,425) | 4,748,801 | 8,404,412 | (3,912,270) | 4,492,142 | |
(i) Historically, tax authorities have offset tax losses ex-officio in administrative proceedings in which the Company and some of its subsidiaries are involved, resulting in an accumulated offset of R$314,817. This amount is included in the tax credits recognized under the line of tax losses carried forward. The contingencies in question have a probability of a possible loss.
AMBEV S.A. |
8.1.1 Realization of deferred taxes
At September 30, 2026 the deferred tax assets and liabilities expected to be utilized/settled, not related to tax losses, are: (i) to be realized until 12 months R$1,566,352; and (ii) to be realized after 12 months R$(638,981).
8.1.2 Net change in deferred taxes
The net change in deferred income tax and social contribution is as follows:
| At December 31, 2025 | 4,492,142 |
| Investment hedges – obligations related to the acquisition of a non-controlling interest | (5,000) |
| Cash flow hedge – gains/(losses) | (24,181) |
| Gains/(losses) on cumulative translation adjustments [CTA] | (240,482) |
| Recognized in other comprehensive income | (269,663) |
| Recognized in the income statement | 814,731 |
| Changes recognized directly in the balance sheet | (288,409) |
| Recognized in deferred tax | (293,076) |
| Effects of the application of IAS 29 (hyperinflation) | (293,076) |
| Recognized in the other balance sheet group | 4,667 |
| At September 30, 2026 | 4,748,801 |
8.1.3 Deferred tax assets related to tax losses
Beyond the tax credits related to tax losses effectively recognized as part of the amounts disclosed above, there are other tax credits related to tax losses that were not recorded in the balance sheets due to their low expectations of realization, based on Management’s assessment. At September 30, 2026, the accumulated balance of these credits represented R$845,153 in taxable value (R$991,549 in December 31, 2025) equivalent to a taxable basis of R$3,194,354 in September 30, 2026 (R$3,788,686 in December 31, 2025).
Additionally, tax credits related to tax losses recorded in the Brazilian ECF (Tax Accounting Bookkeeping), for the purpose of calculating Taxation on a worldwide basis, ceased to be recognized, resulting in a principal amount of R$4,748,729 as of September 30, 2026 (R$5,289,511 as of December 31, 2025).
8.2 Income tax and social contribution
The income taxes reported in the income statement are broken down as follows:
| Nine-month period ended: | Three-month period ended: | ||||
| 09/30/2026 | 09/30/2025 | 09/30/2026 | 09/30/2025 | ||
| Income tax expenses – current | (3,607,280) | (3,157,313) | (1,161,418) | (849,262) | |
| Deferred tax expenses on temporary differences | 708,791 | 901,428 | 304,424 | 543,449 | |
| Deferred tax on taxes loss carryforward movements in the current period | 105,940 | 224,907 | (25,131) | (44,359) | |
| Total deferred tax (expenses)/income | 814,731 | 1,126,335 | 279,293 | 499,090 | |
| Total income tax expenses | (2,792,549) | (2,030,978) | (882,125) | (350,172) | |
The reconciliation between the weighted nominal tax rate and the effective tax rate is summarized below:
AMBEV S.A. |
| Nine-month period ended: | Three-month period ended: | ||||
| 09/30/2026 | 09/30/2025 | 09/30/2026 | 09/30/2025 | ||
| Profit before income tax | 14,519,107 | 13,489,913 | 5,248,440 | 5,213,892 | |
| Adjustments to the taxable basis | |||||
| Other non-taxable income | (493,240) | (860,272) | (166,740) | (529,960) | |
| Government grants related to taxes on sales | (312,639) | (291,397) | (100,930) | (97,499) | |
| Share of results of associates and joint ventures | (33,439) | 8,130 | (22,768) | 5,392 | |
| Non-deductible expenses | 405,441 | 305,321 | 97,849 | 52 | |
| Taxation on a universal basis and other adjustments related to foreign subsidiaries | 495,647 | 188,692 | 107,593 | 183,699 | |
| 14,580,877 | 12,840,387 | 5,163,444 | 4,775,576 | ||
| Aggregated weighted nominal tax rate | 29.64% | 27.62% | 29.20% | 27.69% | |
| Taxes payable – nominal rate | (4,321,334) | (3,546,403) | (1,507,759) | (1,322,270) | |
| Adjustments to tax expenses | |||||
| Income tax incentives | 316,021 | 318,568 | 115,197 | 210,428 | |
| Deductible interest on capital | 1,262,533 | 1,066,866 | 496,004 | 472,152 | |
| Tax savings arising from the amortization of goodwill | 2,689 | 2,689 | 896 | 896 | |
| Withholding income tax | (215,155) | (180,426) | (84,161) | (76,899) | |
| Recognition/(write-off) of deferred charges on tax losses | (49,697) | (58,976) | (14,708) | (13,522) | |
| Effects of the application of IAS 29 (hyperinflation) | 48,634 | (14,151) | 3,853 | 13,790 | |
| Other tax adjustments | 163,760 | 380,855 | 108,553 | 365,253 | |
| Income tax and social contribution expense | (2,792,549) | (2,030,978) | (882,125) | (350,172) | |
| Effective tax rate | 19.23% | 15.06% | 16.81% | 6.72% | |
The main events that impacted the effective tax rate for the period were:
| · | Other non-taxable income: it refers mainly to the revenues arising from monetary updates (Selic) on tax credits. Additionally, specifically in the third quarter of 2025, other non-taxable income arising from the sale of the subsidiary SLU was recognized, as detailed in Note 1.3.4 – Completion of the third tranche – Sale of subsidiary. |
| · | Government grants related to taxes on sales: these represent regional incentives and economic development policies, primarily related to local production to generate economic and social impact. Before the advent of Federal Law No. 14,789/2023, those grants were not subject to income tax and social contribution. In this regarding, since August 2024 companies in the group have obtained favorable decisions, in effect since then, exempting them from collecting IRPJ and CSLL on amounts determined as government grants related to tax benefits deemed as ICMS presumed credits. |
| · | Non-deductible expenses: primarily refer to the additional costs incurred in acquiring foreign currency in certain jurisdictions where the Group operates, used mainly for the remittance of earnings to the parent companies. |
| · | Taxation on a universal basis and other adjustments related to foreign subsidiaries: the additional income taxes due in Brazil on the income of foreign-controlled entities, in accordance with Law No. 12,973/2014. It also includes local permanent adjustments to foreign companies consolidated within the group, as well as the effects arising from some of these companies having a functional currency that differs from the currency used for tax calculations. |
| · | Income tax incentives: it refers to tax incentives related to income tax granted by the Brazilian Federal Government to promote regional development in certain areas of the North and Northeast of the country and to the PAT (“Programa de Alimentação do Trabalhador”). These incentives are recorded in the results on an accruals basis and allocated to fiscal incentives reserve, as per item (13.3.1) "Tax incentives" within note 13 – Changes in equity. |
| · | Withholding income tax: this balance is related to tax due on dividends to be distributed by subsidiaries located outside of Brazil under local tax legislation. The recorded amounts in 2026 are mainly related to withholding tax calculated on profits earned in 2026 and to exchange differences on deferred income tax related to the undistributed profits of subsidiaries. |
AMBEV S.A. |
| · | Deductible interest on capital (“IOC”): under Brazilian law, companies have an option to remunerate their shareholders through the payment of IOC, which is deductible for income tax purposes. The amount of IOC is impacted by the taxable result, net income reserves of the Company and by the long-term interest rate (“TJLP”). These remunerations are deductible for income tax purposes. |
| · | Effects of the application of IAS 29 (hyperinflation): the Company’s subsidiary in Argentina operates in a hyperinflationary economy thus subject to the monetary correction of its non-financial assets and liabilities, its equity and its statement of income, which may impact the consolidated effective tax rate, implying variation between periods. |
| · | Other tax adjustments: in the third quarter of 2025, the Group’s effective tax rate was impacted by a non-recurring effect arising from the partial reversal of a liability related to the Special Tax Regularization Program (“PERT 2017”) at CRBS. This reversal occurred due to the application, by the tax authorities, of Article 14 of Brazilian Federal Law No. 14,689/2023 to a portion of the outstanding tax debt under PERT, which resulted in the recovery of expenses incurred in prior periods. This article established the unenforceability of penalties imposed in tax assessments that exceed one hundred percent (100%) of the tax debt amount, which had been declared unconstitutional by the Federal Supreme Court, as well as the unenforceability of the related interest. The total reduction in the liability amounted to R$644 million. Of this amount, R$375 million was recorded under income tax and related to the reduction in the penalty, representing the main effect reflected in the “Other tax adjustments” line item for the period. The remaining R$269 million was recognized in financial income and related to the corresponding interest |
| 9. | PROPERTY, PLANT AND EQUIPMENT |
| 09/30/2026 | 12/31/2025 | |
| Property, plant and equipment | 22,916,912 | 24,617,947 |
| Right of use assets | 2,382,879 | 3,026,370 |
| 25,299,791 | 27,644,317 |
AMBEV S.A. |
9.1 Changes in the carrying amount of property, plant, and equipment
| Carrying amount | |||||||||||||
| At December 31, 2024 | Cumulative translation adjustments (CTA) | Effects of the application of IAS 29 (hyperinflation) | Acquisitions | Depreciation | Disposals and write-offs | Transfers | Subsidiary Restructuring (i) | At December 31, 2025 | Acquisition cost | Depreciation | Total | ||
| Land and buildings | 11,129,846 | (1,089,380) | 411,668 | 12,150 | (463,596) | (45,497) | 754,751 | (118,667) | 10,591,275 | 16,710,784 | (6,119,509) | 10,591,275 | |
| Plant and equipment | 12,555,289 | (1,085,314) | 358,182 | 375,785 | (3,756,473) | (23,935) | 2,997,705 | (134,001) | 11,287,238 | 47,729,517 | (36,442,279) | 11,287,238 | |
| Fixtures and accessories | 927,840 | (60,495) | 12,817 | 113,453 | (476,269) | (8,377) | 385,549 | (5,448) | 889,070 | 7,896,162 | (7,007,092) | 889,070 | |
| Under construction | 2,521,564 | (181,846) | 63,867 | 3,613,877 | - | - | (4,175,390) | 8,292 | 1,850,364 | 1,850,364 | - | 1,850,364 | |
| Total | 27,134,539 | (2,417,035) | 846,534 | 4,115,265 | (4,696,338) | (77,809) | (37,385) | (249,824) | 24,617,947 | 74,186,827 | (49,568,880) | 24,617,947 | |
| Carrying amount | |||||||||||||
| At December 31, 2025 | Cumulative translation adjustments (CTA) | Effects of the application of IAS 29 (hyperinflation) | Acquisitions | Depreciation | Disposals and write-offs | Transfers | Subsidiary Restructuring (i) | At September 30, 2026 | Acquisition cost | Depreciation | Total | ||
| Land and buildings | 10,591,275 | (520,608) | 388,922 | 1,010 | (380,166) | (3,659) | 329,066 | (60,571) | 10,345,269 | 16,629,254 | (6,283,985) | 10,345,269 | |
| Plant and equipment | 11,287,238 | (455,888) | 282,296 | 167,032 | (2,535,615) | (12,186) | 1,621,468 | (42,242) | 10,312,103 | 47,634,437 | (37,322,334) | 10,312,103 | |
| Fixtures and accessories | 889,070 | (43,295) | 8,869 | 132,008 | (360,276) | - | 421,419 | (5,167) | 1,042,628 | 7,264,405 | (6,221,777) | 1,042,628 | |
| Under construction | 1,850,364 | (65,523) | 23,134 | 1,928,253 | - | - | (2,504,944) | (14,372) | 1,216,912 | 1,216,912 | - | 1,216,912 | |
| Total | 24,617,947 | (1,085,314) | 703,221 | 2,228,303 | (3,276,057) | (15,845) | (132,991) | (122,352) | 22,916,912 | 72,745,008 | (49,828,096) | 22,916,912 | |
(i) Effect related to the deconsolidation of balance sheet amounts, including the sale of a subsidiary.
AMBEV S.A. |
9.2 Changes in the carrying amount of right-of-use assets
| Carrying amount | |||||||||||||
| At December 31, 2024 | Cumulative translation adjustments (CTA) | Effects of the application of IAS 29 (hyperinflation) | Additions | Depreciation | Write-offs | Transfers | Subsidiary Restructuring (i) | At December 31, 2025 | Acquisition cost | Depreciation | Total | ||
| Buildings | 1,235,289 | (55,594) | 7,484 | 697,595 | (463,235) | (1,135) | (35,656) | (649) | 1,384,099 | 3,764,191 | (2,380,092) | 1,384,099 | |
| Machinery, equipment and vehicles | 1,726,325 | (20,933) | 608 | 781,748 | (740,263) | (212,813) | 22,944 | - | 1,557,616 | 4,487,363 | (2,929,747) | 1,557,616 | |
| Others | 74,041 | (7,666) | 2,779 | 73,990 | (60,318) | (447) | 2,276 | - | 84,655 | 277,870 | (193,215) | 84,655 | |
| Total | 3,035,655 | (84,193) | 10,871 | 1,553,333 | (1,263,816) | (214,395) | (10,436) | (649) | 3,026,370 | 8,529,424 | (5,503,054) | 3,026,370 | |
| Carrying amount | ||||||||||||
| At December 31, 2025 | Cumulative translation adjustments (CTA) | Effects of the application of IAS 29 (hyperinflation) | Additions | Depreciation | Write-offs | Subsidiary Restructuring (i) | At September 30, 2026 | Acquisition cost | Depreciation | Total | ||
| Buildings | 1,384,099 | (26,001) | 2,701 | 191,098 | (335,101) | (1,735) | - | 1,215,061 | 3,789,133 | (2,574,072) | 1,215,061 | |
| Machinery, equipment and vehicles | 1,557,616 | (8,510) | (620) | 152,874 | (575,765) | (94,133) | (2,294) | 1,029,168 | 4,469,262 | (3,440,094) | 1,029,168 | |
| Others | 84,655 | (2,896) | 1,959 | 104,892 | (41,837) | (7,732) | (391) | 138,650 | 360,742 | (222,092) | 138,650 | |
| Total | 3,026,370 | (37,407) | 4,040 | 448,864 | (952,703) | (103,600) | (2,685) | 2,382,879 | 8,619,137 | (6,236,258) | 2,382,879 | |
(i) Effect related to the deconsolidation of balance sheet amounts, including the sale of a subsidiary.
AMBEV S.A. |
| 10. | TRADE PAYABLES |
| 09/30/2026 | 12/31/2025 | |
| Trade payables | 19,870,838 | 22,596,092 |
| Related parties | 1,305,278 | 1,146,743 |
| Current | 21,176,116 | 23,742,835 |
| Trade payables | 80,060 | 67,682 |
| Related parties | 149,932 | 245,277 |
| Non-current | 229,992 | 312,959 |
| Total | 21,406,108 | 24,055,794 |
The present value adjustment related to the obligations recorded in trade payables at September 30, 2026 is R$257,150 (R$243,031 at December 31, 2025).
The subsidiaries in Argentina, Chile, and Panama have discount transactions of endorsed trade bills (trade payables securitization) with vendors in the amount of R$87,126 at September 30, 2026 (R$20,247 at December 31, 2025). In general, such discount transactions occur due to legal requirements existing in these jurisdictions. These transactions retain their commercial characteristics, as there are no changes to the previously agreed terms (amount, term or counterparty), and the decision to obtain early payment of the receivables remains at the sole discretion of the vendors. Therefore, these transactions do not result in any additional obligation for the Company.
| 11. | INTEREST-BEARING LOANS AND BORROWING |
| 09/30/2026 | 12/31/2025 | |
| Secured bank loans | 17,580 | 18,831 |
| Other secured loans | 120,024 | 135,510 |
| Lease liabilities | 859,493 | 1,012,984 |
| Current liabilities | 997,097 | 1,167,325 |
| Secured bank loans | 63,291 | 80,870 |
| Other secured loans | 152,770 | 176,067 |
| Lease liabilities | 1,501,601 | 1,962,662 |
| Non-current liabilities | 1,717,662 | 2,219,599 |
| Total | 2,714,759 | 3,386,924 |
Additional information regarding the exposure of the Company to interest rates, foreign currency risk and debt repayment schedule is disclosed in Note 20 - Financial instruments and risks.
11.1 Contractual clauses (covenants)
At September 30, 2026, at December 31, 2025, and up to the date of issuance of these consolidated financial statements, no events of default, breaches of covenants, or significant contractual changes occurred that would result in changes to the payment terms of loan and financing agreements.
11.2 Leasing contracts regarding the term and discount rate (Brazil)
The Company estimated the discount rates based on the risk-free forward interest rate curves observable in the Brazilian market, for terms consistent with the lease contracts, plus the Company-specific credit spread. The risk-free curves were obtained from observable market information, while the credit spreads were estimated based on quotations provided by financial institutions:
AMBEV S.A. |
| Rate % | ||
| Lease Term | 09/30/2026 | 12/31/2025 |
| 2026 - 2030 | 12.56% | 12.23% |
| 2031 - 2040 | 13.31% | 12.94% |
| 12. | PROVISIONS, CONTINGENT LIABILITIES AND CONTINGENT ASSETS |
The Company and its subsidiaries are involved in administrative and judicial proceedings and arbitrations arising from the normal course of business. The assessment of the likelihood of loss, carried out by the Company with the support of its legal advisors, considers the likelihood of the Company position being accepted at the end of the proceedings, considering the applicable legislation, the case law on the subject and the existing evidence. Due to their nature, these proceedings involve inherent uncertainties, including, but not limited to, decisions by courts and tribunals agreements between the parties involved and governmental actions and, as a result, Management cannot, at this stage, estimate the precise timing to conclude such proceedings.
12.1 Provisions
The lawsuits considered probable of loss are fully provisioned, under the terms of IAS 37 - Provisions, Contingent Liabilities and Contingent Assets, and have a tax, civil or labor nature. Cases are considered likelihood of loss when there is established or binding case law unfavorable to the position defended by the Company and its subsidiaries, or, in the case of factual or evidentiary disputes, when the Company and its subsidiaries do not have the necessary and sufficient evidence to prove the claimed right.
12.1.1 Main lawsuits with a probable risk of loss
Taxes on sales: in Brazil, the Company and its subsidiaries are parties to various administrative and judicial proceedings related to ICMS, IPI, PIS and COFINS taxes, considered as probable likelihood of loss. Such proceedings include, among others, tax offsetting, appropriation of tax credits and alleged insufficient payment of the respective taxes.
Labor: the Company and its subsidiaries are parties to labor lawsuits considered likely to result in loss, involving former employees, including those from outsourced service providers. The main issues involve overtime and related effects and respective charges.
Civil: the Company and its subsidiaries are involved in civil proceedings considered as representing a probable likelihood of loss. The most relevant portion of these lawsuits was filed by former distributors, mainly in Brazil, mostly claiming damages resulting from the termination of their contracts with the Company.
Other taxes: refer to provisions for lawsuits concerning taxes unrelated to sales or income taxation. The uncertain tax treatments related to income taxes with a likelihood of probable loss have their value reported directly in the income tax and social contribution payable line, as per IFRIC 23 - Uncertainty on the Treatment of Income Taxes.
12.1.2 Provisions changes
| Tax on sales | Labor | Civil | Other taxes | Restructuring (i) | Total | |
| Balance at December 31, 2024 | 325,906 | 195,110 | 372,021 | 214,206 | 4,572 | 1,111,815 |
| CTA effect | - | (1,955) | (7,372) | (7,435) | (301) | (17,063) |
| Constituted provisions | 423,011 | 285,111 | 273,018 | 275,282 | 23,348 | 1,279,770 |
| Consumed provisions | (129,832) | (211,490) | (165,833) | (42,501) | (22,511) | (572,167) |
AMBEV S.A. |
| Reversed provisions | (93,989) | (49,884) | (174,778) | (34,649) | - | (353,300) |
| Balance at December 31, 2025 | 525,096 | 216,892 | 297,056 | 404,903 | 5,108 | 1,449,055 |
| CTA effect | - | (848) | (2,117) | (2,268) | (369) | (5,602) |
| Constituted provisions | 62,839 | 203,070 | 49,075 | 55,825 | 2,067 | 372,876 |
| Consumed provisions | (62,673) | (122,065) | (27,950) | (8,646) | (6,243) | (227,577) |
| Reversed provisions | (108,446) | (67,998) | (22,168) | (4,747) | - | (203,359) |
| Balance at September 30, 2026 | 416,816 | 229,051 | 293,896 | 445,067 | 563 | 1,385,393 |
(i) Restructuring provisions mainly relate to organizational improvements, right-sizing and the Group’s digitalization efforts.
12.1.3 Expected settlement of provisions
| 09/30/2026 | 12/31/2025 | ||||||
| Current | Non-current | Total | Current | Non-current | Total | ||
| Tax on sales | 200,072 | 216,744 | 416,816 | 124,282 | 400,814 | 525,096 | |
| Labor | 124,401 | 104,650 | 229,051 | 99,389 | 117,503 | 216,892 | |
| Civil | 73,213 | 220,683 | 293,896 | 81,425 | 215,631 | 297,056 | |
| Other taxes | 264,163 | 180,904 | 445,067 | 261,161 | 143,742 | 404,903 | |
| Total provision for disputes and litigation | 661,849 | 722,981 | 1,384,830 | 566,257 | 877,690 | 1,443,947 | |
| Restructuring (i) | 563 | - | 563 | 5,108 | - | 5,108 | |
| Total provisions | 662,412 | 722,981 | 1,385,393 | 571,365 | 877,690 | 1,449,055 | |
(i) Restructuring provisions mainly relate to organizational improvements, right-sizing and the Group’s digitalization efforts.
The expected settlement of provisions was based on Management’s best estimate, in line with their internal and external legal advisors’ assessments, at the consolidated balance sheet date.
12.2 Contingencies
The Company and its subsidiaries maintain administrative and judicial disputes with fiscal authorities in Brazil related to certain tax positions adopted when calculating the income tax and social contribution, which, based on Management’s current evaluation, probably are going to be accepted in superior court decisions of last instance, considering the regular compliance with tax laws, case law, and evidence produced, in line with IFRIC 23 - Uncertainty over Income Tax Treatments. The Group is also part on tax proceedings related to other taxes, which involve possible loss risk, according to Management's assessment. To these uncertain tax treatments and possible contingencies there are no constituted provision, due to the likelihood of loss assessment carried out. Such proceedings represent the following estimates.
| 09/30/2026 | 12/31/2025 | |
| Income tax and social contribution | 77,630,859 | 72,201,276 |
| Value-added and excise duties | 28,095,435 | 28,810,054 |
| PIS and COFINS | 1,995,898 | 1,876,543 |
| Others | 3,893,722 | 3,046,204 |
| 111,615,913 | 105,934,077 |
Contingencies with a remote risk of loss are not disclosed, as the possibility of any settlement is remote, in accordance with IAS 37 - Provisions, Contingent Liabilities and Contingent Assets.
The Company and its subsidiaries have guarantee-insurance bonds and letters of guarantee for some legal proceedings, presented as guarantees on civil, labor and tax lawsuits.
12.2.1 Main contingencies with a possible risk of loss
The changes in the amount of contingencies reported relate mainly to the increase resulting from monetary restatement. In addition, the main process classified with a possible loss probability, which relevant changed between December 31, 2025 and September 30, 2026, are summarized in the table below, along with their respective estimated values involved in the cases.
AMBEV S.A. |
|
Uncertainty over the treatment of income taxes In accordance with IFRIC 23 (note 8 - Income tax and social contribution) |
Estimates (in million of Brazilian Reais) | ||
| # | Description of the main processes | 09/30/2026 | 12/31/2025 |
| 1 |
Deductibility of IOC expenses During the 2013 fiscal year, as approved in a General Meeting, the Company implemented a corporate restructuring aimed at simplifying its structure and unifying its share classes, among other objectives. One of the steps of this restructuring involved the exchange of shares and subsequent incorporation of the shares of its subsidiary Companhia de Bebidas das Américas into Ambev S.A. As a consequence of this operation, Ambev S.A. recognized in its accounting records the counterpart of the difference between the value of its shares issued for this exchange and the book value of the subsidiary's shares in equity, in accordance with IFRS 10 - Consolidated Financial Statements, under the item "adjustments to equity". As a result of this restructuring, since 2019, Ambev has been receiving tax assessments from the Brazilian Federal Tax Authorities (“RFB”) related to the interest on capital (“IOC”) deduction for calendar years 2014 to 2021. The assessments refer primarily to the accounting and corporate effects of the restructuring carried out by Ambev in 2013 and its impact on the increase in the deductibility of IOC expenses. In all cases Ambev obtained partially favorable decisions at the first-level administrative court and filed appeals to the Lower Administrative Court (“CARF). The appeals related to tax assessments involving calendar years 2014 and 2017 to 2021 await judgment by CARF. The favorable portion of the decisions rendered by the first-level administrative court in these cases is subject to mandatory review by the CARF as well. With respect to the tax assessment involving calendar years 2015 and 2016, in May 2024 the company obtained an unfavorable decision on the merits under discussion, but favorable as it relates to the fines charged by the tax authorities, as the court decision cancelled the qualified penalties. In December 2024, the favorable portion of the decision became final, and the Company appealed the unfavorable portion to CARF. CARF did not accept the appeal, and in October 2025, Ambev filed appeals (i) to the Upper Administrative Court (“CSRF”), with respect to the main merits of the assessment and (ii) to the judicial courts on a specific portion of the 2015 assessment. In December 2025, Ambev received an unfavorable decision from the first-level judicial court, which did not analyze the merits of the specific portion of the 2015 assessment as the court determined it would also involve the main merits, and filed an appeal. In April 2026, CARF declined to accept the appeal on the main merits of the assessment, and Ambev filed a lawsuit to have the matter decided at the judicial level. The updated assessed value of this uncertain tax treatment, in accordance with IFRIC 23, is approximately R$33.5 billion as of September 30, 2026 (R$30.8 billion as of December 31, 2025). Due to the assessment of the likelihood of loss, no provision was made in the period. This uncertain tax treatment, according to IFRIC 23, continued to be applied by Ambev and affected subsequent calendar years to those assessed (2022 and 2023), during which the Company also distributed IOC and deducted them from the taxable base of its Corporate Income Tax. Therefore, if the deductibility of IOC is also questioned in the future, on the same basis and with the same grounds as the tax assessments mentioned, the Company estimates that the outcome of these potential new discussions would be consistent with the period already assessed. In December 2023, Provisional Measure 1,185, of August 2023, was converted into a law (No. 14,789/2023), which changes the basis for calculating Interest on Capital as of January 1, 2024, making this uncertain tax treatment limited to Interest on Capital calculated in accordance with legislation in force before the aforementioned law effective date. |
33,484 |
30,782 |
AMBEV S.A. |
| 2 |
Disallowance of tax paid abroad Since 2014, the Company has been receiving tax assessments, relating to calendar years from 2007 onwards, which disallow the use of foreign tax credits relating to income tax paid abroad by its controlled companies. The Company has challenged these assessments in the administrative and judicial courts. The Company has obtained favorable outcomes in certain cases, including a final favorable administrative decision for calendar year 2010 and the full cancellation of a tax assessment relating to calendar year 2012. Two other cases involving calendar year 2012, relating to the requirements for the offset of foreign tax credits, remain under discussion. One of these cases is currently under judicial review following an unfavorable decision to the Company at the administrative court. With respect to tax assessments relating to calendar years 2015 and 2016, the Company received unfavorable decisions at the administrative level in three out of four cases, which are currently subject to judicial review. In 2026, additional tax assessments relating to calendar years 2018, 2020 and 2023 were received, and defenses were filed. The remaining cases are still awaiting final decisions at both administrative and judicial courts. In addition, the Tax Authorities issued separate tax assessments to charge isolated fines due to the lack of monthly prepayments of income tax as a result of allegedly undue deductions of taxes paid abroad. Such assessments have been issued for calendar years 2015 through 2021. At the administrative level, final decisions unfavorable to the Company were rendered for calendar years 2015 and 2019, which are currently under judicial review. Assessments relating to calendar years 2017 and 2018 were cancelled as a result of, respectively, a favorable decision from CARF which became final in September 2026, and the application of Law 14,689/2023 to the 2018 case in July 2026 in light of the decision rendered to the Company by a tie-vote at CARF. These decisions resulted in the cancelation of approximately 1.1 billion Brazilian real in contingencies as of September 30, 2026. In July 2026, the Company received an additional assessment relating to calendar year 2021 and filed a defense, which remains pending before the first-level administrative court. The remaining cases are still awaiting final decisions in the administrative courts. The updated assessed value of this uncertain tax treatment, in accordance with IFRIC 23 - Uncertainty over Income Tax Treatments, is approximately R$22.9 billion as of September 30, 2026 (R$19.1 billion as of December 31, 2025), and, due to the assessment of the likelihood of loss, no provision was made in the period. This uncertain tax treatment, according to IFRIC, regarding income tax credits paid abroad, continued to be applied by the Company and impacted subsequent calendar years to those assessed (2021-2026). If new questions arise in the future, on the same basis and with the same grounds as the tax assessments mentioned, the Company estimates that the outcome of these potential new discussions would be consistent with the periods already assessed. |
22,906 | 19,091 |
| 3 |
Foreign Profits Since 2005, the Company and some of its subsidiaries have been subject to tax assessments filed by the RFB relating to the taxation of profits earned by subsidiaries domiciled abroad under various arguments. The Company is challenging these assessments in the administrative and judicial courts. In 2022 and 2023, CARF rendered favorable and partially favorable decisions to the Company, related to 2012 and 2014 calendar years. These decisions cancelled part of the disputed tax assessments, recognizing the validity of the methodology adopted by the Company with respect to the taxation of foreign profits and the goodwill amortization by foreign subsidiaries. Part of these decisions became final, representing the cancellation of the related tax contingency in the approximate amount 1.0 billion Brazilian real as of 30 September 2024. In August 2024 Ambev received a partially favorable decision from the first-level administrative court with respect to a tax assessment related to the 2018 calendar year. Both Ambev and the tax authorities filed appeals and the case awaits decision by CARF. In November 2024, Ambev received a new tax assessment relating to the taxation of foreign profits for calendar year 2019 and filed a defense, the outcome of which was partially favorable to the Company. The Company and the tax authorities filed appeals to CARF which are awaiting judgment. In December 2025, the Company received a tax assessment relating to calendar year 2020 and filed the defense with the first-level administrative court which issued a partially favorable decision to Ambev in June 2026. This decision is not final, and both the Company and the tax authorities filed appeals with CARF, that await judgment. In the judicial proceedings, the Company has received favorable injunctions that suspend the enforceability of the assessed tax claim. Some proceedings have also resulted in favorable final decisions at the second-level judicial courts, while other proceedings remain pending before the Superior Court of Justice. The updated amount of this uncertain tax treatment, in accordance with IFRIC 23, already assessed, is approximately R$7.1 billion as of September 30, 2026 (R$8.0 billion as of December 31, 2025). This uncertain tax treatment, according to IFRIC 23, continued to be applied by the Company and impacted subsequent calendar years to those assessed (2021-2025). If new inquiries arise in the future, on the same basis and with the same grounds as the tax assessments mentioned, the Company estimates that the outcome of these eventual new discussions would be consistent with the periods already assessed. |
7,057 | 7,996 |
| 4 |
Presumed Profit In April 2016, Arosuco (a subsidiary of Ambev) received a tax assessment regarding the use of the “presumed profit” method for the calculation of income tax and the social contribution on net profits instead of the “real profit” method. In September 2017, Arosuco received an unfavorable first-level administrative decision and filed an appeal. In January 2019, CARF rendered a favorable decision to Arosuco, which became definitive. In March 2019, Arosuco received a new tax assessment regarding the same subject and filed a defense. In October 2019, Arosuco received an unfavorable first-level administrative decision and filed an appeal with CARF. In February 2024, Arosuco received a favorable decision at CARF, which was appealed by the tax authorities to the CSRF. In September 2025, CSRF rendered an unfavorable decision to Arosuco, which upheld the tax authorities’ arguments and remanded the case to the CARF. In April 2026, CARF rendered a favorable decision to Arosuco, resulting in the cancellation of the tax assessment. This decision became final in July 2026. As a result of this decision as of 30 September 2026, there was no tax contingency associated with this uncertain tax position. On December 31, 2025, before this final favorable decision, the updated amount of this uncertain tax treatment, according to ICPC 22/IFRIC 23, was R$601.3 million. |
- | 601 |
| Indirect taxes |
Estimates (in million of Brazilian Reais) | ||
| # | Description of the main processes | 09/30/2026 | 12/31/2025 |
| 1 |
Social contributions – Other Credits In 2022, Ambev received a tax assessment and administrative decisions challenging the offsetting regarding certain PIS/COFINS’ credits. The tax authorities primarily argue that (i) certain credits claimed by Ambev are unrelated to the production proceedings and (ii) Ambev has not adequately demonstrated its right to utilize such credits. The assessment was challenged at the administrative level and after a partially favorable judgment, Ambev filed an appeal with CARF, which resulted in the proceeding being remanded for tax expert examination in September 2024. In March 2026, the Lower Administrative Court (CARF) issued a partially favorable decision in the taxpayer’s appeal. While certain relevant matters were decided in favor of the company, the main issues were ruled against the taxpayer by a tie-vote. This decision is not final, and Ambev filed a motion for clarification on certain aspects of the decision, which is pending trial. Regarding the administrative decisions, they are still awaiting judgment by the first-level administrative court. The Company estimates that the updated amount classified as a possible loss related to these proceedings is approximately R$655.7 million as of September 30, 2026 (R$615.1 million as of December 31, 2025). |
656 | 615 |
AMBEV S.A. |
| 2 |
ICMS-ST Trigger Over the years, Ambev has received tax assessments to charge supposed ICMS differences considered due when the price of the products sold by Ambev is above the fixed price table basis established by the relevant states, cases in which the state tax authorities contend that the calculation basis should be based on a value-added percentage over the actual prices and not the fixed table price. Ambev is currently challenging those charges before the courts. The cases are being challenged at both the administrative and judicial levels. In February 2025, the Supreme Court rendered its judgment on Topic 816, establishing a limit of 20% for late payment fines. This decision is applicable to certain cases under consideration and represents a reclassification of potential loss from possible to remote, amounting to R$0.8 billion reais. In July 2025, Law No. 25,378/2025 of the state of Minas Gerais, which limits the application of isolated fines to a maximum of 50% of the tax due, was enacted. This law is applicable to a portion of the cases under discussion and resulted in a reclassification of approximately R$1.0 billion Brazilian real from possible to remote loss. Additionally, in November 2025, Ambev received new tax assessments from the State of Maranhão amounting to approximately R$1.4 billion. In August 2026, two administrative proceedings in Maranhão were concluded favorably to the Company, resulting in the cancellation of two tax assessments corresponding to R$1.2 billion, in historical amounts. The Company estimates that the total updated amount of possible risk involved in the processes related to this matter, as of September 30, 2026, is approximately R$11.6 billion (R$12.0 billion as of December 31, 2025). |
11,563 | 11,987 |
| 3 |
ICMS – FAIN In recent years, Ambev has received tax assessments issued by the State of Paraíba for the collection of ICMS related to the Fund for Industrial Development Support of Paraíba (FAIN). The alleged infractions stem from a controversy regarding the transfer of the tax incentive from the former Companhia de Bebidas das Américas to its successor Ambev S.A., as well as methodological issues regarding the calculation of the benefit. The Company is contesting these infractions in administrative and judicial courts. In August 2026, three administrative proceedings related to this matter were decided in favor of the Company. As a result of these favorable rulings, Ambev reassessed the likelihood of loss associated with these proceedings and reclassified approximately R$830 million from possible to remote loss. Ambev estimates that the updated value classified as a possible loss involved in these proceedings, as of September 30, 2026, is approximately R$81 million (R$762 million as of December 31, 2025). |
81 | 762 |
12.2.2 Tax Proceeding Initiated by the Group
The Company is also a party on other tax proceedings in which it is the claimant and discusses the possibility of recovering or avoiding the payment of taxes that, in the Management's view, lack constitutional and/or legal support for their enforcement. As disclosed on the accounting policies, the Company does not recognize contingent assets in its financial statements. If the inflow of economic benefits becomes probable, based on a forecast assessment conducted by external legal advisors in conjunction with the internal assessment of the Administration, the Company discloses the contingent asset. When the inflow of economic benefits becomes virtually certain, such as when a final judgment is rendered in the case and the gain can be reliably estimated, the asset is no longer contingent, and the Company recognizes it in the financial statements for the period in which the change in estimate occurs.
The contingent assets with relevant changes until September 30, 2026, are summarized in the table below.
| # | Description of the main processes |
| 1 |
Cerbuco Brewing Inc Arbitration Cerbuco Brewing Inc. (“Cerbuco”), a Canadian subsidiary of Ambev, owns a 50% equity ownership in Cerveceria Bucanero S.A. (“Bucanero”), a joint venture in Cuba. In 2021, Cerbuco initiated an arbitration proceeding at the International Chamber of Commerce (“ICC”), relating to a potential breach of certain obligations in connection with the joint venture. On 24 October 2024, the ICC informed the parties of the partial arbitral award, which was partially favorable to Cerbuco. On September 9, 2026, the final arbitral award in the second phase of the arbitration was rendered, awarding compensation to Cerbuco. The decision is final, with only a request for clarification pending judgment. In May 2025, Cerbuco was notified of an annulment action filed by Coralsa (its partner in the joint venture) in Paris, against the partial arbitral award. The award in the second phase of the arbitration is also subject to an annulment action, and any favorable decision for Coralsa in this case may affect both arbitral awards. |
| 2 |
Federal taxation on VAT Incentives After the enactment of Law No. 14,789, effective as of Jan 1st, 2024, the VAT incentives deemed as “government grants for investment”, began being taxed for IRPJ/CSLL and PIS/COFINS purposes. With that respect, Ambev and some of its subsidiaries in Brazil have filled their own legal procedures to challenge the legal aspects of the newly enacted Law. During 2024 and 2025, some of the companies obtained favorable judicial decisions related to VAT Incentives deemed as ICMS presumed credits which relief them, from the calculation periods starting after each decision was issued, from taxing IRPJ/CSLL and PIS/COFINS. This reflected, up through September 30, 2026, in accumulated amounts utilized of R$278 million and R$775 million, respectively. |
AMBEV S.A. |
| 13. | CHANGES IN EQUITY |
13.1 Issued capital
At September 30, 2026, the authorized and issued capital, fully subscribed and paid in, amounting to R$58,308,102 (R$58,275,696 in September 30, 2025) was composed of 15,484,665 common shares (15,761,639 in September 30, 2025), book entry, registered, and with no par value, distributed as follows:
| 09/30/2026 | 09/30/2025 | ||||
| Shareholder | Thousands of common shares | % | Thousands of common shares | % | |
| Interbrew International GmbH | 8,441,666 | 54.53% | 8,441,666 | 53.57% | |
| Ambrew S.A.R.L. | 1,287,686 | 8.32% | 1,287,740 | 8.17% | |
| Fundação Zerrenner | 1,609,987 | 10.40% | 1,609,987 | 10.21% | |
| Market (free float) | 4,077,148 | 26.32% | 4,253,041 | 26.98% | |
| Treasury shares | 68,178 | 0.44% | 169,205 | 1.07% | |
| 15,484,665 | 100.00% | 15,761,639 | 100.00% | ||
| 09/30/2026 | 09/30/2025 | ||||
| Thousands of common shares | Thousands of Real | Thousands of common shares | Thousands of Real | ||
| Opening balance | 15,761,639 | 58,275,079 | 15,757,657 | 58,226,036 | |
| Capital increase (i) | 2,026 | 33,023 | 3,982 | 49,660 | |
| Share cancellation (ii) | (279,000) | - | - | - | |
| Balance at the end of the period | 15,484,665 | 58,308,102 | 15,761,639 | 58,275,696 | |
(i) Capital increase related to the issue of shares, under the Company’s share-based payment programs.
(ii) Cancellation of treasury shares, approved by the Board of Directors in August 2026, without reducing the share capital.
13.2 Capital reserves
| Capital Reserves | |||||
| Treasury shares | Share Premium | Other capital reserves | Share-based Payments | Total | |
| Balance at January 1, 2025 | (1,332,743) | 53,662,811 | 700,898 | 2,305,444 | 55,336,410 |
| Gains/(losses) of controlling interest | - | - | - | - | - |
| Share buybacks, results from treasury shares, and share-based payments | (1,737,943) | - | - | 168,510 | (1,569,433) |
| Balance at September 30, 2025 | (3,070,686) | 53,662,811 | 700,898 | 2,473,954 | 53,766,977 |
| Capital Reserves | |||||
| Treasury shares | Share Premium | Other capital reserves | Share-based Payments | Total | |
| Balance at January 1, 2026 | (2,947,613) | 53,662,811 | 700,898 | 2,365,289 | 53,781,385 |
| Share buybacks, results from treasury shares, and share-based payments | (3,272,583) | - | - | 208,346 | (3,064,237) |
| Share cancellation | 4,095,498 | (4,095,498) | - | - | - |
| Balance at September 30, 2026 | (2,124,698) | 49,567,313 | 700,898 | 2,573,635 | 50,717,148 |
AMBEV S.A. |
13.2.1 Share buyback and treasury shares results
Treasury shares represent the Company’s own issued shares that have been repurchased by the Company. The results of treasury shares refer to gains and losses arising from share-based payment transactions and others related items. Changes in treasury shares were as follows:
| Acquisition/(realization of shares) | Results from treasury shares | Total treasury shares | |||||
| Thousands of shares | Thousands of Brazilian Reais | Thousands of shares | Thousands of Brazilian Reais | ||||
| Balance at January 1, 2025 | 29,807 | (365,626) | (967,117) | (1,332,743) | |||
| Share Buyback | 146,902 | (1,831,123) | - | (1,831,123) | |||
| Share-Based Payment | (7,504) | 87,081 | - | 87,081 | |||
| Results from shares | - | - | 6,099 | 6,099 | |||
| Balance at September 30, 2025 | 169,205 | (2,109,668) | (961,018) | (3,070,686) | |||
| Acquisition/(realization of shares) | Results from treasury shares | Total treasury shares | |||||
| Thousands of shares | Thousands of Brazilian Reais | Thousands of shares | Thousands of Brazilian Reais | ||||
| Balance at January 1, 2026 | 145,113 | (1,836,585) | (1,111,028) | (2,947,613) | |||
| Share Buyback | 208,000 | (3,333,022) | - | (3,333,022) | |||
| Share-Based Payment | (5,935) | 73,304 | - | 73,304 | |||
| Share cancellation | (279,000) | 4,095,498 | - | 4,095,498 | |||
| Results from shares | - | - | (12,865) | (12,865) | |||
| Balance at September 30, 2026 | 68,178 | (1,000,805) | (1,123,893) | (2,124,698) | |||
13.3 Net income reserves
| Profit reserves | ||||
| Investment reserve | Legal reserve | Fiscal incentives | Total | |
| Balance at January 1, 2025 | 36,125,152 | 4,456 | 17,507,411 | 53,637,019 |
| Declared dividends | (496,600) | - | - | (496,600) |
| Balance at September 30, 2025 | 35,628,552 | 4,456 | 17,507,411 | 53,140,419 |
| Profit reserves | ||||
| Investment reserve | Legal reserve | Fiscal incentives | Total | |
| Balance at January 1, 2026 | 36,337,370 | 4,456 | 17,880,252 | 54,222,078 |
| Balance at September 30, 2026 | 36,337,370 | 4,456 | 17,880,252 | 54,222,078 |
There were no changes in retained earnings reserves during the third quarter of 2025 and 2026.
13.3.1 Tax incentives
The tax incentives recognized by the Company in its net equity, under profit reserves, relate to industrial development programs that aim at the fostering of employment generation, increasing of regional decentralization, in addition to complementing and diversifying the industrial bases of some regions and states in Brazil. In these states, the grace periods and incentive terms are set out in normative acts issued by the respective states, and when there are conditions for obtaining these grants, they are under the Company’s control. The tax treatment of States incentives complies with the provisions of current federal, state, and municipal legislation, particularly Complementary Federal Law No. 160/2017 and CONFAZ Agreement No. 190/2017. Following the revocation of Article 30 of Federal Law No. 12,973/14 by Federal Law No. 14,789/23, the state tax incentives in the form of presumed ICMS credits have ceased to be allocated to the tax incentive reserve, starting from 2024. The other federal and state tax incentives continue to be recognized in the reserve.
AMBEV S.A. |
13.3.2 Interest on capital/dividends
| Event | Approval | Type | Date of payment | Year | Type of share | Amount per share | Total amount |
| Board of Directors’ Meeting | 05/04/2026 | Interest on capital | until 12/31/2026 | 2026 | ON | 0.0449 | 694,639 |
| Board of Directors’ Meeting | 07/29/2026 | Interest on capital | until 12/31/2026 | 2026 | ON | 0.0713 | 1,099,198 |
| 1,793,837 |
Distribution of Interest on Capital (IOC) – May 2026 Resolution: At a meeting held on May 4, 2026, the Board of Directors approved the distribution of interest on capital ("IOC"), in the gross amount of R$0.0449 per Company share, corresponding to a net amount of R$0.0370 per share after withholding income tax in accordance with applicable legislation ("May 2026 IOC"). The May 2026 IOC will not be offset against the mandatory minimum dividend for the fiscal year and was calculated based on the profit for the period and the available balances reflected in the interim balance sheet as of March 31, 2026. The distribution of the May 2026 IOC will be subject to taxation in accordance with the applicable legislation. The payment will be made by December 31, 2026, on a date to be determined by the Company's Management.
Distribution of Interest on Capital (IOC) – July 2026 Resolution: At a meeting held on July 29, 2026, the Board of Directors approved the distribution of interest on capital (IOC) in the gross amount of R$0.0713 per Company share, corresponding to a net amount of R$0.0588 per share after the withholding of income tax in accordance with the applicable legislation (“July 2026 IOC”). The July 2026 IOC will be offset against the mandatory minimum dividend for the fiscal year and was calculated based on the profit for the period and the available balances reflected in the special balance sheet as of June 30, 2026. The distribution of the July 2026 IOC will be taxed in accordance with the applicable legislation. Payment will be made by December 31, 2026, on a date to be determined by the Company's Management.
AMBEV S.A. |
13.4 Carrying value adjustments
| Carrying value adjustments | ||||||||
| Translation reserves | Cash flow hedge | Actuarial gains/ (losses) | Gains/(losses) of non-controlling interest’s share | Other movements | Business combination | Accounting adjustments for transactions between shareholders | Total | |
| Balance at January 1, 2025 | 6,121,951 | 1,248,882 | (602,521) | 74,007 | (94,246) | 156,091 | (75,461,490) | (68,557,326) |
| Gains/(losses) on cumulative translation adjustments [CTA] | (10,440,425) | - | - | - | - | - | - | (10,440,425) |
| Cash flow hedges | - | (1,514,838) | - | - | - | - | - | (1,514,838) |
| Actuarial gains/(losses) | - | - | (504) | - | - | - | - | (504) |
| Total comprehensive income | (10,440,425) | (1,514,838) | (504) | - | - | - | - | (11,955,767) |
| Gains/(losses) of controlling interest | - | - | - | 1,828 | - | - | - | 1,828 |
| Taxes on deemed dividends | - | - | - | - | (62,230) | - | - | (62,230) |
| Reversal of effects of the revaluation of property, plant and equipment based on the predecessor basis of accounting | - | - | (11,728) | - | - | - | - | (11,728) |
| Balance at September 30, 2025 | (4,318,474) | (265,956) | (614,753) | 75,835 | (156,476) | 156,091 | (75,461,490) | (80,585,223) |
| Carrying value adjustments | ||||||||
| Translation reserves | Cash flow hedge | Actuarial gains/ (losses) | Gains/(losses) of non-controlling interest’s share | Other movements | Business combination | Accounting adjustments for transactions between shareholders | Total | |
| Balance at January 1, 2026 | (2,713,332) | 350,639 | (614,411) | 85,732 | (155,909) | 156,091 | (75,473,313) | (78,364,503) |
| Gains/(losses) on cumulative translation adjustment [CTA] | (5,244,642) | - | - | - | - | - | - | (5,244,642) |
| Cash flow hedges | - | 88,315 | - | - | - | - | - | 88,315 |
| Actuarial gains/(losses) | - | - | 890 | - | - | - | - | 890 |
| Total comprehensive income | (5,244,642) | 88,315 | 890 | - | - | - | - | (5,155,437) |
| Taxes on deemed dividends | - | - | - | - | (23,917) | - | - | (23,917) |
| Balance at September 30, 2026 | (7,957,974) | 438,954 | (613,521) | 85,732 | (179,826) | 156,091 | (75,473,313) | (83,543,857) |
AMBEV S.A. |
| 14. | SEGMENT REPORTING |
| (a) | Reportable segments nine-month period ended on September 30: |
| Brazil | CAC | Latin America – South | Canada | Consolidated | ||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |
| Net sales | 37,458,940 | 35,036,473 | 7,128,390 | 8,180,388 | 12,299,787 | 12,323,230 | 7,320,852 | 7,894,743 | 64,207,969 | 63,434,834 |
| Cost of sales | (18,565,354) | (17,488,790) | (3,017,403) | (3,711,118) | (6,546,349) | (6,586,284) | (3,041,238) | (3,325,668) | (31,170,344) | (31,111,860) |
| Gross profit | 18,893,586 | 17,547,683 | 4,110,987 | 4,469,270 | 5,753,438 | 5,736,946 | 4,279,614 | 4,569,075 | 33,037,625 | 32,322,974 |
| Distribution expenses | (4,595,928) | (4,484,098) | (580,748) | (652,491) | (1,642,863) | (1,548,919) | (1,244,772) | (1,331,202) | (8,064,311) | (8,016,710) |
| Sales and marketing expenses | (3,840,925) | (3,514,447) | (512,752) | (571,257) | (1,191,152) | (1,219,905) | (860,361) | (857,130) | (6,405,190) | (6,162,739) |
| Administrative expenses | (2,912,126) | (2,713,495) | (268,367) | (331,789) | (616,247) | (680,110) | (441,715) | (544,811) | (4,238,455) | (4,270,205) |
| Other operating income/(expenses) | 2,010,843 | 1,741,445 | (11,415) | 2,871 | 34,788 | 32,197 | 14,168 | (8,331) | 2,048,384 | 1,768,182 |
| Exceptional items(i) | (18,941) | (21,100) | 66,829 | 878,202 | (82,658) | (68,305) | (2,576) | (15,896) | (37,346) | 772,901 |
| Income from operations | 9,536,509 | 8,555,988 | 2,804,534 | 3,794,806 | 2,255,306 | 2,251,904 | 1,744,358 | 1,811,705 | 16,340,707 | 16,414,403 |
| Net financial results | (1,855,039) | (2,916,360) | ||||||||
| Share of results of associates and joint ventures | 33,439 | (8,130) | ||||||||
| Income before income tax | 14,519,107 | 13,489,913 | ||||||||
| Income tax expenses | (2,792,549) | (2,030,978) | ||||||||
| Net income | 11,726,558 | 11,458,935 | ||||||||
| Acquisitions of property, plant and equipment | 1,548,349 | 2,117,829 | 374,543 | 310,522 | 383,890 | 380,126 | 172,974 | 151,821 | 2,479,756 | 2,960,298 |
AMBEV S.A. |
(continued)
| Brazil | CAC | Latin America – South | Canada | Consolidated | ||||||
| 09/30/2026 | 12/31/2025 | 09/30/2026 | 12/31/2025 | 09/30/2026 | 12/31/2025 | 09/30/2026 | 12/31/2025 | 09/30/2026 | 12/31/2025 | |
| Segment assets | 58,044,482 | 58,539,954 | 12,571,034 | 14,331,925 | 21,679,807 | 23,344,458 | 15,176,918 | 16,783,598 | 107,472,241 | 112,999,935 |
| Inter-segment eliminations | (2,264,188) | (3,067,549) | ||||||||
| Non-segmented assets (ii) | 36,366,646 | 35,154,763 | ||||||||
| Total assets | 141,574,699 | 145,087,149 | ||||||||
| Segment liabilities | 31,104,469 | 32,120,900 | 3,041,505 | 5,297,547 | 5,156,947 | 7,078,599 | 3,964,644 | 4,260,622 | 43,267,565 | 48,757,668 |
| Inter-segment eliminations | (2,263,808) | (3,067,548) | ||||||||
| Non-segmented liabilities (ii) | 100,570,942 | 99,397,029 | ||||||||
| Total liabilities | 141,574,699 | 145,087,149 | ||||||||
(i) For the CAC reportable segment, mainly reflects the effect from the sale of a subsidiary, as described in Note 1 – General Information, item 1.3.4 – Completion of the third tranche – Sale of a subsidiary.
(ii) The balance of non-segmented assets refers mainly to cash and cash equivalents, taxes, and investments. The balance of non-segmented liabilities refers primarily to equity, taxes and derivatives.
Non-current assets attributed to Brazil (the Company’s country of domicile) and to Canada amounted to R$43,885,967 and R$13,281,815, respectively, at September 30, 2026 (R$44,994,052 and R$14,793,973, respectively, at December 31, 2025). Net revenue attributable to the Company's operations in Argentina totaled R$5,585,785 for the nine-month period ended September 30, 2026 (R$5,418,145 as of September 30, 2025), and the segmented non-current assets related to the same country totaled R$10,721,591 for the same period ended September 30, 2026 (R$9,916,672 as of December 31, 2025).
AMBEV S.A. |
| (b) | Reportable segments – three-month period ended on September 30: |
| Brazil | CAC | Latin America – South | Canada | Consolidated | ||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | |
| Net sales | 12,352,737 | 11,760,326 | 2,565,666 | 2,738,890 | 4,037,528 | 3,491,946 | 2,638,639 | 2,856,100 | 21,594,570 | 20,847,262 |
| Cost of sales | (6,224,249) | (5,900,770) | (1,072,329) | (1,208,899) | (2,187,358) | (1,808,645) | (1,104,361) | (1,201,691) | (10,588,297) | (10,120,005) |
| Gross profit | 6,128,488 | 5,859,556 | 1,493,337 | 1,529,991 | 1,850,170 | 1,683,301 | 1,534,278 | 1,654,409 | 11,006,273 | 10,727,257 |
| Distribution expenses | (1,478,090) | (1,452,749) | (180,072) | (207,645) | (492,596) | (420,507) | (443,614) | (478,767) | (2,594,372) | (2,559,668) |
| Sales and marketing expenses | (1,222,973) | (1,109,528) | (175,892) | (188,627) | (392,240) | (346,717) | (276,540) | (275,034) | (2,067,645) | (1,919,906) |
| Administrative expenses | (979,591) | (893,538) | (90,076) | (94,028) | (207,699) | (194,660) | (169,042) | (172,785) | (1,446,408) | (1,355,011) |
| Other operating income/(expenses) | 665,220 | 565,861 | 1,445 | 5,771 | 13,764 | 15,815 | 2,767 | (20,318) | 683,196 | 567,129 |
| Exceptional items (i) | (7,960) | (3,801) | (13,004) | 883,026 | (21,539) | (33,908) | (480) | 159 | (42,983) | 845,476 |
| Income from operations | 3,105,094 | 2,965,801 | 1,035,738 | 1,928,488 | 749,860 | 703,324 | 647,369 | 707,664 | 5,538,061 | 6,305,277 |
| Net financial results | (312,389) | (1,085,993) | ||||||||
| Share of results of associates and joint ventures | 22,768 | (5,392) | ||||||||
| Income before income tax | 5,248,440 | 5,213,892 | ||||||||
| Income tax expenses | (882,125) | (350,172) | ||||||||
| Net income | 4,366,315 | 4,863,720 | ||||||||
(i) For the CAC reportable segment, mainly reflects the effect from the sale of a subsidiary, as described in Note 1 – General Information, item 1.3.4 – Completion of the third tranche – Sale of a subsidiary.
AMBEV S.A. |
| (c) | Additional information – by business unit – nine and three-month periods ended on September 30: |
| nine-month period ended September 30: | three-month period ended September 30: | ||||||||||||
| Brazil | Brazil | ||||||||||||
| Beer | NAB | Total | Beer | NAB | Total | ||||||||
| 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | 2026 | 2025 | ||
| Net sales | 30,889,997 | 28,667,586 | 6,568,943 | 6,368,887 | 37,458,940 | 35,036,473 | 10,138,906 | 9,677,215 | 2,213,831 | 2,083,111 | 12,352,737 | 11,760,326 | |
| Cost of sales | (15,038,684) | (13,870,464) | (3,526,670) | (3,618,326) | (18,565,354) | (17,488,790) | (4,991,756) | (4,749,679) | (1,232,493) | (1,151,091) | (6,224,249) | (5,900,770) | |
| Gross profit | 15,851,313 | 14,797,122 | 3,042,273 | 2,750,561 | 18,893,586 | 17,547,683 | 5,147,150 | 4,927,536 | 981,338 | 932,020 | 6,128,488 | 5,859,556 | |
| Distribution expenses | (3,640,105) | (3,516,969) | (955,823) | (967,129) | (4,595,928) | (4,484,098) | (1,172,329) | (1,156,559) | (305,761) | (296,190) | (1,478,090) | (1,452,749) | |
| Sales and marketing expenses | (3,470,457) | (3,162,525) | (370,468) | (351,922) | (3,840,925) | (3,514,447) | (1,098,530) | (973,582) | (124,443) | (135,946) | (1,222,973) | (1,109,528) | |
| Administrative expenses | (2,574,093) | (2,375,850) | (338,033) | (337,645) | (2,912,126) | (2,713,495) | (865,504) | (781,894) | (114,087) | (111,644) | (979,591) | (893,538) | |
| Other operating income/(expenses) | 1,685,394 | 1,387,714 | 325,449 | 353,731 | 2,010,843 | 1,741,445 | 556,526 | 467,100 | 108,694 | 98,761 | 665,220 | 565,861 | |
| Exceptional items | (18,941) | (21,100) | - | - | (18,941) | (21,100) | (7,960) | (3,801) | - | - | (7,960) | (3,801) | |
| Income from operations | 7,833,111 | 7,108,392 | 1,703,398 | 1,447,596 | 9,536,509 | 8,555,988 | 2,559,353 | 2,478,800 | 545,741 | 487,001 | 3,105,094 | 2,965,801 | |
| Net financial results | (1,495,879) | (1,511,736) | (414,172) | (539,582) | |||||||||
| Share of results of associates and joint ventures | (719) | (8,057) | 2,224 | (5,286) | |||||||||
| Income before income tax | 8,039,911 | 7,036,195 | 2,693,146 | 2,420,933 | |||||||||
| Income tax expenses | (873,181) | 23,080 | (143,798) | 313,099 | |||||||||
| Net income | 7,166,730 | 7,059,275 | 2,549,348 | 2,734,032 | |||||||||
AMBEV S.A. |
| 15. | NET SALES |
In accordance with Brazilian Federal Law No 6,404/76, the Company discloses the reconciliation between gross and net sales presented in the consolidated statement of profit or loss. The revenue figures by operational segment are disclosed in Note 14 – Segment reporting.
| Nine-month period ended: | Three-month period ended: | ||||
| 09/30/2026 | 09/30/2025 | 09/30/2026 | 09/30/2025 | ||
| Gross sales | 95,462,760 | 94,324,099 | 31,980,575 | 31,023,012 | |
| Excise duty | (20,332,294) | (19,813,613) | (6,785,319) | (6,626,253) | |
| Discounts | (10,922,497) | (11,075,652) | (3,600,686) | (3,549,497) | |
| Total | 64,207,969 | 63,434,834 | 21,594,570 | 20,847,262 | |
At September 30, 2026 the Company recognized R$1,291,806 in tax incentives (R$1,138,664 at September 30, 2025). These amounts represent government grants in the nature of effective tax collection, which were recognized in the operating net revenue.
| 16. | OTHER OPERATING INCOME/(EXPENSES) |
| Nine-month period ended: | Three-month period ended: | ||||
| 09/30/2026 | 09/30/2025 | 09/30/2026 | 09/30/2025 | ||
| Government grants and subsidized loan gains | 1,432,758 | 1,357,939 | 460,767 | 484,743 | |
| (Additions to)/reversals of provisions | (1,864) | (83,962) | (6,873) | (9,190) | |
| Gains/(losses) on disposals of property, plant and equipment, intangible assets and investments of associates | 96,129 | 71,948 | 33,574 | 9,870 | |
| Other operating income/(expenses), net | 521,361 | 422,257 | 195,728 | 81,706 | |
| Total | 2,048,384 | 1,768,182 | 683,196 | 567,129 | |
| 17. | EXCEPTIONAL ITEMS |
| Nine-month period ended: | Three-month period ended: | ||||
| 09/30/2026 | 09/30/2025 | 09/30/2026 | 09/30/2025 | ||
| Restructuring (i) | (114,730) | (111,566) | (34,064) | (38,991) | |
| Subsidiary Restructuring (ii) | 77,384 | 884,467 | (8,919) | 884,467 | |
| Total | (37,346) | 772,901 | (42,983) | 845,476 | |
(i) The restructuring expenses primarily relate to organizational realignments resulting from the Group’s operational improvements, resizing initiatives and digitalization efforts.
(ii) Effect related to the deconsolidation of balance sheet amounts, including the sale of a subsidiary, as described in Note 1 – General Information, item 1.3.4 – Completion of the third tranche – Sale of subsidiary.
AMBEV S.A. |
| 18. | FINANCIAL RESULTS |
| Nine-month period ended: | Three-month period ended: | ||||
| 09/30/2026 | 09/30/2025 | 09/30/2026 | 09/30/2025 | ||
| Finance income | |||||
| Income from cash and cash equivalents | 997,508 | 863,310 | 299,341 | 271,744 | |
| Income from debt securities | 212,898 | 126,034 | 80,349 | 45,466 | |
| Income from other receivables (i) | 612,513 | 462,012 | 247,333 | 72,506 | |
| Total finance income | 1,822,919 | 1,451,356 | 627,023 | 389,716 | |
| Finance expenses | |||||
| Interest on accounts payable present value adjustment | (990,404) | (817,359) | (342,984) | (271,889) | |
| Interest on bank debts and tax incentives | (125,241) | (129,890) | (38,143) | (42,288) | |
| Interest on provisions for disputes and litigation | (134,749) | (292,572) | (71,857) | (204,661) | |
| Interest on leases | (204,751) | (188,603) | (63,851) | (67,044) | |
| Interest on pension plans | (86,601) | (82,251) | (28,364) | (27,025) | |
| Other interest expenses (ii) | (314,155) | (363,260) | (115,361) | (106,815) | |
| Losses on hedging instruments (iii) | (912,741) | (837,827) | (207,910) | (283,148) | |
| Taxes on financial transactions | (151,954) | (217,270) | (46,111) | (97,461) | |
| Bank guarantee expenses and surety bond premiums | (264,004) | (213,178) | (78,107) | (42,771) | |
| Total finance expenses | (3,184,600) | (3,142,210) | (992,688) | (1,143,102) | |
| Effects of the application of IAS 29 (hyperinflation) | 4,239 | (45,206) | (24,096) | (18,979) | |
| Exchange differences, net (iv) | (295,605) | (1,539,439) | 151,667 | (524,053) | |
| Other financial income/(expenses) (v) | (201,992) | 359,139 | (74,295) | 210,425 | |
| Other financial results, net | (493,358) | (1,225,506) | 53,276 | (332,607) | |
| Net financial results | (1,855,039) | (2,916,360) | (312,389) | (1,085,993) | |
(i) Refers mainly to monetary adjustments on taxes to be recovered.
(ii) Includes, among others, interest related to the financing of tax payments under the 2017 Special Tax Regularization Program (“PERT”).
(iii) Refers to the forward element, which may be separated and excluded from the designation of a financial instrument as a hedging instrument, in accordance with IFRS 9- Financial Instruments.
(iv) In some jurisdictions where the Group operates, there are additional costs associated with acquiring foreign currency, used for payments to some suppliers as well as for the remittance of earnings to the parent companies.
(v) As from the fourth quarter of 2025, the other financial income and other financial expense lines, which had previously been presented separately, began to be consolidated into the line item “Other financial results, net”. The same presentation has been applied on a comparative basis.
Interest expenses are presented net of the effects of derivative financial instruments used to hedge the Company’s interest rate risk (see also Note 20- Financial instruments and risks).
| 19. | SHARE-BASED PAYMENTS |
Currently, the Company has two share-based payment programs: (i) the Stock Option Plan, approved at the Extraordinary General Meeting held on July 30, 2013 (the “Stock Option Plan”); and (ii) the Share-based Plan approved at the Extraordinary General Meeting of April 29, 2016, as amended at the Extraordinary General Meeting held on April 24, 2020 (“Share-Based Plan”). Each plan may periodically issue different programs stock options, restricted stock units (RSUs) and performance stock units (PSUs). These programs allow employees and members of senior management members, as nominated by the Board of Directors and the People Committee, to acquire shares of the Company through the exercise of stock options or to receive shares directly.
AMBEV S.A. |
19.1 Share-Based Plan
During the nine-month period, the Company granted 9,659 thousand restricted and performance shares under the Share-Based Plan (16,273 thousand in September 30, 2025), representing a fair value of approximately R$144,208 in September 30, 2026 (R$200,177 in September 30, 2025).
The total number of shares granted to employees under the Share-Based Plan, which will be delivered in the future upon the fulfilment of certain conditions, is presented below:
Restricted and performance stock units
| Thousand restricted shares | 09/30/2026 | 09/30/2025 | |
| Restricted and performance stocks outstanding at January | 100,828 | 120,417 | |
| New restricted and performance stocks during the period | 9,659 | 16,273 | |
| Restricted and performance stocks vested during the period | (8,978) | (10,990) | |
| Restricted and performance stocks forfeited during the period | (5,934) | (5,068) | |
| Restricted and performance stocks outstanding at the end of the period | 95,575 | 120,632 |
19.2 Options Plan
Stock options have neither been granted nor exercised during the periods ended September 30, 2026, and September 30, 2025. The total number of outstanding stock options is as follows:
| Thousand options | 09/30/2026 | 09/30/2025 | |
| Options outstanding at January 1 | 60,191 | 72,466 | |
| Options exercised during the period | (818) | - | |
| Options forfeited during the period | (2,256) | (1,847) | |
| Options outstanding at the end of the period | 57,117 | 70,619 |
As of September 30, 2026 the exercise prices of the outstanding options ranged from R$16.34 (R$16.34 at September 30, 2025) to R$22.40 (R$22.40 at September 30, 2025). The options have different expiration dates, with remaining exercise periods of up to 38 months. Of the 57,117 thousand outstanding options (70,619 thousand at September 30, 2025), 57,117 thousand options were vested as of September 30, 2026 (70,619 thousand at September 30, 2025).
The weighted average exercise price of the options is as follows:
| In R$ per share | 09/30/2026 | 09/30/2025 | |
| Options outstanding on January 1 | 18.91 | 18.26 | |
| Options forfeited during the period | 18.39 | 18.16 | |
| Options exercised during the period | 16.34 | - | |
| Options outstanding at the end of the period | 18.24 | 19.92 | |
| Options exercisable at the end of the period | 18.24 | 19.92 |
The Company carries out periodic share buybacks when necessary to meet demand for shares to be delivered under the plans mentioned above.
AMBEV S.A. |
19.3 Expenses related to share-based payments
The share-based payments transactions described above generated an expense of R$304,777 on September 30, 2026 (R$307,720 on September 30, 2025), which was recorded under administrative expenses.
| 20. | FINANCIAL INSTRUMENTS AND RISKS |
20.1 Categories of financial instruments
The financial instruments held by the Company and its subsidiaries are managed based on operational strategies and internal controls designed to assure liquidity, profitability, and security in transaction. Transactions involving financial instruments are regularly reviewed to assess the effectiveness of the risk exposures that management intends to cover (including foreign exchange, and interest rate risk, among others).
The table below presents the consolidated financial instruments recognized in the financial statements, classified by category:
| Financial instrument items | Note | 09/30/2026 | 12/31/2025 |
| Assets | |||
| Amortized cost | |||
| Cash and cash equivalents | 5.1 | 19,188,249 | 18,638,228 |
| Trade receivables excluding prepaid expenses | 9,395,076 | 8,987,257 | |
| Investment securities | 5.2 | 90,930 | 137,557 |
| Subtotal | 28,674,255 | 27,763,042 | |
| Fair value through profit or loss | |||
| Investment securities | 5.2 | 2,725,865 | 1,667,391 |
| Derivatives hedges | 20.2 | 691,543 | 778,116 |
| Subtotal | 3,417,408 | 2,445,507 | |
| Total assets | 32,091,663 | 30,208,549 | |
| Liabilities | |||
| Amortized cost | |||
| Trade payables | 10 | 21,406,108 | 24,055,794 |
| Interest-bearing loans and borrowing | 11 | 2,714,759 | 3,386,924 |
| Other liabilities | 3,587,363 | 3,473,785 | |
| Subtotal | 27,708,230 | 30,916,503 | |
| Fair value through profit or loss | |||
| Obligations related to the acquisition of non-controlling interest (i) | 1,252,968 | 1,154,203 | |
| Derivatives hedges | 20.2 | 895,311 | 925,401 |
| Subtotal | 2,148,279 | 2,079,604 | |
| Total liabilities | 29,856,509 | 32,996,107 |
(i) Obligations related to the acquisition of a non-controlling interest: the Company recognized a liability related to the acquisition of the remaining non-controlling interest in the operations in the Dominican Republic. This financial instrument is denominated in Dominican Pesos and refers to Tranche B. The instrument is recorded by an entity whose functional currency is the Brazilian Real. The Company designated this financial liability as a hedging instrument for a portion of its net assets located in subsidiaries whose functional currency is the Dominican Peso, so that the hedge result is recognized in the Group’s other comprehensive income, consistent with the results of the hedged items.
At September 30, 2026, and December 31, 2025, the Company did not have any financial assets measured at fair value through other comprehensive income.
20.2 Risk management
In the ordinary course of its operations, the Company is exposed to market risks arising primarily from fluctuations in foreign exchange rates, commodity prices and interest rates, as well as to credit and liquidity risks. The Company identifies, measures and monitors these risks both individually and on an integrated basis, considering their interrelationships and potential effects on its operations. Risk management strategies are defined according to the nature, magnitude and duration of the exposures and may include operational, commercial and financial measures.
AMBEV S.A. |
The management of these risks is governed by the Company’s Risk Management Policy, which establishes the applicable guidelines, responsibilities, limits and approval levels. From a financial perspective, the Policy covers: (i) transactional risks related to the business; (ii) counterparty credit risks; (iii) liquidity, financing and capital structure; and (iv) financial statement translation risks.
The source and nature of each risk are presented below, while the derivative financial instruments used for hedging purposes, the related risk management strategies and their respective accounting effects are presented in Note 20.3 - Derivative financial instruments.
20.2.1 Market risk
Market risk is the risk that changes in foreign exchange rates, interest rates and commodity prices may affect the Company’s cash flows, profit or loss, or equity. These exposures arise from recognized financial instruments and forecast transactions entered into in the ordinary course of its operations and are managed in accordance with the guidelines and limits established in the Company’s Risk Management Policy.
20.2.1.1 Foreign currency risk
The Company is exposed to foreign currency risk when it holds assets or liabilities or enters into transactions denominated in a currency other than the functional currency of the respective entity. These exposures arise primarily from purchases of raw materials, operating expenses, borrowings, investment securities, dividends and transactions between Group companies.
The exposures are monitored by currency, nature of the transaction and expected settlement date, considering both recognized balances and forecast cash flows. In accordance with its Risk Management Policy, the Company seeks to reduce the foreign exchange volatility of exposures considered relevant through operational measures and the use of derivative financial instruments for hedging purposes.
The Company is also exposed to foreign exchange fluctuations arising from the translation of the financial statements of foreign subsidiaries whose functional currencies differ from the Brazilian Real. These fluctuations affect other comprehensive income and consolidated equity.
20.2.1.2 Commodity risk
The Company is exposed to fluctuations in the prices of commodities used as raw materials and packaging materials, primarily aluminum, sugar, wheat, corn and paraxylene. These fluctuations may affect the Company’s production costs, operating margins and cash flows. The exposures are monitored based on purchase commitments and consumption forecasts, taking into account the volumes, expected purchase dates and price components of each input.
20.2.1.3 Interest rate risk
The Company is exposed to fluctuations in interest rates applicable to borrowings, cash, investment securities and other financial instruments that bear fixed or variable interest rates.
Changes in market interest rates may affect finance expenses on financial liabilities, finance income from financial assets and the fair value of certain financial instruments. Exposure may also arise from future financing or refinancing arrangements entered into on terms that differ from those prevailing as of the date of the financial statements.
AMBEV S.A. |
20.3 Derivative financial instruments and hedge accounting
The Company uses derivative financial instruments exclusively to hedge financial risks arising from its operations, in accordance with the objectives, limits and approval levels established in its Risk Management Policy. The instruments used by the Company include exchange-traded futures contracts, full deliverable forwards, non-deliverable forwards and options. The selection of the instrument takes into account the nature of the risk, the relevant currency or benchmark index, and the amount and term of the hedged exposure.
The hedge accounting relationships applied by the Company comprise:
| (i) | cash flow hedges, in which derivative financial instruments are used; and |
| (ii) | a net investment hedge, in which a non-derivative financial liability denominated in a foreign currency is used, as described in Note 20.4.1 (“CND Put”). |
The Company applies cash flow hedge accounting to certain exposures related to foreign currencies and commodity prices, and net investment hedge accounting to a portion of the foreign currency exposure arising from its net investment in a subsidiary whose functional currency is the Dominican Peso, as described in Note 20.4.1 (“CND Put”) - Level 3 financial instruments.
At the inception of each hedging relationship, the Company formally documents the hedging instrument and the hedged item, the nature of the risk being hedged, the objective of the hedging strategy, the relationship between the quantities of the hedging instrument and the hedged item, the method used to assess hedge effectiveness, and the potential sources of hedge ineffectiveness. Hedge effectiveness is assessed at the inception of the hedging relationship and prospectively throughout its term, taking into account whether an economic relationship exists between the hedging instrument and the hedged item.
In hedging relationships involving foreign currencies and commodity prices, hedge ineffectiveness may arise primarily from changes in purchase forecasts and consumption curves that result in volume or timing differences between the occurrence of the forecast transactions and the settlement of the contracted instruments. In net investment hedging relationships, hedge ineffectiveness may arise from differences between the amount of the designated instrument and the portion of the net investment being hedged.
For cash flow hedges, the effective portion recognized in other comprehensive income is limited to the lower, in absolute terms, of the cumulative change in the hedging instrument and the cumulative change in the hedged item attributable to the designated risk. Any excess of the cumulative change in the hedging instrument over the cumulative change in the hedged item represents hedge ineffectiveness and is recognized immediately in the financial result. For net investment hedges, the effective portion of the foreign exchange difference on the designated instrument is recognized in other comprehensive income, while any ineffective portion is recognized in profit or loss.
The Company measures derivative financial instruments by calculating their present value using the market curves applicable to each instrument at the respective measurement dates. For exchange-traded financial instruments, fair value is calculated based on quoted exchange prices. The following tables summarize exclusively the exposures that were identified and hedged through derivative financial instruments in accordance with the Company’s Policy, including instruments designated in hedge accounting relationships and instruments used exclusively for economic hedging, as well as the instruments’ notional amounts, their asset and liability fair values as of the reporting date, and the respective effects recognized in profit or loss and equity.
AMBEV S.A. |
Transactions protected by derivative financial instruments in accordance with the Financial Risk Management Policy
| Nine-month period ended: 09/30/2026 | Three-month period ended: 09/30/2026 | ||||||||||||||
| Fair Value | Gains/(Losses) | Gains/(Losses) | |||||||||||||
| Hedged transaction or item | Hedge accounting designation | Designated risk | Notional | Assets | Liabilities | Financial results | Operational result | Equity | Financial results | Operational result | Equity | ||||
| Forward element | Spot element | Hedge accounting effect | Forward element | Spot element | Hedge accounting effect | ||||||||||
| Planned purchases of raw materials and packaging materials | 18,489,445 | 669,583 | (881,785) | (1,055,772) | 256,713 | 346,673 | (272,719) | 132,055 | 310,387 | ||||||
| Cash flow | Commodity price component | 5,460,619 | 385,586 | (74,343) | (65,621) | 648,871 | 607,495 | 18,355 | 208,144 | 321,431 | |||||
| Cash flow | Foreign exchange component - U.S. Dollars | 13,028,826 | 283,997 | (807,442) | (990,151) | (392,158) | (260,822) | (291,074) | (76,089) | (11,045) | |||||
| Expected imports of fixed assets | 83,284 | 1,061 | (7,833) | (3,707) | (5,576) | 1,531 | 513 | (1,353) | (478) | ||||||
| Cash flow | Foreign exchange component - U.S. Dollars | 83,284 | 1,061 | (7,833) | (3,707) | (5,576) | 1,531 | 513 | (1,353) | (478) | |||||
| Expected operating expenses | 81,301 | 1,018 | (5,693) | (2,772) | (4,027) | 9,954 | 217 | (539) | 619 | ||||||
| Cash flow | Foreign exchange component - U.S. Dollars | 81,301 | 1,018 | (5,693) | (2,772) | (4,027) | 9,954 | 217 | (539) | 619 | |||||
| Financial assets | (2,201,829) | 19,881 | - | 59,280 | - | - | 35,835 | - | - | ||||||
| Not applicable (i) | Foreign exchange component - U.S. Dollars | (2,201,829) | 19,881 | - | 59,280 | - | - | 35,835 | - | - | |||||
| Balance at end of the period | 16,452,201 | 691,543 | (895,311) | (1,002,971) | 247,110 | 358,158 | (236,154) | 130,163 | 310,527 | ||||||
(i) Instruments used to economically hedge the foreign exchange exposure of financial assets denominated in U.S. dollars, not designated for hedge accounting purposes, with changes in fair value recognized in financial results.
AMBEV S.A. |
| 12/31/2025 | Nine-month period ended: 09/30/2025 | Three-month period ended: 09/30/2025 | |||||||||||||
| Fair Value | Gains/(Losses) | Gains/(Losses) | |||||||||||||
| Hedge position | Hedge accounting designation | Designated risk | Notional | Assets | Liabilities | Financial results | Operational result | Equity | Financial results | Operational result | Equity | ||||
| Forward element | Spot element | Hedge accounting effect | Forward element | Spot element | Hedge accounting effect | ||||||||||
| Planned purchases of raw materials and packaging materials | 19,317,767 | 749,013 | (889,212) | (846,716) | 788,474 | (1,186,789) | (294,137) | 94,735 | (114,272) | ||||||
| Cash flow | Commodity price component | 5,280,603 | 620,734 | (108,720) | (77,799) | (34,015) | 192,802 | (32,405) | 8,453 | 124,731 | |||||
| Cash flow | Foreign exchange component - U.S. Dollars | 14,037,164 | 128,279 | (780,492) | (768,917) | 822,489 | (1,379,591) | (261,732) | 86,282 | (239,003) | |||||
| Expected imports of fixed assets | 117,977 | 143 | (11,449) | (1,996) | 2,395 | (7,326) | (1,430) | (142) | (95) | ||||||
| Cash flow | Foreign exchange component - U.S. Dollars | 117,977 | 143 | (11,449) | (1,996) | 2,395 | (7,326) | (1,430) | (142) | (95) | |||||
| Expected operating expenses | 92,349 | 427 | (8,098) | (1,425) | 3,979 | 1,822 | (1,066) | 2,799 | 5,713 | ||||||
| Cash flow | Foreign exchange component - U.S. Dollars | 92,349 | 427 | (8,098) | (1,425) | 3,979 | 1,822 | (1,066) | 2,799 | 5,713 | |||||
| Financial assets | - | 28,533 | (16,642) | - | - | - | - | - | - | ||||||
| Not applicable (i) | Foreign exchange component - U.S. Dollars | - | 28,533 | (16,642) | - | - | - | - | - | - | |||||
| Balance at end of the period | 19,528,093 | 778,116 | (925,401) | (850,137) | 794,848 | (1,192,293) | (296,633) | 97,392 | (108,654) | ||||||
(i) Instruments used to economically hedge the foreign exchange exposure of financial assets denominated in U.S. dollars, not designated for hedge accounting purposes, with changes in fair value recognized in financial results.
As disclosed in the Company’s accounting policies, the forward element, which may be separated and excluded from hedge designation, is recognized in the financial result in accordance with IFRS 9 - Financial Instruments.
AMBEV S.A. |
20.3.1 Instrument maturity
At September 30, 2026, the Notional and Fair Value amounts, by instrument and maturity, were as follow:
| Notional Value | ||||
| Hedge position | Risk | 2026 | 2027 | Total |
| Forecast purchases of raw materials and packaging materials. | 8,275,568 | 10,213,877 | 18,489,445 | |
| Commodity price component | 1,401,312 | 4,059,307 | 5,460,619 | |
| Foreign exchange component - U.S. Dollars | 6,874,256 | 6,154,570 | 13,028,826 | |
| Expected imports of fixed assets | 27,390 | 55,894 | 83,284 | |
| Foreign exchange component - U.S. Dollars | 27,390 | 55,894 | 83,284 | |
| Expected operating expenses | 16,938 | 64,363 | 81,301 | |
| Foreign exchange component - U.S. Dollars | 16,938 | 64,363 | 81,301 | |
| Financial assets | (2,201,829) | - | (2,201,829) | |
| Foreign exchange component - U.S. Dollars | (2,201,829) | - | (2,201,829) | |
| 6,118,067 | 10,334,134 | 16,452,201 | ||
| Fair Value | ||||
| Hedge position | Risk | 2026 | 2027 | Total |
| Forecast purchases of raw materials and packaging materials. | (159,416) | (52,786) | (212,202) | |
| Commodity price component | 266,910 | 44,333 | 311,243 | |
| Foreign exchange component - U.S. Dollars | (426,326) | (97,119) | (523,445) | |
| Expected imports of fixed assets | (4,104) | (2,668) | (6,772) | |
| Foreign exchange component - U.S. Dollars | (4,104) | (2,668) | (6,772) | |
| Expected operating expenses | (2,996) | (1,679) | (4,675) | |
| Foreign exchange component - U.S. Dollars | (2,996) | (1,679) | (4,675) | |
| Financial assets | 19,881 | - | 19,881 | |
| Foreign exchange component - U.S. Dollars | 19,881 | - | 19,881 | |
| (146,635) | (57,133) | (203,768) | ||
20.3.2 Margins pledged as guarantees
To comply with margin requirements established by derivative exchanges and/or counterparties to certain derivative financial instrument transactions, at September 30, 2026, the Group held R$227,045 financial investments with high liquidity or in cash, classified as cash and cash equivalents and investment securities (R$164,400 at December 31, 2025).
AMBEV S.A. |
20.4 Classification of financial instruments
| 09/30/2026 | 12/31/2025 | ||||||||
| Level 1 | Level 2 | Level 3 | Total | Level 1 | Level 2 | Level 3 | Total | ||
| Financial assets | |||||||||
| Investment securities | 2,725,865 | - | - | 2,725,865 | 1,667,391 | - | - | 1,667,391 | |
| Derivatives assets at fair value through profit and loss | 19,881 | - | - | 19,881 | 7,850 | 20,683 | - | 28,533 | |
| Derivatives – operational hedges | 195,742 | 475,920 | - | 671,662 | 164,266 | 585,317 | - | 749,583 | |
| 2,941,488 | 475,920 | - | 3,417,408 | 1,839,507 | 606,000 | - | 2,445,507 | ||
| Financial liabilities | |||||||||
| Put options granted on subsidiaries | - | - | 1,252,968 | 1,252,968 | - | - | 1,154,203 | 1,154,203 | |
| Derivatives liabilities at fair value through profit and loss | - | - | - | - | - | 16,642 | - | 16,642 | |
| Derivatives – operational hedges | 45,778 | 849,533 | - | 895,311 | 97,982 | 810,777 | - | 908,759 | |
| 45,778 | 849,533 | 1,252,968 | 2,148,279 | 97,982 | 827,419 | 1,154,203 | 2,079,604 | ||
There were no transfers of assets and liabilities among fair value hierarchy Levels 1, 2, and 3 during the periods presented.
20.4.1 Financial instruments level 3
PUT CND
In accordance with the Shareholders' Agreement of Tenedora CND S.A. ("Tenedora”) – holding company headquartered in the Dominican Republic which owns almost the entire share capital of CND – executed between the Company and E. León Jimenes, S.A. (“ELJ”), ELJ is the owner of 2.89% of the shares of Tenedora, and has a put option for such remaining interest, corresponding to Tranche B as provided in the Agreement. This put option may be exercised by ELJ starting as from 2026. The Company, in turn, also holds a call option to acquire the Tranche B shares, exercisable from 2029 onwards, at which point both options will coexist.
At September 30, 2026, the Tranche B shares held by ELJ were valued at R$1,252,968 (R$1,154,203 at December 31, 2025). The fair value of Tranche B was calculated based on the EBITDA multiple defined in the agreement, less net debt, and discounted to present value using standard valuation techniques, based on the present value of the principal and future interest, discounted using the local currency WACC as of the measurement date. The valuation inputs are based on market information from reliable sources and are classified within Level 3 of the fair value hierarchy.
20.4.2 Reconciliation of changes in the liabilities categorized at Level 3
| Financial liabilities at December 31, 2025 | 1,154,203 |
| Total gains and losses during the period | 98,765 |
| Losses/(gains) recognized in net income | 106,569 |
| Losses/(gains) recognized in equity (i) | (7,804) |
| Financial liabilities at September 30, 2026 | 1,252,968 |
(i) Effect of foreign exchange variation on the Net Investment Hedge (NIH) instrument.
The table below demonstrates the exposure of the Company and its subsidiaries to debts and respective weighted interest rates. As of September 30, 2026, the Company and its subsidiaries did not hold hedge positions to the exposure described below:
AMBEV S.A. |
| 09/30/2026 | 12/31/2025 | ||||
| Risk | Risk | ||||
| Interest rate | Amount in Brazilian Real | Interest rate | Amount in Brazilian Real | ||
| Brazilian Reais | 12.1% | 1,659,383 | 11.1% | 2,172,861 | |
| Other | 13.7% | 535,064 | 15.1% | 628,508 | |
| US Dollars | 7.3% | 124 | 2.4% | 9,750 | |
| Canadian Dollars | 5.3% | 253,909 | 5.5% | 314,790 | |
| Pre-fixed interest rate | 2,448,480 | 3,125,909 | |||
| Brazilian Reais | 7.2% | 266,279 | 7.6% | 261,015 | |
| Post - fixed interest rate | 266,279 | 261,015 | |||
20.5 Credit risk
The financial institutions authorized to act as counterparties to the Company are determined in accordance with the Company’s Credit Risk Policy. The Credit Risk Policy establishes maximum exposure limits for each counterparty based on its credit rating and capitalization.
Deposits or cash positions, if any, must be maintained in accounts with first-tier banks or banks with high credit ratings in each country. Any short-term position with a maturity of less than six months must be treated as a deposit or cash position.
Counterparty risk must be managed by the Company on a global basis, with product-specific limits established by Treasury, taking into account: (i) the counterparty’s credit rating; (ii) duration; (iii) amount; and (iv) the allocation between assets and liabilities, in the absence of netting provisions in the respective derivative contracts.
The carrying amounts of cash and cash equivalents, investment securities, trade receivables excluding advance payments, recoverable taxes and derivative financial instruments are presented net of any recognized impairment provisions and represent the Company’s maximum exposure to credit risk as of September 30, 2026. As of September 30, 2026, there was no concentration of credit risk with any counterparty in excess of the limits established by the Company’s Credit Risk Policy. Counterparty credit risk is reassessed quarterly.
Customers
A substantial portion of the Company’s sales is made to distributors, supermarkets and retailers through a broad distribution network. Credit risk is mitigated by the broad diversification of the Company’s customer portfolio and by the control procedures implemented to monitor such risk. Historically, the Company has not incurred significant losses on trade receivables.
Investments
To minimize the credit risk associated with its investments, the Company has adopted cash and investment allocation policies that take into account exposure limits and the credit assessments of financial institutions, thereby avoiding credit concentration. Accordingly, credit risk is monitored and mitigated by restricting transactions to a select group of highly rated counterparties.
20.6 Liquidity risk
Historically, the Company’s primary sources of liquidity have been cash flows from operating activities, debt issuances and bank borrowings. The Company’s principal cash requirements include the payment of dividends and interest on capital, capital expenditures, investments in companies, increases in ownership interests in subsidiaries or other companies in which it holds equity interests, share buyback programs and debt service.
The Company believes that its cash flow from operating activities, cash and cash equivalents and short-term financial investments, together with derivatives financial instruments and access to credit facilities, are sufficient to finance its capital expenditure, financial liabilities and dividend payments in the future.
AMBEV S.A. |
| 09/30/2026 | |||||||
| Carrying amount | Contractual cash flow | Less than 1 year | 1-2 years | 2-3 years | 3-5 years | More than 5 years | |
| Trade and other payables (i) | 34,204,520 | 36,124,034 | 34,099,223 | 94,167 | 49,525 | 8,214 | 1,872,905 |
| Secured bank loans | 80,871 | 100,728 | 25,182 | 25,182 | 25,182 | 25,182 | - |
| Other secured loans | 272,794 | 337,950 | 129,077 | 95,258 | 63,744 | 6,900 | 42,971 |
| Lease liabilities | 2,361,094 | 3,065,145 | 1,103,043 | 792,511 | 367,574 | 374,815 | 427,202 |
| 36,919,279 | 39,627,857 | 35,356,525 | 1,007,118 | 506,025 | 415,111 | 2,343,078 |
| 12/31/2025 | |||||||
| Carrying amount | Contractual cash flow | Less than 1 year | 1-2 years | 2-3 years | 3-5 years | More than 5 years | |
| Trade and other payables (i) | 38,793,549 | 40,657,985 | 37,499,850 | 85,522 | 40,675 | 1,169,439 | 1,862,499 |
| Secured bank loans | 99,701 | 126,861 | 27,943 | 25,182 | 23,373 | 50,363 | - |
| Other secured loans | 311,577 | 405,106 | 146,216 | 131,495 | 65,261 | 8,253 | 53,881 |
| Lease liabilities | 2,975,646 | 3,837,785 | 1,229,439 | 946,023 | 688,200 | 441,695 | 532,428 |
| 42,180,473 | 45,027,737 | 38,903,448 | 1,188,222 | 817,509 | 1,669,750 | 2,448,808 |
(i) Mainly includes amounts related to suppliers, taxes, fees and contributions payables, dividends and interest on equity payable, salaries and related charges, put options related to the Company’s ownership interests in subsidiaries and other liabilities, except for transactions with related parties.
AMBEV S.A. |
20.7 Capital management
The Company continuously evaluates and optimizes its capital structure in order to maximize shareholder value while maintaining the desired financial flexibility to execute its strategic projects. In addition to the statutory minimum equity funding requirements applicable to the Company’s subsidiaries in different countries, the Company is not subject to any externally imposed capital requirements. When analyzing its capital structure, the Company uses the same debt ratios and capital classifications that are applied in the financial statements.
The company monitors its net debt to ensure the continuity of its operations over the long term.
| 09/30/2026 | 12/31/2025 | ||
| Debt details | |||
| Interest-bearing loans and borrowing current and non-current | 2,714,759 | 3,386,924 | |
| (-) Current investment securities | (2,725,865) | (1,681,692) | |
| (-) Cash and cash equivalents | (19,188,249) | (18,638,228) | |
| Net debt/(cash) | (19,199,355) | (16,932,996) | |
| 21. | COLLATERAL, CONTRACTUAL COMMITMENTS TO SUPPLIERS, ADVANCES FROM CUSTOMERS AND OTHERS |
| 09/30/2026 | 12/31/2025 | |
| Collateral given for the Company’s own liabilities | 708,337 | 775,755 |
| Other commitments | 932,056 | 491,142 |
| 1,640,393 | 1,266,897 | |
| Commitments to suppliers - Property, plant and equipment and Intangibles | 563,782 | 251,074 |
| Commitments to suppliers - Inventory | 23,224,564 | 25,020,120 |
| 23,788,346 | 25,271,194 |
At September 30, 2026, the Company had R$708,337 (R$775,755 at December 31, 2025) of cash guarantees.
Most of the commitments balance relates to obligations to packaging suppliers. These commitments are primarily aimed at ensuring a secure long-term supply of the Company’s strategic inputs and providing greater assurance to suppliers making long-term investments. The future contractual commitments are presented below:
| 09/30/2026 | 12/31/2025 | |
| Less than 1 year | 10,895,262 | 12,895,064 |
| Between 1 and 2 years | 4,155,164 | 2,151,696 |
| More than 2 years | 8,737,920 | 10,224,434 |
| 23,788,346 | 25,271,194 |
Cash deposits used as guarantees are classified within other assets. The amount of fixed assets pledged as collateral is not material.
AMBEV S.A. |
| 22. | RELATED PARTIES |
The Company adopts corporate governance practices as recommended and/or required by the applicable laws and regulations. Under the Company’s bylaws, the Board of Directors is responsible for approving any transactions or agreements entered into between the Company and/or any of its subsidiaries (except wholly owned subsidiaries), its directors and/or shareholders (including direct or indirect partners of the Company’s shareholders). The Company's Governance Committee is responsible for advising the Board of Directors on matters related to related party transactions, among others.
Members of management are prohibited from taking part in any transaction in which a conflict of interest with the Company may exist, even if only in theory. This restriction also applies to any decision made by other members of management regarding the matter. Whenever such conflict exists, the members involved must inform management of the conflict and ensure that their non-participation in the deliberation is recorded in the minutes of the Board of Directors’ or Executive Board’s meeting.
22.1 Transactions with key management personnel
Key management personnel comprise the members of Executive Board and the Board of Directors. In addition to short-term benefits (mainly salaries), key management personnel are eligible to participate in the Company’s share-based payment plans, as described in note 19 – Share-based payments.
The total remuneration of key management personnel is presented below:
| Nine-month period ended: | Three-month period ended: | ||||
| 09/30/2026 | 09/30/2025 | 09/30/2026 | 09/30/2025 | ||
| Short-term benefits (i) | 33,837 | 36,316 | 11,437 | 10,976 | |
| Share-based payments (ii) | 73,316 | 96,073 | 33,748 | 31,973 | |
| Taxes | 7,799 | 4,553 | 3,729 | 1,523 | |
| Total key Management remuneration | 114,952 | 136,942 | 48,914 | 44,472 | |
(i) Mainly comprise fixed and variable compensation (including performance bonuses) paid to management.
(ii) Reflects expenses related to share options, deferred shares, restricted stocks and performance shares granted to Management.
Except for the above mentioned remuneration, the Company has no other transaction with key management personnel, nor does it have outstanding balances receivable from or payable to them in the Company’s balance sheet.
22.2 Transactions with the Company's shareholders:
22.2.1 Medical, dental and other benefits
Fundação Zerrenner is one of Ambev’s shareholders, holding 10.4% of its share capital. Fundação Zerrenner is also an independent legal entity whose main goal is to provide Ambev’s employees, both active and retired, with healthcare and dental assistance, support for technical and higher education courses, and facilities for assisting elderly people, either directly or through financial assistance agreements with other entities. At September 30, 2026, and December 31, 2025, the actuarial obligations related to the benefits provided directly by Fundação Zerrenner were fully covered by plan assets held for this purpose, which significantly exceeded the corresponding liabilities at those dates.
Ambev recognizes the assets (recorded as prepaid expenses) to the extent of the economic benefits that are available to the Company, arising from reimbursements or reductions in future contributions.
AMBEV S.A. |
During the nine-month period ended September 30, 2026, expenses incurred and recognized by Fundação Zerrenner with third parties to provide these benefits amounted to R$307,988 (R$277,887 at September 30, 2025), of which R$276,077 and R$31,911 related to active employees and retirees, respectively (R$245,981 and R$31,906 at September 30, 2025).
22.2.2 Licensing agreement with AB InBev
The Company maintains licensing agreement with AB InBev and certain of its subsidiaries, including as Group Modelo and Spaten-Franziskaner-Bräu GmbH, to produce, bottle, import, promote, sell and distribute their key brands in the territories where the Group operates. The Company also grants AB InBev and certain of its subsidiaries licenses granting similar rights over its key brands, such as Brahma®, in AB Inbev’s territories.
During the nine-month period ended September 30, 2026, the Group recognized R$47,364 (R$49,129 at September 30, 2025) and R$1,052,331 (R$962,973 at September 30, 2025) as royalty income and expenses, respectively, in its consolidated results.
22.3 Transactions with related parties
The Group’s consolidated results include R$548,995 from sales of products, services rendered and other income in the nine-month period ended September 30, 2026 (R$570,971 in September 30, 2025). Regarding product purchases and other expenses, the Group recognized, in the same nine-month period ended September 30, 2026, the amount to R$2,237,170 (R$(2,192,001) in September 30, 2025). Additionally, an amount to R$(10,198) was recognized by the Group as part of the net financial result from Transactions with related parties for the nine-month period ended September 30, 2026 (R$(10,995) on September 30, 2025). The Group's main related party transactions were conducted with the following companies: Anheuser-Busch Packaging Group Inc., Anheuser-Busch Inbev USA LLC, Bavaria S.A., Cervecería Modelo de Mexico S. de R.L. de C.V., Anheuser-Busch Inbev Services LLC, Anheuser-Busch InBev N.V. among others.
| 23. | EVENTS AFTER THE REPORTING PERIOD |
23.1 Share Buyback Program
In a meeting held on October 28, 2026, the Board of Directors approved, pursuant to article 30, Paragraph 1st, “b”, of Law 6,404/76 and CVM Resolution 77/2022, a share buyback program for the repurchase of shares issued by the Company up to the limit of 190,000,000 common shares (“Program”), with the primary purpose of cancelation of such shares. Any remaining shares may be held in treasury, transferred and/or delivered under Company’s share-based compensation plans. The Program will remain in effect until April 28, 2028, as further detailed, together with the other information relating thereto, in the Notice Regarding the Negotiation of Shares Issued by the Company, prepared pursuant to Annex G of CVM Resolution No. 80/2022 and disclosed on the date of approval.
AMBEV S.A. |
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned, thereunto duly authorized.
Date: October 29, 2026
| AMBEV S.A. | ||
| By: | /s/ Guilherme Fleury de Figueiredo Ferraz Parolari | |
|
Guilherme Fleury de Figueiredo Ferraz Parolari Chief Financial and Investor Relations Officer | ||