Table of Contents
As filed with the Securities and Exchange Commission on August 21, 2026.
Registration No. 333-
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM S-1
REGISTRATION STATEMENT
UNDER
THE SECURITIES ACT OF 1933
CoVolt Power, Inc.
(Exact name of registrant as specified in its charter)
| Texas | 4931 | 42-2230361 | ||
| (State or other jurisdiction of incorporation or organization) | (Primary Standard Industrial Classification Code Number) | (I.R.S. Employer Identification No.) |
711 Louisiana Street
Suite ST 2500
Houston, TX 77002
(713) 267-5567
(Address, including zip code, and telephone number, including area code, of registrant’s principal executive offices)
Samuel K. Robison
711 Louisiana Street
Suite ST 2500
Houston, TX 77002
(713) 267-5567
(Name, address, including zip code, and telephone number, including area code, of agent for service)
Copies to:
| Ryan J. Maierson John J. Slater Latham & Watkins LLP 811 Main Street, Suite 3700 Houston, Texas 77002 (713) 546-5400 |
Sarah K. Morgan Jackson A. O’Maley Vinson & Elkins L.L.P. 845 Texas Avenue, Suite 4700 Houston, Texas 77002 (713) 758-2222 |
APPROXIMATE DATE OF COMMENCEMENT OF PROPOSED SALE TO THE PUBLIC: AS SOON AS PRACTICABLE AFTER THIS REGISTRATION STATEMENT IS DECLARED EFFECTIVE.
If any of the securities being registered on this form are to be offered on a delayed or continuous basis pursuant to Rule 415 under the Securities Act of 1933, check the following box. ☐
If this form is filed to register additional securities for an offering pursuant to Rule 462(b) under the Securities Act, check the following box and list the Securities Act registration statement number of the earlier effective registration statement for the same offering. ☐
If this form is a post-effective amendment filed pursuant to Rule 462(c) under the Securities Act, check the following box and list the Securities Act registration statement number of the earlier effective registration statement for the same offering. ☐
If this form is a post-effective amendment filed pursuant to Rule 462(d) under the Securities Act, check the following box and list the Securities Act registration statement number of the earlier effective registration statement for the same offering. ☐
Indicate by check mark whether the registrant is a large accelerated filer, an accelerated filer, a non-accelerated filer, a smaller reporting company, or an emerging growth company. See the definitions of “large accelerated filer,” “accelerated filer,” “smaller reporting company” and “emerging growth company” in Rule 12b-2 of the Exchange Act.
| Large accelerated filer | ☐ | Accelerated filer | ☐ | |||
| Non-accelerated filer | ☒ | Smaller reporting company | ☐ | |||
| Emerging growth company | ☒ | |||||
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 7(a)(2)(B) of the Securities Act. ☐
The Registrant hereby amends this Registration Statement on such date or dates as may be necessary to delay its effective date until the Registrant shall file a further amendment which specifically states that this Registration Statement shall thereafter become effective in accordance with Section 8(a) of the Securities Act of 1933 or until the Registration Statement shall become effective on such date as the Securities and Exchange Commission, acting pursuant to said Section 8(a), may determine.
Table of Contents
The information in this preliminary prospectus is not complete and may be changed. These securities may not be sold until the registration statement filed with the Securities and Exchange Commission is effective. This preliminary prospectus is not an offer to sell these securities, and it is not soliciting an offer to buy these securities in any jurisdiction where the offer or sale is not permitted.
Subject to Completion. Dated , 2026.
Shares
CoVolt Power, Inc.
Class A Common Stock
This is an initial public offering of shares of our Class A common stock of CoVolt Power, Inc. We are offering shares of our Class A common stock. The selling shareholders identified in this prospectus are offering an additional shares of our Class A common stock. We will not receive any of the proceeds from the sale of the shares being sold by the selling shareholders.
Prior to this offering, there has been no public market for our Class A common stock. It is currently estimated that the initial public offering price per share of our Class A common stock will be between $ and $ . We have applied to list our Class A common stock on the NYSE under the symbol “KVLT.”
We will have two classes of common stock: Class A common stock, par value $0.001 per share, and Class B common stock, par value $0.001 per share. Holders of our Class A common stock and Class B common stock will be entitled to one vote for each share of Class A common stock and Class B common stock, respectively, held of record on all matters on which shareholders are entitled to vote generally. See “Description of Capital Stock.” Upon consummation of this offering, our Continuing Equity Owners (as defined herein) will hold 100% of the shares of Class B common stock that will entitle them to % of the combined voting power of our common stock (or % if the underwriters exercise their option to purchase additional shares of Class A common stock in full). In connection with the consummation of this offering, we will be a holding company in an organizational structure commonly referred to as an umbrella partnership-C-corporation (or “Up-C”) structure. Our sole material asset will be our equity interest in CoVolt Holdings Group, LLC (“CoVolt Holdings”) which, through its direct and indirect subsidiaries, conducts all of our operations. Because CoVolt Power, Inc. will be the sole managing member of CoVolt Holdings, we will indirectly operate and control all of the business and affairs (and will consolidate the financial results) of CoVolt Holdings and its subsidiaries. See “Risk Factors–Risks Related to Our Capital Structure.”
We are an “emerging growth company,” as defined under the federal securities laws, and, as such, may elect to comply with certain reduced public company reporting requirements. See “Prospectus Summary–Implications of Being an Emerging Growth Company.”
After the completion of this offering, certain of our Continuing Equity Owners will collectively hold a majority of the combined voting power of our shares eligible to vote for the election of our directors. As a result, we will be a “controlled company” within the meaning of the NYSE corporate governance standards. See “Management–Controlled Company Exception” and “Principal and Selling Shareholders.”
Investing in our Class A common stock involves risks. See “Risk Factors” beginning on page 27 to read about factors you should consider before buying shares of our Class A common stock.
| Per Share | Total | |||||||
| Initial public offering price |
$ | $ | ||||||
| Underwriting discounts and commissions(1) |
$ | $ | ||||||
| Proceeds, before expenses, to us |
$ | $ | ||||||
| Proceeds, before expenses, to the selling shareholders |
$ | $ | ||||||
| (1) | See the section titled “Underwriting” for a description of the compensation payable to the underwriters. |
The selling shareholders have granted the underwriters an option for a period of 30 days from the date of this prospectus to purchase up to an additional shares of our Class A common stock from the selling shareholders at the initial public offering price, less the underwriting discounts and commissions.
Neither the Securities and Exchange Commission nor any state securities commission or any other regulatory body has approved or disapproved of these securities or passed upon the accuracy or adequacy of this prospectus. Any representation to the contrary is a criminal offense.
At our request, the underwriters have reserved up to % of the Class A common stock offered by this prospectus for sale, at the initial public offering price, to certain individuals associated with us and our shareholders. See “Underwriting–Directed Share Program.”
The underwriters expect to deliver the shares of our Class A common stock against payment on , 2026.
| J.P. Morgan | Jefferies |
| RBC Capital Markets | UBS Investment Bank |
| KeyBanc Capital Markets | Wolfe | Nomura Alliance | |
| Baird | Needham & Company | Roth Capital Partners | ||
Prospectus dated , 2026.
Table of Contents
Table of Contents
Table of Contents
Table of Contents
Table of Contents
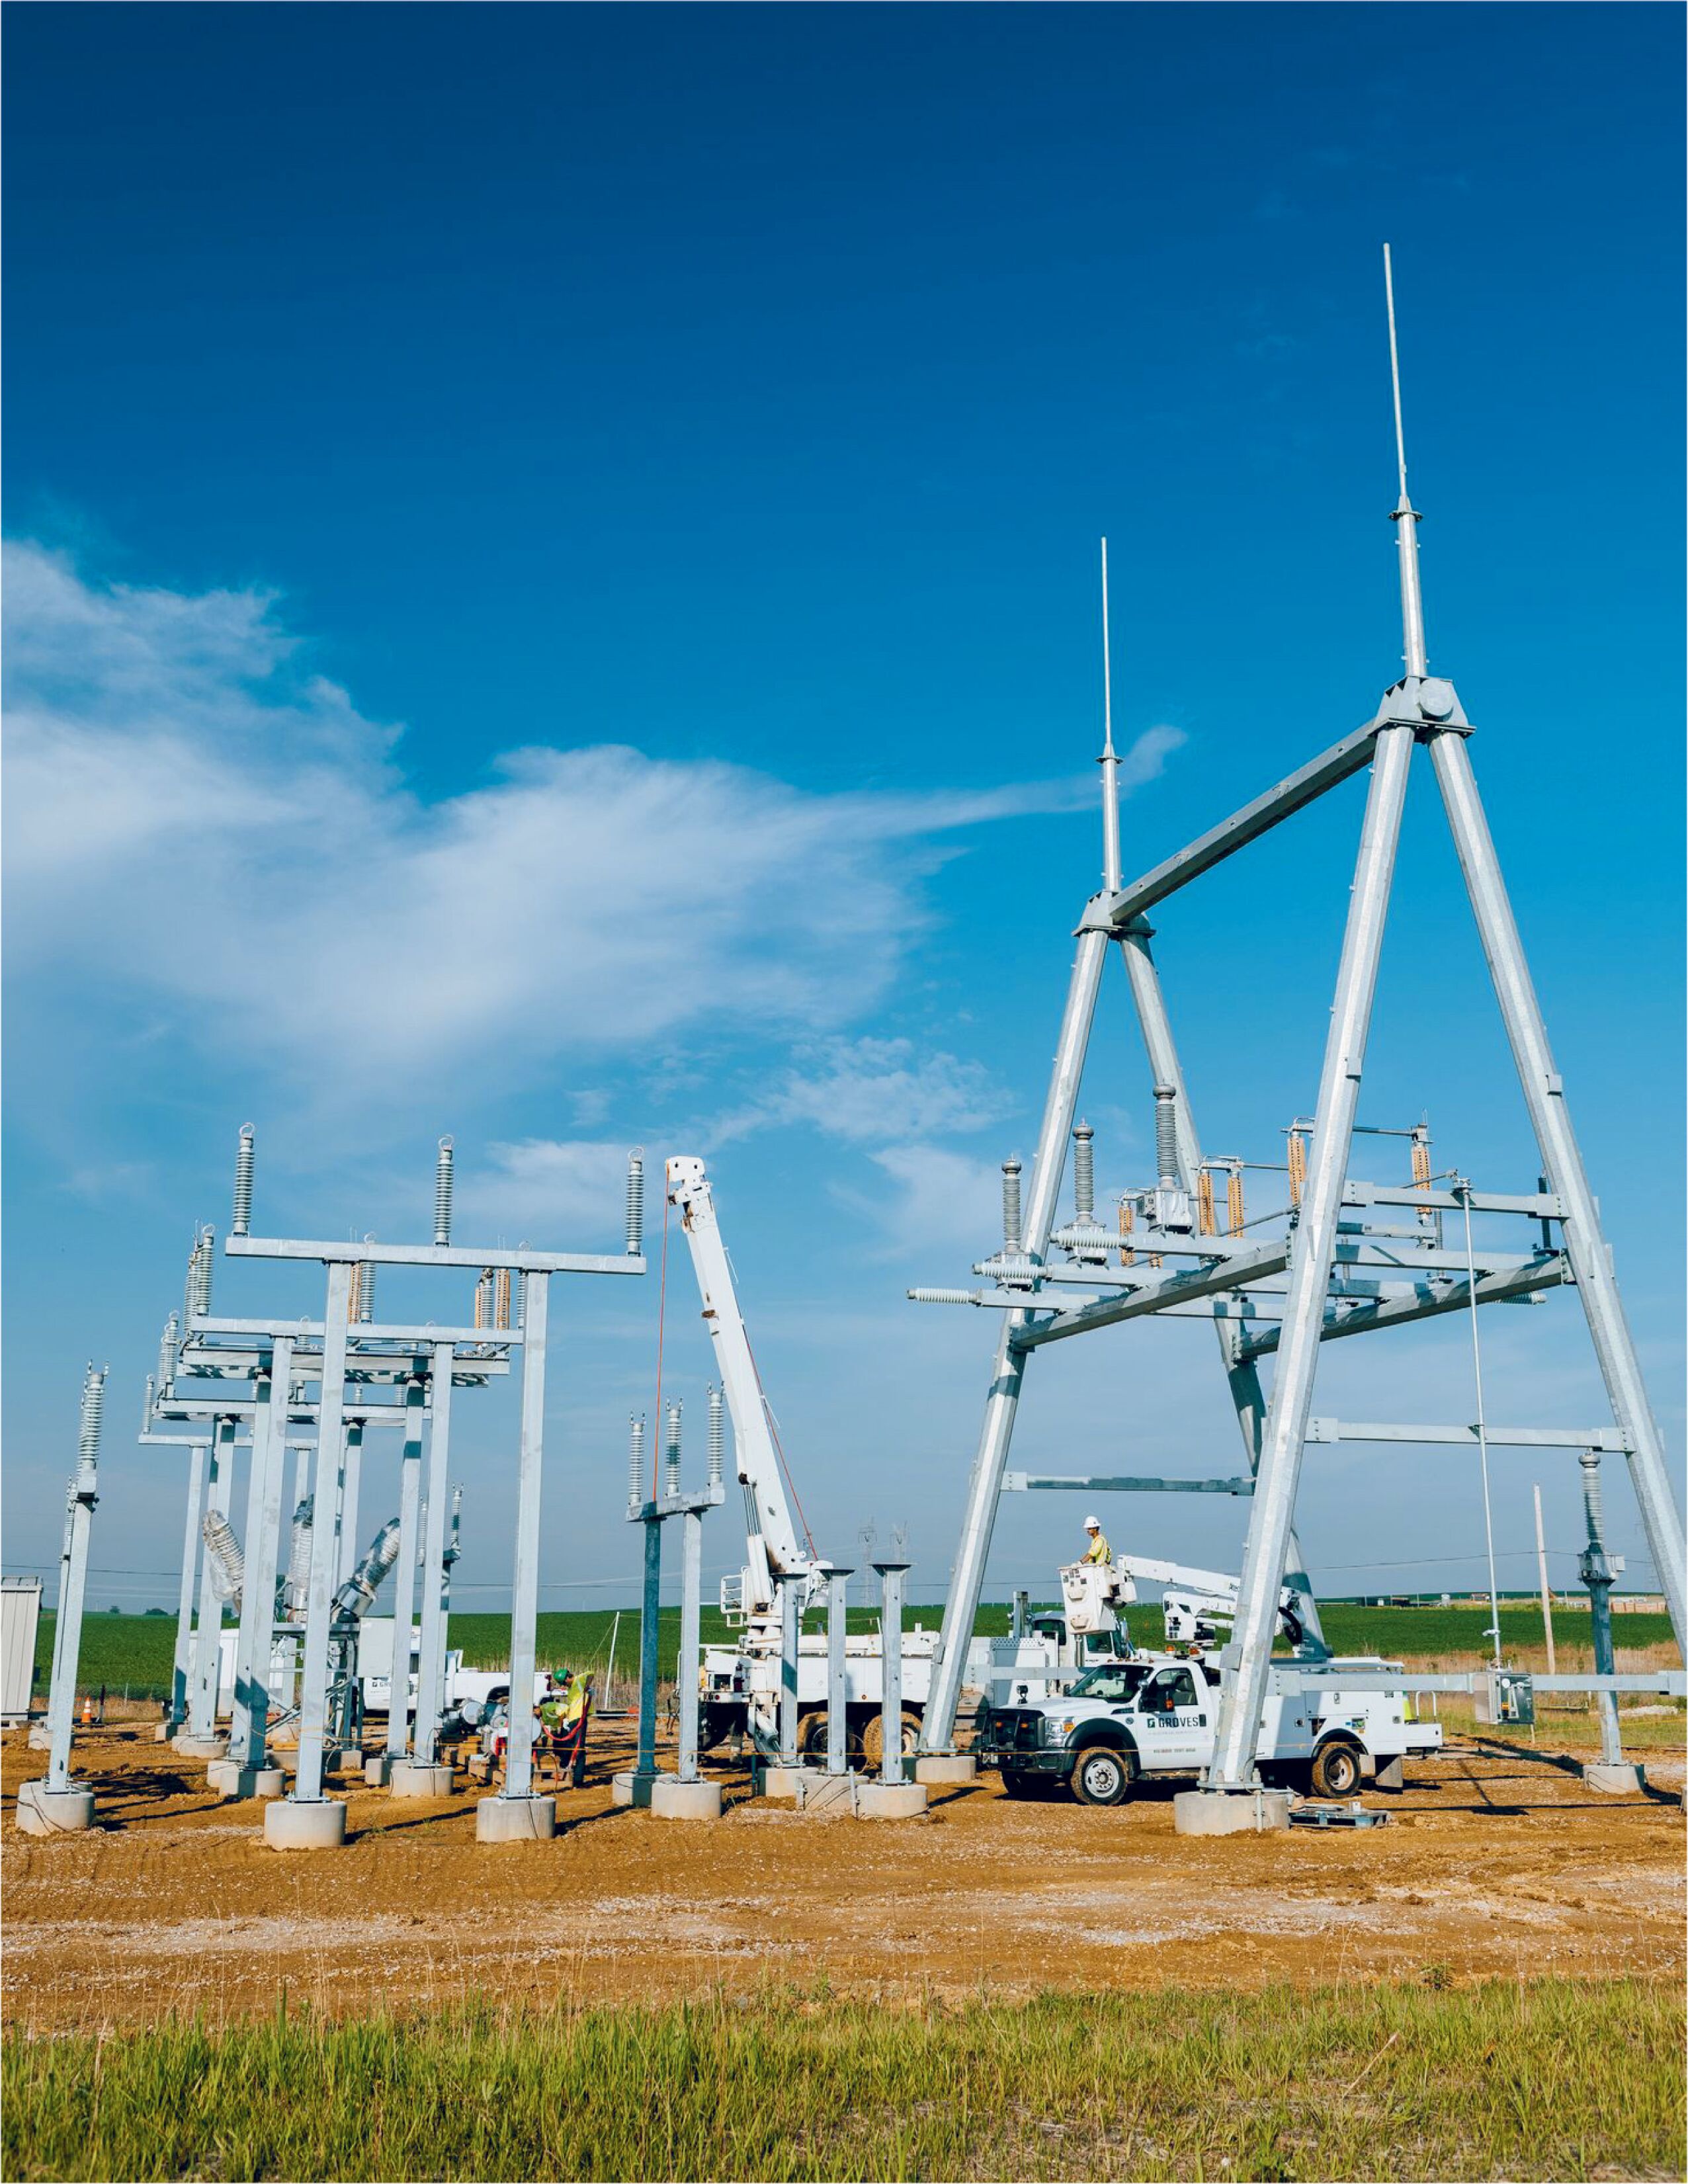
Table of Contents
Table of Contents
Table of Contents
Table of Contents
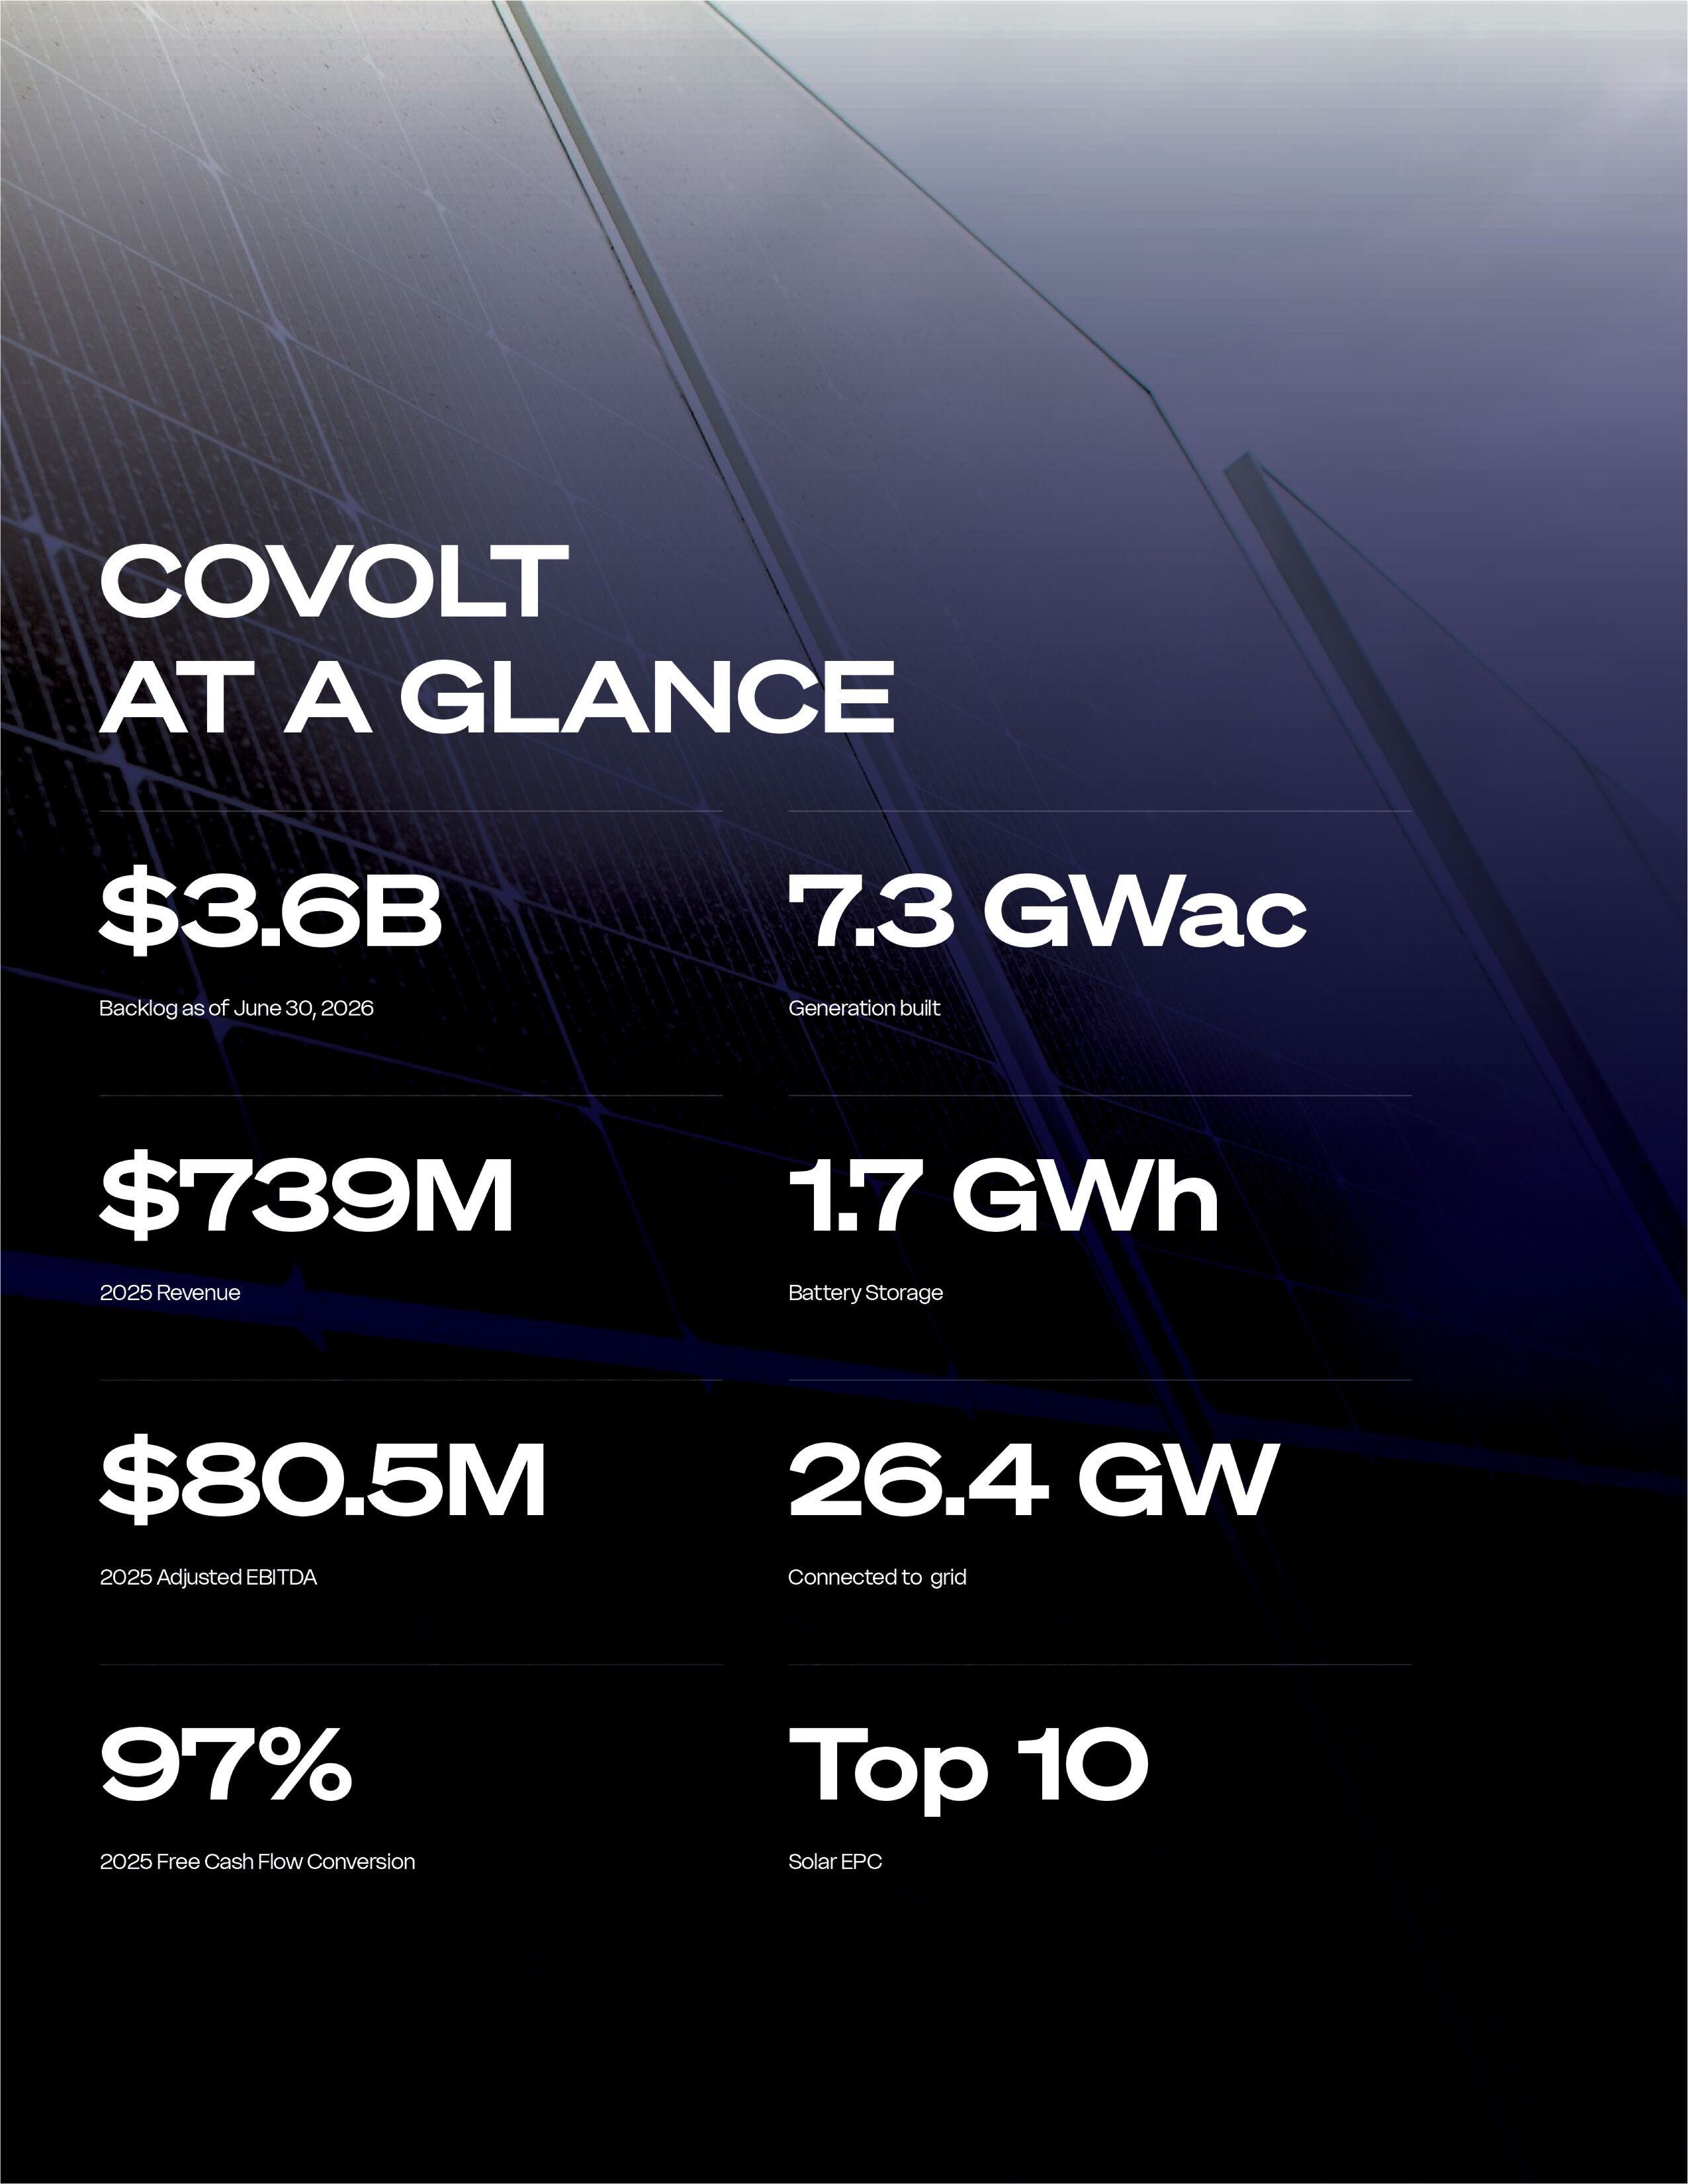
Table of Contents
| Page | ||||
| iii | ||||
| iv | ||||
| iv | ||||
| v | ||||
| 1 | ||||
| 13 | ||||
| 27 | ||||
| 72 | ||||
| 75 | ||||
| 76 | ||||
| 77 | ||||
| 79 | ||||
| Unaudited Pro Forma Condensed Consolidated Financial Information |
82 | |||
| Management’s Discussion and Analysis of Financial Condition and Results of Operations |
92 | |||
| 113 | ||||
| 132 | ||||
| 139 | ||||
| 149 | ||||
| 151 | ||||
| 159 | ||||
| 168 | ||||
| Material U.S. Federal Income Tax Consequences to Non-U.S. Holders |
171 | |||
| 176 | ||||
| 188 | ||||
| 189 | ||||
| 190 | ||||
| F-1 | ||||
Through and including , 2026 (the 25th day after the date of this prospectus), all dealers effecting transactions in these securities, whether or not participating in this offering, may be required to deliver a prospectus. This is in addition to a dealer’s obligation to deliver a prospectus when acting as an underwriter and with respect to an unsold allotment or subscription.
Neither we, the selling shareholders, nor the underwriters have authorized anyone to provide you with any information or to make any representations other than those contained in this prospectus, any amendment or supplement to this prospectus or in any free writing prospectus prepared by us or on our behalf. We, the selling shareholders and the underwriters take no responsibility for, and can provide no assurance as to the reliability of, any information other than the information in this prospectus and any free writing prospectus prepared by us or on our behalf. Offers to sell, and solicitations of offers to buy, shares of our Class A common stock are being made only in jurisdictions where offers and sales are permitted. The information contained in this prospectus is accurate only as of the date of this prospectus, regardless of the time of delivery of this prospectus or of any sale of our Class A common stock. Our business, financial condition, operating results and prospects may have changed since such date.
You should not consider any information in this prospectus, any amendment or supplement to this prospectus or any applicable free writing prospectus to be investment, legal or tax advice. You should consult your own
i
Table of Contents
counsel, accountant and other advisors for legal, tax, business, financial and related advice regarding the purchase of our Class A common stock. Neither we nor any underwriter (nor any of our or their affiliates) are making any representation to you regarding the legality of an investment in our Class A common stock by you under applicable investment or similar laws.
For investors outside the United States: Neither we, the selling shareholders, nor any of the underwriters have done anything that would permit this offering or possession or distribution of this prospectus in any jurisdiction where action for that purpose is required, other than in the United States. Persons outside of the United States who come into possession of this prospectus must inform themselves about, and observe any restrictions relating to, this offering of our Class A common stock and the distribution of this prospectus outside of the United States.
ii
Table of Contents
Basis of Presentation
In connection with the consummation of this offering, we will undertake certain organizational transactions to reorganize our corporate structure. We refer to these transactions as the “Reorganization Transactions.” See “Organizational Structure” for a description of the Reorganization Transactions and a diagram depicting our organizational structure after giving effect to the Reorganization Transactions and this offering.
Unless otherwise stated or the context otherwise requires, all information in this prospectus reflects the consummation of the Reorganization Transactions described in the “Organizational Structure” section of this prospectus and this offering, and the application of the proceeds therefrom, which we refer to collectively as the “Transactions.”
In this prospectus, unless the context otherwise requires, “CoVolt Power,” the “Company,” “we,” “us” and “our” refer (i) prior to the consummation of the Transactions described under “Organizational Structure” to CoVolt Holdings and its subsidiaries and (ii) after the Transactions described under “Organizational Structure” to CoVolt Power, Inc. and its consolidated subsidiaries. As used in this prospectus, unless the context otherwise requires, references to “we,” “us,” “our,” the “Company,” “CoVolt Power,” and similar references refer to CoVolt Power and its subsidiaries.
Certain monetary amounts, percentages, and other figures included in this prospectus have been subject to rounding adjustments. Percentage amounts included in this prospectus have not in all cases been calculated on the basis of such rounded figures, but on the basis of such amounts prior to rounding. For this reason, percentage amounts in this prospectus may vary from those obtained by performing the same calculations using the figures in our consolidated financial statements included elsewhere in this prospectus. Certain other amounts that appear in this prospectus may not sum due to rounding.
Financial Statement Presentation
CoVolt Holdings is the accounting predecessor of CoVolt Power, Inc. for financial reporting purposes. CoVolt Power, Inc. will be the audited financial reporting entity following this offering. Accordingly, this prospectus contains the following historical financial statements:
| • | CoVolt Power, Inc. Other than the balance sheets dated as of April 22, 2026 and June 30, 2026, the historical financial information of CoVolt Power, Inc. has not been included in this prospectus as it is a newly incorporated entity, and has had no business transactions or activities to date, besides our initial capitalization, the Transactions and the preparation of this prospectus and the registration statement of which this prospectus forms a part. |
| • | CoVolt Holdings. Because CoVolt Power, Inc. will have no interest in any operations other than those of CoVolt Holdings, the historical financial information included in this prospectus is that of CoVolt Holdings. |
| • | Unaudited Pro Forma Condensed Consolidated Financial Information. This prospectus contains unaudited pro forma condensed consolidated financial information as of and for the six months ended June 30, 2026 and for the year ended December 31, 2025. The unaudited pro forma condensed consolidated financial information contained in this prospectus is derived from the “Unaudited Pro Forma Condensed Consolidated Financial Information” section of this prospectus. |
Immediately following this offering, we will be a holding company and our sole material asset will be our interest in CoVolt Holdings. We will operate and control all the business and affairs of CoVolt Holdings and conduct our business through CoVolt Holdings and its subsidiaries. Following this offering, CoVolt Holdings will
iii
Table of Contents
be the predecessor of CoVolt Power, Inc. for financial reporting purposes. As a result, the consolidated financial statements of CoVolt Power, Inc. will recognize the assets and liabilities received in the reorganization at their historical carrying amounts, as reflected in the historical financial statements of CoVolt Holdings. We will consolidate CoVolt Holdings on our consolidated financial statements and record a noncontrolling interest related to the Common Units held by our Continuing Equity Owners on our consolidated balance sheet and statements of operations.
The unaudited pro forma condensed consolidated balance sheet as of June 30, 2026 contained in this prospectus presents the consolidated financial position of CoVolt Holdings after giving effect to the Transactions as if all such transactions had occurred on June 30, 2026 and has been prepared in accordance with Article 11 of Regulation S-X. The unaudited pro forma condensed consolidated statement of operations for the six months ended June 30, 2026 and year ended December 31, 2025 contained in this prospectus presents the consolidated results of operations of CoVolt Holdings after giving effect to the Transactions as if all such transactions had occurred on January 1, 2025 and has been prepared in accordance with Article 11 of Regulation S-X.
The unaudited pro forma condensed consolidated financial information is presented for informational purposes only and may not be indicative of the results that would have been achieved if the foregoing transactions had taken place on an earlier date or on the dates assumed. In addition, the unaudited pro forma condensed consolidated financial information does not purport to project the future financial condition and results of operations of CoVolt Holdings or CoVolt Power, Inc. See “Unaudited Pro Forma Condensed Consolidated Financial Information” for a complete description of the adjustments and assumptions underlying the unaudited pro forma condensed consolidated financial data.
TRADEMARKS, SERVICE MARKS AND TRADE NAMES
This prospectus includes our registered or common law trademarks, service marks and trade names, including but not limited to our design logo, CoVolt Power™, We Harness Creative Energy®, Signal Wind®, Signal Energy®, Applying Powerful Solutions™ and Applied High Voltage™, which are protected under applicable intellectual property laws. This prospectus also contains trademarks, trade names, and service marks of other companies, which are the property of their respective owners. We do not intend our use or display of other parties’ trademarks, service marks or trade names to imply, and such use or display should not be construed to imply, a relationship with, or endorsement or sponsorship of us by, these other parties. Solely for convenience, trademarks, service marks and trade names referred to in this prospectus may appear without the ®, ™, or SM symbols, but such references are not intended to indicate, in any way, that we will not assert, to the fullest extent permitted under applicable law, our rights or the right of the applicable licensor to these trademarks, service marks and trade names.
This prospectus contains estimates, projections, and information concerning our industry, our business, and the market size and growth rates of the markets in which we participate. Some data and statistical information are based on independent reports from third parties, including Wood Mackenzie, Solar Power World, the U.S. Energy Information Administration (“EIA”), Edison Electric Institute (“EEI”), the Bureau of Labor Statistics (“BLS”), National Renewable Energy Laboratory (“NREL”), and American Society of Civil Engineers (“ASCE”), as well as other industry and general publications and research.
We are responsible for all of the disclosure in this registration statement. While we believe this information to be reliable, we have not independently verified the accuracy or completeness of any data provided by
iv
Table of Contents
third-party sources. In each case, this information involves a number of assumptions and limitations, and you are cautioned not to give undue weight to such information, estimates, or projections. The industry in which we operate is subject to a high degree of uncertainty and risk due to a variety of factors, including those described in “Risk Factors” and “Cautionary Note Regarding Forward-Looking Statements.” Projections and other forward-looking information obtained from third-party sources and our internal research are subject to the same qualifications and additional uncertainties regarding the other forward-looking statements in this prospectus. Actual market size, growth rates, and other industry metrics could differ materially from those set forth herein as a result of any number of factors, including those described in “Risk Factors.” Market and industry data are current only as of the dates on which such data were prepared, and such data may no longer be current or reflect current market conditions at the time of this offering.
DEFINED TERMS AND PRESENTATION
As used in this prospectus, unless the context otherwise requires, references to “we,” “us,” “our,” the “Company,” “CoVolt Power,” and similar references refer to CoVolt Power, Inc. and its subsidiaries. In addition, the terms below that are used frequently in this prospectus have the following meanings:
| • | “2023 Preferred” shall mean the preferred equity interests issued by SEC Parent II, LLC, which were treated as debt for U.S. federal income tax purposes and were fully redeemed on August 7, 2026 in connection with the Reorganization Transactions. |
| • | “2026 Plan” shall mean the 2026 Incentive Award Plan, which will become effective in connection with this offering. |
| • | “Adjusted EBITDA” shall mean net income attributable to controlling interest before interest expense, income tax provision (benefit) and depreciation and amortization, as further adjusted for certain items as described under “Management’s Discussion and Analysis of Financial Condition and Results of Operations.” |
| • | “Adjusted EBITDA Margin” shall mean Adjusted EBITDA divided by revenue. |
| • | “Amended Bylaws” shall mean the amended and restated bylaws of CoVolt Power, which will be adopted in connection with this offering. |
| • | “Amended Charter” shall mean the amended and restated certificate of formation of CoVolt Power, which will be filed and become effective in connection with this offering. |
| • | “Basis Adjustment” shall mean the tax basis adjustments expected to be obtained by us resulting from (a) any future redemptions or exchanges of Common Units from the TRA Holders; (b) certain distributions (or deemed distributions) by CoVolt Holdings; and (c) payments made under the Tax Receivable Agreement. |
| • | “Blocker Corporations” shall mean DK Solar BT III LLC (“DK Blocker”), Bardin Hill SPV LLC (“Bardin Blocker”) and Avenue MIC Signal LLC (“Ave Blocker”), which are each a direct or indirect owner of Common Units in CoVolt Holdings prior to the Reorganization Transactions that is classified as a corporation for U.S. federal income tax purposes. |
| • | “Blocker Mergers” shall mean the mergers of each of the Blocker Corporations with and into CoVolt Power, Inc. as part of the Reorganization Transactions, pursuant to which the Blocker Shareholders receive shares of Class A common stock as consideration for the applicable Blocker Merger. |
| • | “Blocker Shareholders” shall mean owners of the Blocker Corporations prior to the Reorganization Transactions, and their respective successors. |
v
Table of Contents
| • | “Blocker Transferred Basis” shall mean (a) the share of tax basis of certain of the assets of CoVolt Holdings and its subsidiaries at the time of the Blocker Mergers that is attributable to the Common Units acquired by us from the Blocker Corporations in the Blocker Mergers and (b) any increase or decrease to such tax basis referred to in clause (a) as a result of the Blocker Mergers. |
| • | “CCGTs” shall mean combined cycle gas turbines. |
| • | “CEIC” shall mean the clean electricity investment credit under Section 48E of the U.S. Internal Revenue Code. |
| • | “CEPC” shall mean the clean electricity production credit under Section 45Y of the U.S. Internal Revenue Code. |
| • | “Common Units” shall mean the membership units of CoVolt Holdings, including those that we purchase with the net proceeds from this offering. |
| • | “Continuing Equity Owners” shall mean the direct or indirect equity holders of CoVolt Holdings immediately prior to the Reorganization Transactions who will continue to hold Common Units following the consummation of this offering and to whom shares of our Class B common stock will be issued in connection with the Reorganization Transactions. |
| • | “EOR” shall mean engineer of record. |
| • | “FERC” shall mean the Federal Energy Regulatory Commission. |
| • | “EPC” shall mean engineering, procurement, and construction. |
| • | “Exchange Act” shall mean the Securities Exchange Act of 1934, as amended. |
| • | “Exchange Existing Basis” means (a) the share of tax basis of certain of the assets of CoVolt Holdings and its subsidiaries that are attributable to the Common Units acquired by us from the TRA Parties pursuant to future redemptions, exchanges or certain contributions, and (b) any increase or decrease to such tax basis referred to in clause (a) as a result of such acquisitions. |
| • | “Existing Basis” means our share of tax basis of certain of the assets of CoVolt Holdings and its subsidiaries that are attributable to Common Units acquired by us (a) at the time of this offering or (b) after this offering (other than any Common Units acquired pursuant to future redemptions or exchanges). |
| • | “Free Cash Flow” shall mean operating cash flow less capital expenditures. |
| • | “Interest Deduction” shall mean deductions attributable to imputed interest and other payments of interest by us pursuant to the Tax Receivable Agreement. |
| • | “IPPs” shall mean independent power producers. |
| • | “IRA” shall mean the Inflation Reduction Act of 2022. |
| • | “ITC” shall mean the investment tax credit under Section 48 or Section 48E of the U.S. Internal Revenue Code, as applicable. |
| • | “JOBS Act” shall mean the Jumpstart Our Business Startups Act of 2012. |
| • | “LNTP” shall mean a limited-notice-to-proceed agreement, under which a customer pays us to perform initial engineering and site investigation work, procure long lead time equipment and materials, and begin initial mobilization of our workforce and equipment prior to finalizing a lump sum EPC contract. |
vi
Table of Contents
| • | “NERC” shall mean the North American Electric Reliability Corporation. |
| • | “O&M” shall mean operations and maintenance. |
| • | “OBBBA” shall mean the One Big Beautiful Bill Act, which was signed into law on July 4, 2025. |
| • | “PPAs” shall mean power purchase agreements. |
| • | “PRC” shall mean the People’s Republic of China. |
| • | “Reorganization Transactions” shall mean the series of organizational transactions to be completed by us in connection with the consummation of this offering, as described under “Organizational Structure,” as a result of which we will be organized in an “Up-C” structure. |
| • | “Revolving Credit Facility” shall mean that certain Revolving Credit Agreement, dated as of November 19, 2020 (as amended, restated, amended and restated, extended, supplemented or otherwise modified from time to time, including by that certain Tenth Amendment to Revolving Credit Agreement, dated as of March 25, 2026), among Signal Energy, LLC, Applied High Voltage, LLC, Signal Wind Constructors, LLC, Signal Energy DG, LLC, Signal Energy Australia Pty Ltd., SEC Holdings Group, LLC and Pinnacle Bank, as Lender and L/C Issuer. |
| • | “SCADA” shall mean supervisory control and data acquisition. |
| • | “Shareholders Agreement” shall mean the shareholders agreement to be effective upon the consummation of this offering and to be entered into by and among the Company and certain Continuing Equity Owners. |
| • | “Securities Act” shall mean the Securities Act of 1933, as amended. |
| • | “T&D” shall mean transmission and distribution. |
| • | “Tax Receivable Agreement” shall mean the Tax Receivable Agreement to be entered into by and among us, CoVolt Holdings, certain Continuing Equity Owners, the Blocker Shareholders, certain representatives and any other person that may be a party thereto (other than us, CoVolt Holdings and such representatives, the “TRA Holders”) at the consummation of this offering, pursuant to which, among other things, we will be required to pay to each TRA Holder % of the amount of cash tax savings, if any, that we realize (or in certain cases, are deemed to realize) as a result of Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions. |
| • | “TBOC” shall mean Texas Business Organizations Code, as amended. |
| • | “Transactions” shall mean the Reorganization Transactions and this offering. |
| • | “TRIR” shall mean Total Recordable Incident Rate. |
vii
Table of Contents
This summary highlights selected information contained elsewhere in this prospectus and is qualified in its entirety by the more detailed information and financial statements included elsewhere in this prospectus. This summary does not contain all of the information that you should consider before deciding to invest in our Class A common stock. You should read the entire prospectus carefully, including the sections entitled “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and our consolidated financial statements and the related notes included elsewhere in this prospectus, before making an investment decision. Some of the statements in this prospectus constitute forward–looking statements. See “Cautionary Note Regarding Forward–Looking Statements.”
Our Company
We are a leading provider of engineering, procurement, and construction services to the power and data center industries. We specialize in building utility-scale solar projects, battery energy storage systems (“BESS”) and high-voltage transmission and distribution (“T&D”) infrastructure. Since our founding in 2005, we have built more than 7.3 GWac of generation, nearly 1.7 GWh of battery storage and T&D infrastructure that connected over 26.4 GW of capacity and load to the grid. We are recognized as a top 10 utility-scale solar builder based on installations from 2015 to 2025 according to Solar Power World.
Demand for our services is growing rapidly as independent power producers (“IPPs”) add new generation to satisfy rising electricity demand, utilities upgrade and expand T&D infrastructure to support rapid load growth, and data center operators build more energy-intensive facilities. For the year ended December 31, 2025, our revenues grew 67% to $739.4 million compared to the year ended December 31, 2024 and, as of June 30, 2026, we had $3.6 billion of backlog representing an increase of 410% compared to the same date in the prior year. 85%, 13% and 2% of our backlog as of June 30, 2026 was related to generation, T&D projects and standalone battery storage, respectively. Our revenue in future periods may differ from the amounts in our backlog due to contract changes or terminations and other factors. See “Management’s Discussion and Analysis of Financial Condition and Results of Operations–Backlog” for a discussion of our backlog.
Our customers include IPPs, project developers, utilities, industrial facilities and data center operators. Since 2021, we have completed projects for 14 of the top solar 20 IPPs in the U.S. We seek to partner closely with our customers by engaging with them during the planning phases of their projects. By engaging early in project design, we help identify value engineering opportunities that benefit both our customers and us, as well as make it more difficult for competitors that are less familiar with the projects to displace us.
Our projects are typically executed over 12 to 18 months pursuant to one or more limited notice to proceed (“LNTP”) agreements followed by a lump sum engineering, procurement, and construction (“EPC”) contract. Under LNTP agreements, our customers pay us to perform initial engineering and site investigation work, procure long lead time equipment and begin initial mobilization of our workforce and equipment, the results of which we use to refine our price to construct the project. This structure reduces our risk by allowing us to learn more about the site conditions, reduce estimating assumptions and more accurately forecast our costs prior to entering into an EPC contract, and it benefits our customers by reducing change orders and schedule disruptions during construction.
We are headquartered in Houston, Texas. As of June 30, 2026, we employed approximately 345 professionals and 757 trade and craft employees.
1
Table of Contents
Our Market Opportunity
Demand for our services is driven primarily by investment in utility-scale solar projects, battery energy storage projects and T&D infrastructure, particularly substations. Annual investment in utility-scale solar and battery energy storage projects over 200 MWdc is forecast to grow from $28.5 billion in 2026 to $41.9 billion in 2031, representing a compound annual growth rate of 8.0%, according to Wood Mackenzie. Annual investment in T&D infrastructure is forecast to grow from $149.7 billion in 2026 to $218.5 billion in 2031, representing a compound annual growth rate of 7.9%, according to Wood Mackenzie. We believe key drivers of growing investment in these areas include:
| • | Step-change load growth—driven by data centers and U.S. reshoring—that is creating an urgent need for new generation. According to Wood Mackenzie and the EIA, U.S. electricity consumption is expected to grow 36.9% from 2026 to 2036 which compares with only 17.0% over the prior ten-year period from 2016 to 2026. The acceleration reflects growing investment in new, larger data centers, the reshoring of energy-intensive manufacturing, higher heating, ventilation and air conditioning (“HVAC”) demand, and broader electrification of commercial and industrial processes. The urgent need for new generation is underscored by declining operating reserve margins—the buffer of available generation capacity above expected peak demand. The North American Electric Reliability Corporation (“NERC”) currently classifies the Electric Reliability Council of Texas (“ERCOT”), Midcontinent Independent System Operator (“MISO”), PJM Interconnection (“PJM”) and portions of Western Electricity Coordinating Council (“WECC”) interconnections, which represent over 50% of electricity demand in the U.S., as having “high risk” of energy shortfalls that exceed resource adequacy targets during the period from 2026 to 2030. Wood Mackenzie forecasts that an average of 49 GWac of new solar and storage projects will be built annually during the period from 2027 to 2036, an increase of 2.2x compared to the average over the prior ten year period, and representing nearly 64% of all new generation capacity expected to be built over the period. |
| • | Outsized growth in generation and large-load interconnections that is fueling demand for more substations. New power plants, battery energy storage systems, data centers and industrial facilities require an interconnection to the grid. Each interconnection typically requires new or upgraded substations, protection and controls, and, in many cases, incremental T&D capacity. Outsized growth in both new generation and large-load projects is driving a sharp increase in the number of grid interconnections. Utilities and system operators are being asked to connect record volumes of utility-scale solar, battery storage, and other generation resources while data centers and reshored industrial facilities are adding large, concentrated loads. According to Wood Mackenzie, the total capacity of interconnection requests has increased more than three-fold over the past 10 years from 2015 to 2025. |
| • | Proliferation of on-site generation and battery storage for large users. Data centers and large industrial facilities are increasingly adding on-site generation and battery storage to secure capacity, improve resiliency, and reduce exposure to utility interconnection delays and grid constraints. These behind-the-meter systems provide firm power for peak demand, contingency events, and planned maintenance, while battery storage can also smooth load, manage demand charges, and support rapid ramping requirements. As power availability becomes a gating factor for new capacity, on-site generation and battery energy storage are becoming core components of many new data centers and industrial facilities—driving incremental demand for EPC services to engineer and integrate complex, site-specific systems, execute civil and electrical construction, and provide commissioning and compliance services. |
| • | Solar energy’s faster time-to-power and shorter equipment lead times compared to other forms of generation. Utility-scale solar projects can be delivered in 18 months or less, compared to approximately |
2
Table of Contents
| three to four years for new natural gas plants and ten years for new nuclear plants, according to Wood Mackenzie. Lead times for gas-fired generation may also extend further given reported multi-year OEM order backlogs—for example, new gas turbine lead times can exceed six years, while solar equipment such as modules, trackers, and inverters are typically available in under ten months, according to Wood Mackenzie. Solar’s faster time-to-power makes solar an attractive solution for adding capacity quickly in regions experiencing rapid load growth. |
| • | Solar’s lower levelized cost of energy compared to other forms of generation both with and without ITCs. Wood Mackenzie estimates that the levelized cost of energy for utility-scale solar with trackers including the ITC; utility-scale solar with trackers excluding the ITC; and hybrids including the ITC for the battery storage system is $54.62, $70.70 and $74.70 per MWh, respectively, which compares with $120.65 per MWh for gas combined cycle gas turbines. Solar energy’s lower levelized cost of energy combined with its lack of greenhouse gas emissions make it an attractive source of new generation capacity to utilities, corporations and the public when compared to new gas-fired generation. The falling cost of battery storage and the rising cost of new natural gas-fired power plants is also making it possible for solar to compete with natural gas as economical base load generation in certain areas of the United States. |
| • | Corporate offtakers’ continued preference for carbon-free power. According to Wood Mackenzie, 64% of PPAs in the United States for projects that came online in 2025 were signed with corporate offtakers and 89% of those PPAs were with wind and solar projects. Data center offtakers, who are expected to account for approximately 67% of the increase in electricity consumption from 2026 to 2036, prefer carbon-free power which is underscored by the commitments of top 10 data center owners to use 100% carbon-free power, according to Wood Mackenzie. |
| • | Rapid deployment of battery storage driven by expanding use cases. Energy storage deployments are being driven by the need for grid stability, backup power for data centers, peak demand management and the ability to create baseload power from solar energy and battery storage. Rising power prices and falling system costs have enabled broader adoption of battery storage systems. According to Wood Mackenzie, annual utility-scale battery storage installations will nearly double from 60.0 GWh in 2026 to 119.0 GWh in 2036. |
| • | Confluence of load growth and aging infrastructure boosting T&D investment. U.S. grid infrastructure is under increasing strain as electrification, data centers, and solar energy and battery storage drive rapid load growth and a surge in interconnection activity. At the same time, the installed base of T&D equipment is aging rapidly—T&D equipment used in the grid typically have a useful life of 25 to 40 years. According to NREL and ASCE, the majority of in-service T&D equipment used in the grid is more than 30 years old. The combination of rising demand, growing interconnection volumes, and aging infrastructure is driving increasing investment by utilities in transmission and distribution infrastructure. According to the Edison Electric Institute, utility spending on T&D infrastructure has increased every year since 2010. |
Our Strengths
We believe the following strengths of our business position us to grow faster than the markets we operate in and distinguish us from our peers:
| • | Proven operator with a longstanding market presence. We have been continuously constructing utility-scale solar projects, battery energy storage systems and high-voltage substations for more than two decades. |
3
Table of Contents
| Since our founding in 2005, we have built more than 7.3 GWac of generation, nearly 1.7 GWh of battery storage and T&D infrastructure that connected over 26.4 GW of capacity and load to the grid. We are recognized as a top 10 utility-scale solar builder based on installations from 2015 to 2025 according to Solar Power World. We believe our long operating history, scale and market leadership provide meaningful advantages versus smaller, less-established competitors, including: |
| • | Increased customer confidence in our financial capacity and operational capability to execute large, complex projects; |
| • | “Bankable” standing with customers’ lenders, supporting more favorable financing outcomes for our customers; |
| • | Deeper experience and project data to price-in risk accurately and bid with discipline; |
| • | Greater purchasing power and preferential terms with suppliers; |
| • | Preferred access to long lead, critical-path equipment such as transformers and circuit breakers; |
| • | Enhanced ability to recruit and retain top field and management talent; and |
| • | Exclusive means and methods developed over millions of hours of project execution experience. |
| • | Direct beneficiary of accelerating load growth and the retirement of fossil generation. The consumption of power in the United States is forecast to grow 36.9% from 2026 through 2036 which compares with only 17.0% over the prior 10-year period from 2016 to 2026 according to Wood Mackenzie and the EIA. At the same time, more than 13% of the existing generation fleet in the United States as of year-end 2025 is slated to be retired from 2026 through 2035 according to Wood Mackenzie. The combination of growing demand for power coupled with the large number of fossil generation retirements has created increasing demand for new generation capacity. According to Wood Mackenzie, a total of 486 GWac of solar and storage capacity will be constructed in the U.S. from 2027 to 2036, representing nearly 64% of all new generation constructed over the period. We believe these structural tailwinds—higher demand, supply attrition, and a build mix increasingly weighted toward solar and storage—will translate into sustained, growing demand for our services. |
| • | Self-perform model supported by extensive engineering, mechanical and electrical capabilities. We have the capability to self-perform all of the electrical and mechanical scopes of work and certain civil scopes of work for our customers’ projects. The level of self-performance varies by project based on project-specific requirements and our execution strategy. We self-performed over 90% of projects that commenced construction in 2025 with fully self-performed scopes. By relying on our own trained crews, standardized processes, and a dedicated equipment fleet, we can better control safety, scheduling, quality, and productivity in the field. We believe our self-perform approach enables us to capture more margin while reducing execution risk and schedule variability that can arise from dependence on third-party subcontractors, particularly in tight labor markets or remote project locations. We also leverage our front-end engineering capability to help us identify and mitigate design, permitting, procurement, and constructability risks before mobilization—supporting more predictable schedules and tighter cost control. |
| • | Scale and capabilities to execute large, complex projects. Utility-scale solar and storage projects continue to increase in size and complexity, with Wood Mackenzie forecasting that 73% and 47% of utility-scale solar projects built between 2026 and 2036 will exceed 200 MWdc and include battery storage, respectively. We believe only a limited number of contractors have a proven track record delivering projects at this scale. The average capacity of utility-scale solar and solar-plus-storage hybrid projects that we completed in 2025 was |
4
Table of Contents
| approximately 232 MWdc, positioning us as one of a small handful of contractors with consistent experience executing large, complex builds. |
| • | Dedicated in-house high-voltage platform whose capabilities are needed by a wide range of industries, including data centers, power generation, energy-intensive manufacturing and utilities. We maintain a dedicated, in-house high-voltage team focused on substation, switchyard and interconnection work for both generation projects and large-load customers. High-voltage work is highly technical, tightly regulated, and safety-intensive, and there are a limited number of qualified personnel. By self-performing this work, we enhance schedule and quality control, reduce reliance on third-party subcontractors at a key project interface, and improve overall project certainty for customers. Importantly, our high-voltage platform supports greater cost certainty and higher margins on our own projects as well as enables us to pursue third-party substation and interconnection awards, expanding our addressable market. |
| • | In-house engineering capabilities that accelerate time-to-power for customers and increase our margins. We have in-house engineering capabilities, including certified professional engineers. Unlike some of our competitors, we are able to act as the engineer of record (“EOR”) and provide our customers with stamped issued for construction (“IFC”) drawings. We believe this in-house engineer of record capability enables faster execution by reducing our reliance on third-party engineering approvals and improving design-to-field coordination, while also allowing us to capture additional margin through integrated design and delivery. |
| • | Repeat customer relationships that provide revenue predictability. We have built long-term relationships with leading independent power producers, utilities and data center operators. We generated 93% of our 2025 revenues from customers we had served in the prior three years, and our average relationship tenure with our top 25 customers is approximately seven years. These longstanding relationships give us greater visibility into future work, reduce sales and marketing costs, and make it challenging for our competitors to displace us. Our high rate of repeat business also demonstrates customer satisfaction with our execution capabilities. |
| • | Differentiated labor engagement model that supports rapid scaling. Like most contractors, we flex field labor by region based on project activity. We utilize a direct-hire model for our craftworkers which we believe drives higher quality workmanship, improved retention and more consistent project execution. A key differentiator in our approach to craft labor is the ability to mobilize skilled crews rapidly, across multiple states and on short notice, which is essential for schedule-driven projects in tight labor markets. We support that capability through an extensive and actively curated database of more than 5,000 qualified craftworkers and technicians that is continuously expanded by our dedicated craft recruiting team. We use workforce management tools to track labor availability and project requirements, enabling faster mobilization, more predictable staffing and the ability to execute multiple concurrent projects across geographies without reliance on any single local labor pool. |
| • | Dedicated apprenticeship program that strengthens our ability to attract, train, and retain labor while helping customers qualify for tax credits. We operate a Department of Labor–approved Registered Apprenticeship Program under the National Apprenticeship Act. The program helps us to attract new workers by offering participants trade-school-equivalent training, delivered by our personnel, at no cost while they earn an hourly wage. Additionally, our registered status enables our customers to satisfy federal investment tax credit labor requirements, which typically require that a specified portion of construction hours (at least 15%) be performed by registered apprentices. We believe we are among a limited number of EPCs with this capability, allowing customers to meet apprenticeship thresholds more reliably and reducing the administrative burden of sourcing apprentices and managing related compliance tracking that would otherwise fall on their teams. We also have established processes and controls to support compliance with |
5
Table of Contents
| prevailing wage requirements, which we believe enhances execution reliability and is a critical consideration for customers seeking to maximize available tax incentives. |
| • | Comprehensive, data-driven risk management that supports superior project performance. In 2022, we began implementing a coordinated set of risk management policies and procedures designed to improve job margins and reduce earnings volatility. Core elements include a bid/no-bid committee that evaluates all prospective projects for viability and attractiveness; a requirement that no firm bids are submitted unless a senior leader has physically walked the site; board approval for projects above a defined size threshold; and bi-weekly CFO-led project reviews that assess detailed project-level KPIs, including cost performance, schedule adherence and identified risks with associated mitigation plans. We also prepare a detailed risk register for every bid as part of the estimating process, no bid is submitted until subject matter experts have reviewed the risk register and developed a mitigation plan, which can include specific contract revisions, pricing additional resources and assessing additional contingency. All of the projects that reached substantial completion in 2025 exceeded initial bid margins by at least 250 bps. This demonstrates the effectiveness of our risk management practices and a more rigorous project oversight and management framework, resulting in margin predictability and consistency. |
| • | Project controls personnel report to the Chief Financial Officer not project management. In our industry, project controls personnel are typically responsible for tracking, validating, and reporting project schedules, forecasts and costs, including commitments, invoices, labor, and change orders. While many contractors structure this function to report directly to project managers, we deliberately have our project controls personnel report to our Chief Financial Officer. This reporting line reinforces independence and accountability, ensures consistent application of cost-control standards across all projects, and strengthens oversight of budget-to-actual performance. We believe with direct CFO visibility, variances are identified and escalated more quickly, enabling earlier corrective action, whether through tighter cost controls, updated forecasts, change-order recovery, or resource adjustments, before issues compound and more significantly impact overall project profitability. |
| • | Business model designed to support strong free cash flow generation. Our contract structure is designed to align customer payments with our procurement and construction activities, including customer deposits on long-lead equipment, materials funded by customers prior to procurement, and monthly progress payments throughout the construction period. This structure minimizes our working capital requirements and reduces credit risk. Combined with modest capital expenditure requirements as a percentage of revenue, we believe our model enables us to convert the majority of our Adjusted EBITDA to Free Cash Flow, which we define as operating cash flow less capital expenditures. For the 12 months ended June 30, 2026, net cash provided by operating activities was $91.8 million and capital expenditures were $0.9 million; accordingly, Free Cash Flow was $90.9 million, representing 130% of our Adjusted EBITDA. We believe our ability to generate significant Free Cash Flow coupled with our low leverage gives us the financial flexibility to invest in growth opportunities, fund equipment purchases, and manage through industry cycles without needing to rely on significant external capital. For additional discussion of our Adjusted EBITDA and Free Cash Flow, which are not measures calculated in accordance with GAAP, and for a reconciliation of these measures for the six months ended June 30, 2026, see “Management’s Discussion and Analysis of Financial Condition and Results of Operations–Non-GAAP Financial Measures” elsewhere in this prospectus. |
| • | Safety-first culture with industry-leading results. Safety is the foundation of our operations and a core value embedded throughout our organization. We use data-driven safety management, integrating leading indicators, near-miss reporting, and real-time field observations, to identify emerging patterns early and proactively mitigate risks before they become incidents. In 2025, our Total Recordable Incident Rate (“TRIR”) was 0.66 and our Lost Time Incident Rate (“LTIR”) was 0.07, versus Bureau of Labor Statistics industry |
6
Table of Contents
| averages of 1.5 and 0.4 for the power and communication line and related structures construction industry, respectively, placing our TRIR at approximately 56% better than the industry benchmark. We believe our safety track record is a competitive differentiator: it qualifies us for safety-gated projects, supports lower insurance and claims costs, and reduces the risk of schedule disruption and productivity losses associated with workplace incidents. We received the National Safety Council Occupational Excellence Achievement Award in each of 2023, 2024 and 2025 and achieved over five million work hours without a lost-time injury. |
| • | Seasoned leadership team with tight financial-operational integration. Our leadership team averages more than 20 years of experience in the construction and power industries, including oversight of multi-billion-dollar EPC and power generation project portfolios. We also position our finance team as a strategic partner to the field, providing rigorous cost visibility, disciplined forecasting, and timely decision support, so each project is executed with fiscal discipline and high operational accountability for financial results. We believe this combination of seasoned leadership and tight financial-operational integration drives consistent delivery and equips us to successfully execute increasingly large and complex projects at attractive margins. |
Our Growth Strategy
We intend to continue growing our business by:
| • | Capitalizing on the shrinking pool of EPCs capable of executing large-scale projects to grow our market share. Utility-scale projects are becoming larger and more complex as electricity demand rises and interconnection capacity becomes increasingly constrained, pushing developers and IPPs toward larger, more capital-intensive builds. According to the EIA, the average size of a utility-scale solar project has more than tripled from 2021 to 2026 with a corresponding increase in construction budgets. Wood Mackenzie expects projects above 200 MWdc to grow at a 6.5% compound annual growth rate from 2026–2031, compared with negative 6.3% for projects below 200 MWdc. Against this backdrop, we believe we are among a limited set of EPCs with the scale, systems, and financial capacity to reliably deliver projects greater than 200 MWdc. As project sizes continue to grow, we expect customers to consolidate awards with proven contractors that can manage complexity, supply chain and logistics, schedule risk, and balance-sheet requirements, creating a structural advantage for established EPCs and an opportunity for us to capture incremental share. |
| • | Capturing a larger share of fast-growing data center construction spending. As of June 30, 2026, we had approximately $225 million of backlog with data center customers, all related to high-voltage substation work. Our strategy is to continue growing our core high-voltage offering while selectively expanding into adjacent scopes, such as transmission lines, medium voltage distribution systems, and integration of on-site generation, where we can leverage existing capabilities to become a more comprehensive delivery partner for data center developers while maintaining disciplined risk selection. We believe the data center market is supported by favorable demand trends. Wood Mackenzie projects U.S. data center construction spending, excluding compute, will more than double from $93 billion in 2026 to $222 billion in 2031. |
| • | Expanding our civil self-perform capabilities to increase margins and reduce execution risk. Today, we typically self-perform certain civil work, including pile foundation and structural posts as well as trenching for medium-voltage cable, and based on the size, layout, and geological attributes of the specific site, we sometimes self-perform the earthwork and grading, including building and installing access roads, and retention ponds. We use subcontractors for other specialty civil work, such as clearing and grubbing or directional drilling and boring. We intend to selectively expand our civil self-perform capabilities where we can capture meaningful additional margin by reducing our use of subcontractors. Civil work is also frequently |
7
Table of Contents
| the primary source of project delays and execution risk, and we believe further expanding our in-house capability will allow us to better manage construction schedules, coordination and cost. |
| • | Growing our high voltage T&D business with utilities. Utilities are large buyers of high voltage services to expand, harden, and modernize their T&D systems. According to Wood Mackenzie, utilities invested $135 billion in T&D infrastructure in 2025. Historically, we generated less than 2% of our high voltage revenues from utility customers. We intend to increase our high voltage revenues by intensifying our sales efforts on utilities that have infrastructure in the geographies where we operate. |
| • | Further expanding our in-house engineering capabilities. We intend to further grow our in-house engineering resources across the areas of civil, structural and electrical design. Expanding our in-house engineering capabilities enables earlier engagement with customers, shorter design cycles, and greater confidence in execution outcomes through tighter design-to-construction coordination. Over time, we expect this to drive higher win rates, capture incremental margin by reducing reliance on third parties, and strengthen project execution through fewer design changes, clearer scope definition, and improved schedule and cost certainty. |
| • | Leveraging technology and innovation to improve construction efficiency and reduce costs. We are evaluating and piloting technology solutions to improve margins, construction quality and project safety. Our innovation efforts focus on digital technologies, drones, robotics and artificial intelligence applications across the design and construction lifecycle. Areas we are currently exploring include deploying robotic systems to install heavy components, automating manual steps in the construction workflow, reducing safety risk; creating automated processes, improving the amount of output we can create; and using drones for quantity verification, quality assurance and geographic scoping. We believe our focus on construction innovation positions us to deliver greater profitability than our peers as projects increase in size and complexity. |
| • | Pursuing strategic acquisitions that increase our scale, broaden our customer base and expand our addressable market. We intend to selectively pursue acquisitions of complementary businesses that accelerate our strategic objectives, including regional contractors in geographies where we have limited presence; providers of O&M services for solar and battery energy storage projects; specialized T&D contractors with high-voltage capabilities and utility relationships; companies with expertise in distributed gas generation; and construction firms who specialize in building data centers. We believe the infrastructure services market is fragmented with numerous small-to-midsize contractors, creating a robust pipeline of potential targets. We believe our scale, unlevered balance sheet, access to public equity capital following our IPO and proven ability to integrate businesses position us to be a consolidator in our industry. |
Summary Risk Factors
There are a number of risks that you should understand before making an investment decision regarding this offering. These risks are discussed more fully in the section entitled “Risk Factors” following this prospectus summary. If any of these risks actually occur, our business, financial condition, or results of operations could be materially and adversely affected. In such case, the trading price of our Class A common stock would likely decline, and you may lose all or part of your investment. These risks include, but are not limited to:
| • | A wide range of factors beyond our control, including adverse weather, permitting delays, grid interconnection issues, and supply chain disruptions, impacting project timing and profitability, resulting in additional costs, liquidated damages, or contract terminations; |
| • | Our reliance on lump sum contracts exposing us to the risk of reduced profits or losses if actual project costs exceed our estimates; |
8
Table of Contents
| • | Our labor-intensive business model and the challenge of attracting and retaining qualified electricians, project managers, engineers, and skilled construction personnel, as well as risks related to collective bargaining agreements and multiemployer pension plan obligations; |
| • | Our dependence on a limited number of large customers for a significant portion of our revenue, exposing us to revenue volatility; |
| • | The cancellation, suspension, or non-renewal of contracts on short notice, and our potential inability to replace such contracts; |
| • | Our failure to adequately recover on contract modifications, change orders, or claims against customers, reducing our revenues and profitability; |
| • | Our exposure to warranty, engineering, design defect, and performance guarantee claims arising from the nature of our EPC business; |
| • | Health and safety risks inherent in large-scale solar and battery storage construction operations, including risks of worksite injuries and fatalities; |
| • | Distinct risks presented by our high-voltage substation, T&D, and data center services, including more stringent regulatory requirements and dependence on hyperscaler capital allocation decisions; |
| • | Litigation, claims, and legal proceedings in the ordinary course of our business, including personal injury claims, breach of contract disputes, and bonding claims; |
| • | Our inability to obtain surety bonds, letters of credit, or bank guarantees limiting our ability to compete for projects; |
| • | Risks that if the market for artificial intelligence technologies does not grow as expected, our data center customers may reduce their projected power needs, impacting demand for our services; |
| • | Cybersecurity threats and data breaches exposing us to significant liabilities, reputational harm, and operational disruption; |
| • | Our dependence on the continued services of key personnel, including our senior management team and skilled project managers; |
| • | Our insurance coverage may be inadequate to cover all losses or liabilities we may incur, and insurance may become more difficult or expensive to obtain in the future; |
| • | Our use of the percentage-of-completion method of revenue recognition requiring subjective estimates that, if incorrect, could require us to recognize losses or revise previously reported revenues; |
| • | Our backlog may not be realized or may not result in profits, and may not accurately represent future revenue; |
| • | Significant backlogs in grid interconnection queues delaying or preventing our customers’ projects from reaching construction, reducing demand for our EPC services; |
| • | Our inability to successfully execute our acquisition strategy or integrate acquired businesses, adversely impacting our growth; |
| • | Negative macroeconomic conditions, including inflation, rising interest rates, and tighter credit markets, reducing demand for solar energy and battery storage projects; |
9
Table of Contents
| • | The reduction, elimination, or expiration of government incentives for solar energy and battery storage, including federal tax credits under the Inflation Reduction Act, and the potential accelerated termination of such incentives as a result of recent legislation such as the OBBBA, significantly reducing demand for our EPC services; |
| • | Technological advancements in other forms of power generation reducing investment in solar and battery storage projects and decreasing demand for our EPC services; |
| • | Intense competition from other EPC contractors, self-performing customers, and new market entrants pressuring our pricing, margins, and market share; |
| • | Complex federal, state, and local environmental, health, and safety laws and regulations exposing us to significant liabilities or requiring costly compliance measures; |
| • | Risks associated with forced labor laws and supply chain traceability requirements, including the Uyghur Forced Labor Prevention Act, potentially causing project delays and increased costs; |
| • | The risk that we could be deemed an investment company under the Investment Company Act of 1940 as a result of our ownership of CoVolt Holdings, which could make it impractical to continue our business as contemplated; |
| • | Volatility in the market price of our common stock causing the value of an investment in our stock to decline; |
| • | The absence of an established public market for our common stock prior to this offering and uncertainty regarding whether an active trading market will develop; |
| • | Control by our principal shareholders limiting the ability of other shareholders to influence corporate matters; |
| • | The TBOC has been recently amended to provide additional protections for our officers, directors and affiliates while making it more difficult for shareholders to make proposals at our annual meeting or to bring derivative claims. As a result, our shareholders may be disadvantaged as compared to shareholders of Delaware corporations; |
| • | Substantial future sales of our common stock, or the perception thereof, depressing our stock price; |
| • | The absence of securities or industry analyst coverage, or the publication of unfavorable research, adversely affecting our stock price and trading volume; |
| • | Our reliance on reduced disclosure and governance requirements as an “emerging growth company,” potentially making our stock less attractive to some investors; |
| • | The requirements of being a public company straining our resources, diverting management’s attention, and affecting our ability to attract qualified directors and officers; and |
| • | Upon the listing of our shares on the NYSE, we will be a “controlled company” within the meaning of the rules of the NYSE and, as a result, will qualify for, and intend to rely upon, exemptions from certain corporate governance requirements. If we rely on such exemptions in the future, you will not have the same protections afforded to stockholders of companies that are subject to such requirements. |
Future material weaknesses or our failure to develop or maintain an effective system of internal controls, adversely affecting investor confidence and the value of our Class A common stock.
10
Table of Contents
Before you invest in our Class A common stock, you should carefully consider all of the information in this prospectus, including matters set forth under the heading “Risk Factors.”
Implications of Being an Emerging Growth Company
We qualify as an “emerging growth company” as defined in Section 2(a) of the Securities Act of 1933, as amended (the “Securities Act”), as modified by the Jumpstart Our Business Startups Act of 2012 (the “JOBS Act”). As an emerging growth company, we may take advantage of specified reduced disclosure and other requirements that are otherwise applicable, in general, to public companies that are not emerging growth companies. These provisions include:
| • | the presentation of only two years of audited financial statements and only two years of related Management’s Discussion and Analysis of Financial Condition and Results of Operations in this prospectus; |
| • | reduced disclosure about our executive compensation arrangements; |
| • | no non-binding shareholder advisory votes on executive compensation or golden parachute arrangements; |
| • | exemption from compliance with the requirement of the Public Company Accounting Oversight Board regarding communication of critical accounting matters in the auditor’s report in the financial statements; and |
| • | exemption from the auditor attestation requirement in the auditing assessment over internal control over financial reporting. |
We may take advantage of these provisions until the last day of our fiscal year following the fifth anniversary of the date of the first sale of our Class A common stock in this offering or such earlier time that we are no longer an emerging growth company. We would cease to be an emerging growth company upon the earliest of: (i) the last day of the first fiscal year in which our annual gross revenues are $1.235 billion or more; (ii) the date on which we have, during the previous three-year period, issued more than $1.0 billion in non-convertible debt securities; or (iii) the date on which we are deemed to be a “large accelerated filer,” which will occur as of the end of any fiscal year in which we (x) have an aggregate market value of our Class A common stock held by non-affiliates of $700 million or more as of the last business day of our most recently completed second fiscal quarter, (y) have been required to file annual and quarterly reports under the Securities and Exchange Act of 1934, as amended (the “Exchange Act”), for a period of at least 12 months and (z) have filed at least one annual report pursuant to the Exchange Act.
We may choose to take advantage of some or all of these reduced burdens. We have elected to adopt the reduced requirements with respect to the presentation of our financial statements and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” disclosure. Further, pursuant to Section 107 of the JOBS Act, as an emerging growth company, we have elected to take advantage of the extended transition period for complying with new or revised accounting standards until those standards would otherwise apply to private companies. As a result, our operating results and financial statements may not be comparable to the operating results and financial statements of other companies who have adopted the new or revised accounting standards. It is possible that some investors will find our Class A common stock less attractive as a result of these elections, which may result in a less active trading market for our Class A common stock and higher volatility in our stock price.
11
Table of Contents
Our Corporate Information
CoVolt Power, Inc., the registrant and the issuer of our Class A common stock in this offering, was incorporated as a Texas corporation on April 22, 2026. Our corporate headquarters are located at 711 Louisiana Street, Suite ST 2500, Houston, Texas 77002. Our telephone number is (713) 267-5567.
In connection with this offering, the Company rebranded from Signal Energy to CoVolt Power. Except as otherwise indicated or where the context otherwise requires, references in this prospectus to “Signal Energy” refer to the Company prior to the rebranding.
Our principal website address is http://www.covolt.com. The information on, or that can be accessed through, our website is deemed not to be incorporated in this prospectus or to be part of this prospectus. You should not consider information contained on our website to be part of this prospectus in deciding whether to purchase shares of our Class A common stock.
12
Table of Contents
In connection with the closing of this offering, we will undertake certain organizational transactions subsequent to which we will conduct our business through what is commonly referred to as an “Up-C” structure, which is often used by partnerships and limited liability companies when they decide to undertake an initial public offering. Unless otherwise stated or the context otherwise requires, all information in this prospectus reflects the consummation of the Reorganization Transactions.
Following the consummation of the Reorganization Transactions, we will be a holding company. Our sole material asset will be our equity interest in CoVolt Holdings, which, through its direct and indirect subsidiaries, will conduct all of our operations. Because CoVolt Power, Inc. will be the sole managing member of CoVolt Holdings, we will indirectly operate and control all of the business and affairs (and will consolidate the financial results) of CoVolt Holdings and its subsidiaries.
Prior to the consummation of the Reorganization Transactions, the capital structure of CoVolt Holdings’ indirect parent, SEC Parent II, LLC, consists of two classes of membership interests: New Class A Units and New Class B Units, and CoVolt Holdings is a wholly owned subsidiary of SEC Parent II, LLC held through SEC Intermediate, LLC.
In connection with the consummation of this offering, we will complete a series of reorganization transactions, including: (i) the amendment and restatement of the CoVolt Holdings LLC Agreement to, among other things, effect a recapitalization in which all existing membership interests in CoVolt Holdings are converted into one class of Common Units; (ii) the amendment and restatement of the CoVolt Power, Inc. certificate of formation to, among other things, authorize two classes of common stock; (iii) CoVolt Power, Inc.’s designation as managing member of CoVolt Holdings; (iv) the merger of SEC Intermediate, LLC with and into SEC Parent II, LLC, with SEC Parent II, LLC surviving such merger, followed by the liquidation of SEC Parent II, LLC in which the holders of equity interests in SEC Parent II, LLC receive equity interests in CoVolt Holdings; (v) the amendment and restatement of the SEC Member II, LLC Agreement to, among other things, effect a recapitalization in which all existing membership interests of SEC Member II, LLC are converted into one class of common units; (vi) the Blocker Mergers, pursuant to which each Blocker Corporation will merge with and into CoVolt Power, Inc., with the Blocker Shareholders receiving shares of Class A common stock; (vii) the contribution by an affiliate of Avenue Capital Group of its Common Units to CoVolt Power, Inc. in exchange for shares of Class A common stock; (viii) CoVolt Power, Inc.’s acquisition of Common Units held by certain of the Continuing Equity Owners in exchange for an equal number of shares of Class A common stock or, in the case of certain Continuing Equity Owners, cash; and (ix) CoVolt Power, Inc.’s issuance of Class B common stock to the Continuing Equity Owners in exchange for a nominal cash contribution made by such Continuing Equity Owners, resulting in a combined company organized in an Up-C structure. Following the consummation of this offering, we will contribute the remaining net proceeds of this offering to CoVolt Holdings in exchange for newly issued Common Units. See “Organizational Structure,” “Certain Relationships and Related Party Transactions” and “Description of Capital Stock” for additional information.
After giving effect to the Reorganization Transactions and this offering and assuming the underwriters’ option to purchase additional shares from the selling shareholders is not exercised:
| • | the Continuing Equity Owners will own all of our Class B Common Stock, representing % total voting power of our capital stock; |
| • | Investors in this offering will own shares of our Class A common stock, representing % total voting power of our capital stock; |
13
Table of Contents
| • | We will own an approximate % interest in CoVolt Holdings; and |
| • | The Continuing Equity Owners will own an approximate % interest in CoVolt Holdings. |
| • | the former Blocker Shareholders will own an aggregate of shares of our Class A common stock, representing approximately % of the combined voting power of our capital stock and approximately % of the economic interest in the Company, in each case without holding any Class B common stock or Common Units directly. |
Tax Receivable Agreement
In connection with the completion of this offering, we and CoVolt Holdings will enter into the Tax Receivable Agreement with the TRA Holders. This Tax Receivable Agreement will provide for the payment by CoVolt Power, Inc. to the TRA Holders of % of the benefits, if any, that CoVolt Power, Inc. is deemed to realize (calculated using certain assumptions) as a result of the Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions. Assuming no material changes in the relevant tax laws and that we earn sufficient taxable income to realize all tax benefits that are subject to the Tax Receivable Agreement, we expect the tax savings associated with the Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions would aggregate to approximately $ million over years from the date of this offering based on the assumed initial public offering price of $ per share of our Class A common stock (the midpoint of the estimated price range set forth on the cover page of this prospectus), and assuming all redemptions or exchanges would occur immediately after the initial public offering for the remaining ownership of CoVolt Holdings not acquired by CoVolt Power, Inc. Under such scenario, assuming future payments are made on the date each relevant tax return is due, without extensions, we would be required to pay approximately % of such amount, or approximately million over the -year period from the date of this offering, to the TRA Holders. The actual amounts we will be required to pay under the Tax Receivable Agreement may be significantly different from the amounts described in the preceding sentence. See “Risk Factors–Risks Related to Our Capital Structure” and “Certain Relationships and Related Party Transactions–Tax Receivable Agreement” for additional information regarding the Tax Receivable Agreement.
Redemption Right
Following this offering, under the CoVolt Holdings LLC Agreement, each holder of Common Units (other than us), will, subject to certain limitations, have the right (the “Redemption Right”) to cause CoVolt Holdings to redeem all or a portion of its Common Units for, at CoVolt Holdings’ election, (i) shares of our Class A common stock at a redemption ratio of one share of Class A common stock for each Common Unit redeemed, subject to conversion rate adjustments for stock splits, stock dividends and reclassifications and other similar transactions, or (ii) an equivalent amount of cash. Alternatively, upon the exercise of the Redemption Right, we (instead of CoVolt Holdings) will have the right (the “Call Right”) to acquire the tendered Common Units directly from such redeeming holder by paying, at our option, either (i) shares of our Class A common stock at a redemption ratio of one share of Class A common stock for each Common Unit redeemed, subject to conversion rate adjustments for stock splits, stock dividends and reclassifications and other similar transactions, or (ii) an equivalent amount of cash.
In connection with any redemption of Common Units pursuant to the Redemption Right (or an acquisition of Common Units by us pursuant to the Call Right), a corresponding number of shares of Class B common stock will be cancelled.
14
Table of Contents
Any decision to cause CoVolt Holdings to make a cash payment pursuant to the Redemption Right or Call Right will be made by our independent directors (within the meaning of the NYSE listing rules and Section 10A-3 of the Securities Act). Such independent directors will determine whether to issue shares of Class A common stock or pay cash in accordance with the CoVolt Holdings LLC Agreement based on facts in existence at the time of the decision, which we expect would include the relative value of the Class A common stock (including the trading price for shares of Class A common stock at the time), the cash purchase price and the availability of other sources of liquidity (such as an issuance of preferred stock or additional shares of common stock) to acquire the Common Units and alternative uses for such cash.
Subject to certain limitations and exceptions, the holders of Common Units will be permitted to cause a redemption of their Common Units for shares of our Class A common stock on the terms set forth in the CoVolt Holdings LLC Agreement. As the holders of Common Units cause their Common Units to be redeemed, our membership interest in CoVolt Holdings will be correspondingly increased, the number of shares of Class A common stock outstanding will be increased, and the number of shares of Class B common stock outstanding will be decreased. See “Certain Relationships and Related Party Transactions–CoVolt Holdings LLC Agreement.”
Holding Company Structure
Our post-offering organizational structure will allow the Continuing Equity Owners to retain a direct equity ownership in CoVolt Holdings, which will be classified as a partnership for U.S. federal income tax purposes following the offering. As a result the Continuing Equity Owners (as well as CoVolt Power) will generally incur U.S. federal, state and local income taxes on their proportionate share of any taxable income of CoVolt Holdings. Investors in this offering will, by contrast, hold their equity ownership in CoVolt Power, which will be classified as a domestic corporation for U.S. federal income tax purposes, in the form of shares of Class A common stock, and an indirect ownership interest in CoVolt Holdings through CoVolt Power’s ownership of Common Units. The CoVolt Holdings LLC Agreement will generally provide, to the extent cash is available, for pro rata distributions to holders of Common Units (including CoVolt Power) in an amount at least sufficient to allow CoVolt Power to pay its taxes.
We selected the Up-C structure because it is a well-established organizational framework for initial public offerings by companies that were previously organized as partnerships or limited liability companies, and because we believe the structure provides meaningful benefits to both the Company and the Continuing Equity Owners.
The Up-C structure preserves CoVolt Holdings’ classification as a partnership for U.S. federal income tax purposes following this offering, which provides the following principal benefits:
Benefits to the Company and Holders of Class A Common Stock
| • | Retention of Tax Benefits. Future redemptions or exchanges of Common Units by the Continuing Equity Owners are expected to result in adjustments to the tax basis of the assets of CoVolt Holdings. These Basis Adjustments, as well as Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions, may have the effect of reducing the amounts that CoVolt Power would otherwise pay in the future to various tax authorities. Under the Tax Receivable Agreement, CoVolt Power will retain % of the cash tax savings, if any, that it actually realizes as a result of Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions, which we expect will reduce our future tax liability and increase cash available for our operations and growth initiatives. See “Certain Relationships and Related Party Transactions–Tax Receivable Agreement.” |
15
Table of Contents
| • | Operational Continuity. The Up-C structure enables us to complete this offering without a conversion of CoVolt Holdings from a limited liability company to a corporation, thereby avoiding the operational disruption, and third-party consent requirements that could accompany a full corporate conversion. CoVolt Power, as the sole managing member of CoVolt Holdings, will control all of the day-to-day business affairs and decision-making of CoVolt Holdings, and the organizational structure will not alter our existing operations, customer relationships, or contractual arrangements. |
| • | Investor Familiarity. The Up-C structure is widely used in initial public offerings of former partnerships and limited liability companies and we believe this structure is well-understood by public market investors, which we believe facilitates investor evaluation of our business and capital structure. |
Benefits to the Continuing Equity Owners
| • | Tax Efficiency. The Continuing Equity Owners will be taxed on their allocable share of CoVolt Holdings’ income on a flow-through basis, thereby avoiding an additional level of entity-level taxation on their pre-IPO interests that would result from a direct corporate conversion. |
| • | Phased Liquidity. The Redemption Right provides a mechanism for the Continuing Equity Owners to monetize their interests over time through the exchange of Common Units for shares of Class A common stock on a one-for-one basis (or, at our election, subject to certain conditions, a cash payment equal to a volume weighted average market price of one share of our Class A common stock for each Common Unit so redeemed). This phased approach is designed to facilitate an orderly transition to public ownership while providing the Continuing Equity Owners with flexibility in managing the timing and tax consequences of any future disposition of their interests. See “Certain Relationships and Related Party Transactions–CoVolt Holdings LLC Agreement–Common Unit Redemption Right.” |
| • | Voting Rights. The Continuing Equity Owners will receive shares of Class B common stock, each of which entitles the holder to one vote per share on all matters on which shareholders are entitled to vote generally. This enables the Continuing Equity Owners to maintain voting power commensurate with their economic ownership in CoVolt Holdings while holding their economic interests directly through Common Units. The Continuing Equity Owners will initially hold % of the combined voting power of our common stock. |
Tax Receivable Agreement Payments
| • | Tax Receivable Agreement Payments. Under the Tax Receivable Agreement, the TRA Holders will receive payments equal to % of the cash tax savings, if any, that CoVolt Power actually realizes, or in certain circumstances is deemed to realize, as a result of Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions. We expect these payments to be substantial. Based on certain assumptions, we estimate that the aggregate payments under the Tax Receivable Agreement could be approximately $ million over the term of the agreement, assuming all Common Units were exchanged or redeemed on the date of this offering. In addition, in the event of a change of control of CoVolt Power (as defined in the Tax Receivable Agreement), we would be required to make an early termination payment to the TRA Holders equal to the present value of all future payments that would be required to be made under the Tax Receivable Agreement (calculated using certain valuation assumptions, including that we would have sufficient taxable income to fully utilize the relevant tax benefits), which early termination payment we expect could be substantial. See “Organizational Structure–Tax Receivable Agreement” and “Risk Factors–Risks Related to Our Capital Structure–The Tax Receivable Agreement with CoVolt Holdings and the |
16
Table of Contents
| TRA Holders requires us to make cash payments to the TRA Holders in respect of certain tax benefits to which we may become entitled, and we expect that such payments will be substantial.” |
The interests of the Continuing Equity Owners may not be aligned with the interests of holders of our Class A common stock in all circumstances. For a discussion of the potential conflicts of interest associated with our organizational structure, see “Risk Factors–Risks Related to Our Capital Structure–The Continuing Equity Owners may have conflicting interests with holders of shares of our Class A common stock” and “Risk Factors–Risks Related to Our Capital Structure–Our organizational structure, including the Tax Receivable Agreement, confers certain benefits upon the Continuing Equity Owners that will not benefit holders of our Class A common stock to the same extent that it will benefit the Continuing Equity Owners.”
Material Subsidiaries
CoVolt Holdings conducts its operations through the following material subsidiaries:
| • | Signal Energy, LLC. Signal Energy, LLC is our primary operating subsidiary and provides engineering, procurement, and construction services for utility-scale solar generation projects and battery energy storage systems. Signal Energy, LLC serves as the prime contractor on our EPC projects throughout the United States, contracting directly with project owners (including independent power producers, project developers, utilities, and data center operators) for full-scope integrated delivery. Signal Energy, LLC’s services encompass the full project lifecycle, including front-end engineering and design, procurement of major equipment and materials, civil and structural construction, electrical and mechanical installation, and commissioning and testing. Signal Energy, LLC self-performs the majority of its electrical, mechanical, and certain civil scopes of work through its trained workforce and dedicated equipment fleet, and maintains in-house engineering capabilities, including certified professional engineers who may serve as the engineer of record. We operate through Signal Energy, LLC as our prime contracting entity because its established contractor licenses, surety bonding capacity, customer relationships, and operating history enable it to serve as the contracting counterparty on large-scale EPC engagements and to hold the associated performance obligations, warranties, and insurance programs. |
| • | Applied High Voltage, LLC. Applied High Voltage, LLC is an EPC contractor that specializes in high-voltage electrical construction and designs and builds high-voltage substations, switchyards, collector systems, and transmission lines for projects across the United States. Applied High Voltage, LLC’s services include installation of major substation equipment, transformers, circuit breakers, protective relays, control systems, and SCADA systems, as well as aerial and underground high-voltage transmission and distribution lines. Applied High Voltage, LLC also provides high-voltage system commissioning and testing. Applied High Voltage, LLC provides services both to external customers (including independent power producers, utilities, and data center operators) and as a subcontractor to Signal Energy, LLC on the high-voltage components of our integrated EPC projects. We maintain Applied High Voltage, LLC as a separate subsidiary because high-voltage work requires specialized engineering expertise and licenses, and compliance with regulatory requirements (including NERC and FERC standards) that differ from those applicable to our generation and storage construction activities. Operating through a dedicated entity allows us to maintain the specialized qualifications, certifications, and safety programs necessary to perform work on or adjacent to the bulk electric system while also enabling Applied High Voltage, LLC to contract directly with third-party customers for standalone high-voltage projects independent of our generation EPC work. |
A complete list of our material subsidiaries is set forth in Exhibit 21.1 to the registration statement of which this prospectus forms a part.
17
Table of Contents
The following diagram reflects our simplified organizational structure after giving effect to the Transactions:
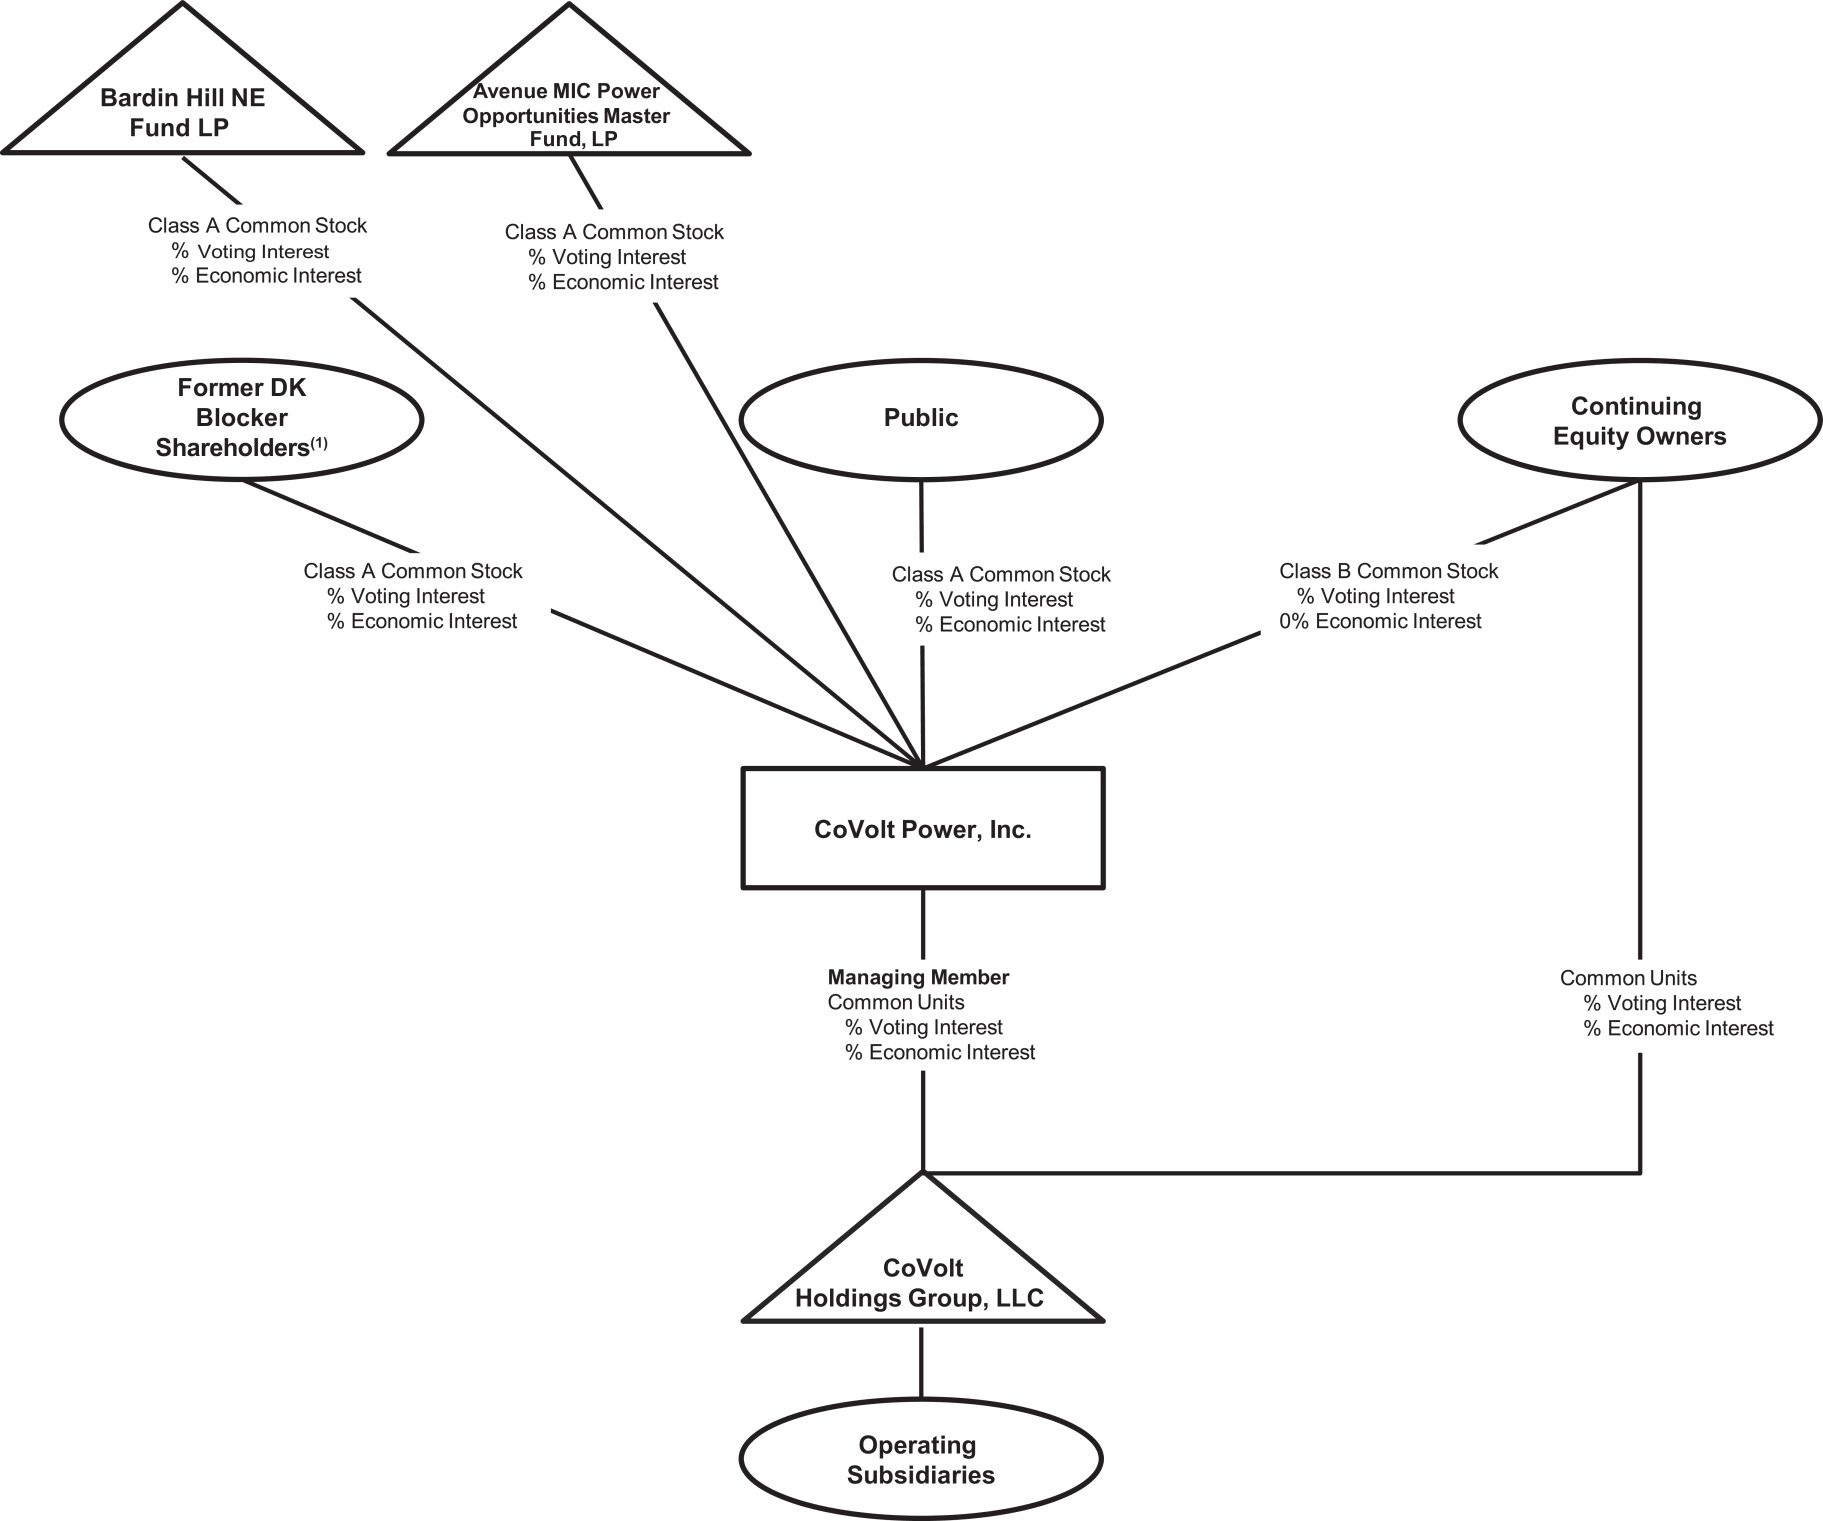
| (1) | Includes (i) Davidson Kempner International Master Fund Ltd., (ii) Davidson Kempner Distressed Opportunities International Ltd. and (iii) Davidson Kempner Institutional Partners, L.P. |
| (2) | Following this offering, the Continuing Equity Owners will have the right to cause the redemption of common units. See “The Offering–Redemption Right.” |
| (3) | For more information regarding the beneficial ownership of our Class A common stock and Class B common stock, see “Principal and Selling Shareholders.” |
18
Table of Contents
THE OFFERING
| Class A common stock offered by us |
shares. |
| Class A common stock offered by the selling shareholders |
shares (or shares if the underwriters exercise their option to purchase additional shares of Class A common stock from the selling shareholders in full). |
| Underwriters’ option to purchase additional shares of Class A common stock |
The selling shareholders have granted the underwriters an option for a period of 30 days from the date of this prospectus to purchase up to an additional shares of our Class A common stock from the selling shareholders at the initial public offering price, less the underwriting discounts and commissions. |
| Class A common stock to be outstanding after this offering |
shares (or shares if the underwriters exercise their option to purchase additional shares of Class A common stock from the selling shareholders in full). |
| Class B common stock to be outstanding after this offering |
shares (or shares if the underwriters exercise their option to purchase additional shares of Class A common stock from the selling shareholders in full), or one share for each Common Unit held by the Continuing Equity Owners following this offering. Shares of Class B common stock are non-economic but each share thereof will entitle its holder to one vote on all matters to be voted on by shareholders generally, voting together as a single class with holders of the shares of Class A common stock. In connection with any redemption of Common Units, a corresponding number of shares of Class B common stock will be cancelled. |
| Voting power of Class A common stock after giving effect to this offering |
% (or % if the underwriters’ option to purchase additional shares from the selling shareholders is exercised in full). |
| Voting power of Class B common stock after giving effect to this offering |
% (or % if the underwriters’ option to purchase additional shares from the selling shareholders is exercised in full). Upon completion of this offering, the Continuing Equity Owners will initially own all shares of Class B common stock, representing approximately % of the voting power of the Company. |
| Voting rights |
Each share of our Class A common stock entitles its holder to one vote on all matters to be voted on by shareholders generally. Each share of our Class B |
19
Table of Contents
| common stock entitles its holder to one vote on all matters to be voted on by shareholders generally. Holders of our Class A common stock and our Class B common stock will vote together as a single class on all matters presented to our shareholders for their vote or approval, except as otherwise required by applicable law or by our Amended Charter. See “Description of Capital Stock.” |
| Common Units to be held by us following this offering |
Common Units, representing approximately % of the economic interest in CoVolt Holdings (or Common Units, representing approximately % of the economic interest in CoVolt Holdings if the underwriters exercise in full their option to purchase additional shares of Class A common stock from the selling shareholders); |
| Common Units to be held by the Continuing Equity Owners following this offering |
Common Units, representing approximately % of the economic interest in CoVolt Holdings (or Common Units, representing approximately % of the economic interest in CoVolt Holdings if the underwriters exercise in full their option to purchase additional shares of Class A common stock from the selling shareholders). |
| Use of proceeds |
We estimate that we will receive net proceeds from this offering of approximately $ million, based upon an assumed initial public offering price of $ per share (which is the midpoint of the price range set forth on the cover page of this prospectus) and after deducting estimated underwriting discounts and commissions and estimated offering expenses payable by us. We will not receive any proceeds from the sale of shares of Class A common stock by the selling shareholders. |
| The principal purposes of this offering are to create a public market for our Class A common stock and enable access to the public equity markets for our shareholders. We intend to use the net proceeds from this offering to purchase Common Units from certain of the Continuing Equity Owners and to contribute the remaining net proceeds to CoVolt Holdings in exchange for newly issued Common Units. CoVolt Holdings intends to use the net proceeds from this offering for general corporate purposes, including working capital, operating expenses and capital expenditures. We will have broad discretion in the way that we use the net proceeds of this offering. See “Use of Proceeds.” |
| Dividend policy |
We have no current plans to pay dividends on our Class A common stock following this offering. Any decision to declare and pay dividends in the future will be made at the sole discretion of our board of directors and will depend on, among other things, our results of operations, cash requirements, financial condition, contractual restrictions and other factors that our board of directors may deem relevant. Because we are a holding company and have no direct operations, we will only be able to pay dividends from funds we receive from our |
20
Table of Contents
| subsidiaries. In addition, our ability to pay dividends is limited by our Revolving Credit Agreement and may be limited by the agreements governing any indebtedness we or our subsidiaries may incur in the future. See “Dividend Policy.” |
| Controlled Company |
Upon the closing of this offering, certain of our Continuing Equity Owners will collectively hold a majority of the combined voting power of our shares eligible to vote in the election of our directors (or approximately % if the underwriters exercise in full their option to purchase additional shares of Class A common stock from the selling shareholders). As a result, we will be a “controlled company” under NYSE rules. As a controlled company, we will qualify for, and intend to rely upon, exemptions from certain corporate governance requirements of the NYSE. See “Management–Controlled Company Exception.” |
| Tax Receivable Agreement |
In connection with the completion of this offering, we will enter into the Tax Receivable Agreement with CoVolt Holdings and the TRA Holders that will provide for the payment by us to the TRA Holders of % of the cash tax savings, if any, that we actually realize, or in certain circumstances are deemed to realize, as a result of Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions. We expect that the amount of cash payments we will be required to make under the Tax Receivable Agreement will be substantial. See “Organizational Structure–Tax Receivable Agreement” and “Certain Relationships and Related Party Transactions–Tax Receivable Agreement.” |
| Directed Share Program |
At our request, the underwriters have reserved for sale, at the initial public offering price, up to % of the Class A common stock being offered for sale, to our directors, officers and certain employees and other related parties. The sales will be made at our direction by , an underwriter of this offering, and its affiliates through a directed share program. The number of shares of Class A common stock available for sale to the general public will be reduced to the extent these individuals purchase such reserved shares. Any reserved shares that are not so purchased will be offered by the underwriters to the general public on the same basis as the other shares offered by this prospectus. Except for any shares acquired by our directors and officers, shares purchased pursuant to the directed share program will not be subject to lock-up agreements with the underwriters. See “Underwriting–Directed Share Program.” |
| Redemption Right |
Following this offering, under the CoVolt Holdings LLC Agreement, the Continuing Equity Owners will have the right (the “Redemption Right”) to cause CoVolt Holdings to redeem all or a portion of their Common Units for, at CoVolt Holdings’ election, (i) shares of our Class A common stock at a redemption ratio of one share of Class A common stock for each Common Unit redeemed, subject to conversion rate adjustments for stock splits, stock dividends, reclassifications and other similar transactions, or (ii) an equivalent amount of cash. Alternatively, upon the exercise of the Redemption Right, CoVolt Power, Inc. will have the right (the “Call Right”) to acquire the tendered Common Units directly from the redeeming holder |
21
Table of Contents
| of Common Units by paying, at its election, either shares of Class A common stock (on a one-for-one basis, subject to the same conversion rate adjustments) or an equivalent amount of cash. In connection with any redemption of Common Units pursuant to the Redemption Right or acquisition of Common Units pursuant to the Call Right, a corresponding number of shares of Class B common stock held by the exchanging Continuing Equity Owner will be cancelled. See “Organizational Structure–Redemption Right” and “Certain Relationships and Related Party Transactions–CoVolt Holdings LLC Agreement.” |
| Risk factors |
Investing in our Class A common stock involves risks. See “Risk Factors” beginning on page 27 and other information included in this prospectus for a discussion of factors you should carefully consider before deciding to invest in shares of our Class A common stock. |
| Proposed trading symbol |
We have applied to list our Class A common stock on the NYSE under the symbol “KVLT.” |
Unless otherwise indicated, all information contained in this prospectus assumes or gives effect to:
| • | the filing and effectiveness of our amended and restated certificate of formation, or the Amended Charter, and the adoption of our amended and restated bylaws, or the Amended Bylaws, each of which will occur immediately after the effectiveness of this registration statement and which will effect the reclassification of all outstanding shares into our Class A common stock; |
| • | no exercise by the underwriters of their option to purchase up to shares of Class A common stock from the selling shareholders; and |
| • | an initial public offering price of $ per share of Class A common stock, which is the midpoint of the price range set forth on the cover page of this prospectus. |
The number of shares of our Class A common stock that will be outstanding immediately after this offering is based on shares of our Class A common stock outstanding as of , 2026.
The number of shares of our Class A common stock to be outstanding after this offering excludes:
| • | shares of our Class A common stock reserved for issuance upon redemption or exchange of all outstanding Common Units on a one-for-one basis; |
| • | shares of common stock issuable upon the exercise of warrants outstanding as of , 2026, with a weighted average exercise price of $ per share; and |
| • | shares of our Class A common stock reserved for future issuance under the 2026 Incentive Award Plan (the “2026 Plan”), which will become effective in connection with this offering, which number includes shares of our Class A common stock subject to restricted stock unit awards that will be granted to certain of our employees pursuant to our 2026 Plan substantially concurrently with the consummation of this offering. |
In addition, our 2026 Plan provides for annual automatic increases in the number of shares reserved thereunder.
22
Table of Contents
SUMMARY HISTORICAL AND PRO FORMA CONDENSED CONSOLIDATED FINANCIAL AND OTHER DATA
The following table shows summary historical and pro forma financial data for each of the periods indicated. The summary historical financial information for CoVolt Holdings presented below for the years ended December 31, 2025 and 2024 and for the six months ended June 30, 2026 and 2025 have been derived from the audited and unaudited financial statements of CoVolt Holdings, respectively, included elsewhere in this prospectus. The unaudited summary pro forma consolidated financial data set forth below as of June 30, 2026 and for the six months ended June 30, 2026 and for the year ended December 31, 2025 have been derived from our unaudited pro forma condensed consolidated financial statements included elsewhere in this prospectus. The results for any interim period are not necessarily indicative of the results to be expected for the full fiscal period.
The unaudited pro forma condensed statement of operations for the six months ended June 30, 2026 and the year ended December 31, 2025 gives effect to the Reorganization Transactions, entry into the Tax Receivable Agreement and this offering as if they had been consummated on January 1, 2025. The unaudited pro forma condensed statement of operations for the six months ended June 30, 2026 gives effect to the Reorganization Transactions, entry into the Tax Receivable Agreement and this offering as if they had been consummated on January 1, 2025. The unaudited pro forma condensed balance sheet as of June 30, 2026 gives effect to (i) the Reorganization Transactions, (ii) entry into the Tax Receivable Agreement and (iii) the offering (together, the “pro forma events”) as if they had been consummated on June 30, 2026. The pro forma adjustments are based on available information and upon assumptions that management believes are reasonable in order to reflect, on a pro forma basis, the effect of the pro forma events on our historical financial information. The adjustments are described in the notes to the unaudited pro forma condensed balance sheet and the unaudited pro forma condensed statements of operations. The unaudited pro forma condensed financial information is presented for illustrative purposes only and does not purport to represent the results of operations or the financial position that would actually have occurred had the pro forma events been consummated on the dates assumed or to project the Company’s results of operations or financial position for any future date or period.
The summary information in the following tables should be read in conjunction with “Basis of Presentation–Organizational Structure,” “Capitalization,” “Management’s Discussion and Analysis of Financial Condition and Results of Operations of CoVolt Holdings,” “Unaudited Pro Forma Condensed Consolidated Financial Information” and our financial statements and accompanying notes included elsewhere in this prospectus.
| Consolidated Statement of Operations: | Year Ended December 31, 2025 |
Pro Forma Year Ended December 31, 2025 |
Year Ended December 31, 2024 |
Six Months Ended June 30, 2026 |
Pro Forma Six Months Ended June 30, 2026 |
Six Months Ended June 30, 2025 |
||||||||||||||||||
| (in thousands) | ||||||||||||||||||||||||
| Revenue |
$ | 739,405 | $ | 442,724 | $ | 308,278 | $ | 451,379 | ||||||||||||||||
| Cost of revenue |
637,137 | 411,146 | 254,158 | 389,895 | ||||||||||||||||||||
| Gross profit |
102,268 | 31,578 | 54,120 | 61,484 | ||||||||||||||||||||
| General and administrative |
34,413 | 29,838 | 18,537 | 14,370 | ||||||||||||||||||||
| Depreciation and amortization expense |
8,040 | 8,852 | 914 | 4,429 | ||||||||||||||||||||
| Gain on disposal of assets |
69 | (165 | ) | (193 | ) | — | ||||||||||||||||||
| Operating income (loss) |
59,746 | (6,947 | ) | 34,862 | 42,685 | |||||||||||||||||||
23
Table of Contents
| Consolidated Statement of Operations: | Year Ended December 31, 2025 |
Pro Forma Year Ended December 31, 2025 |
Year Ended December 31, 2024 |
Six Months Ended June 30, 2026 |
Pro Forma Six Months Ended June 30, 2026 |
Six Months Ended June 30, 2025 |
||||||||||||||||||
| (in thousands) | ||||||||||||||||||||||||
| Other income (expense): |
||||||||||||||||||||||||
| Interest income |
1,297 | 29 | 1,614 | 445 | ||||||||||||||||||||
| Interest expense |
(654 | ) | (1,945 | ) | (279 | ) | (256 | ) | ||||||||||||||||
| Other income (expense), net |
192 | (146 | ) | (837 | ) | 363 | ||||||||||||||||||
| Net income (loss) |
60,581 | (9,009 | ) | 35,360 | 43,237 | |||||||||||||||||||
| Income tax expense(1) |
— | — | — | |||||||||||||||||||||
| Less: net attributable to non-controlling interests |
— | — | — | |||||||||||||||||||||
| Net income (loss) attributable to CoVolt Power |
$ | 60,581 | $ | $ | (9,009 | ) | $ | 35,360 | $ | 43,237 | ||||||||||||||
| Pro forma weighted-average shares used to compute pro forma net income per share(2): |
||||||||||||||||||||||||
| Basic |
||||||||||||||||||||||||
| Diluted |
||||||||||||||||||||||||
| (1) | CoVolt Holdings is a limited liability company treated as a pass-through entity for U.S. federal income tax purposes. As a result, members report the taxable income on their individual income tax returns. The Company is subject to income taxes in certain states, which amounts were not material to the consolidated financial statements. On a pro forma basis, CoVolt Power, Inc. will be subject to federal income taxes. |
| (2) | Pro forma weighted-average shares used to compute pro forma net income per share give effect to (i) the Reorganization Transactions, (ii) the exchange of all outstanding Common Units for shares of Class A common stock of CoVolt Power, Inc. on a one-for-one basis, and (iii) the issuance of shares of Class A common stock in this offering at an assumed initial public offering price of $ per share, which is the midpoint of the price range set forth on the cover of this prospectus. |
| As of December 31, 2025 Actual |
As of June 30, 2026 Actual |
As
of |
As of June 30, 2026 Pro Forma As Adjusted(3)(4) |
|||||||||||||
| (in thousands) | ||||||||||||||||
| Balance Sheet Data: |
||||||||||||||||
| Cash and cash equivalents |
$ | 140,590 | $ | 119,218 | ||||||||||||
| Total assets |
303,108 | 283,747 | ||||||||||||||
| Total debt(5) |
— | — | ||||||||||||||
| Total liabilities, excluding debt |
201,018 | 178,082 | ||||||||||||||
| Total members’/shareholders’ equity |
102,090 | 105,665 | ||||||||||||||
| (3) | The pro forma and pro forma as adjusted consolidated balance sheet data as of December 31, 2025 and June 30, 2026 gives effect to (i) the Reorganization Transactions (ii) the adoption of the Amended Charter, and (iii) the issuance of shares of Class B common stock to the Continuing Equity Owners. |
| (4) | The pro forma as adjusted consolidated balance sheet data reflects the items described in footnote (3) above and gives further effect to our receipt of estimated net proceeds from the sale of shares of Class A common stock that we are offering by this prospectus at an assumed initial public offering price of $ per share, which is the midpoint of the price range on the cover page of this prospectus, after deducting estimated underwriting discounts and commissions and estimated offering expenses payable by us. A $1.00 increase (decrease) in the assumed initial public offering price of $ per share would increase (decrease) each of cash and cash equivalents, total assets and total members’/shareholders’ equity by $ million, assuming that the number of shares offered by us, as set forth on the cover page of this prospectus, remains the same, and after deducting estimated underwriting discounts and commissions and estimated offering expenses payable by us. The pro forma as adjusted data discussed above is illustrative only and will be adjusted based on the actual initial public offering price and other terms of our initial public offering determined at pricing. We will not receive any proceeds from the sale of shares of our common stock by the selling shareholders. |
24
Table of Contents
| (5) | As of June 30, 2026, the Company had no revolving borrowings outstanding under the Revolving Credit Agreement, $4.7 million of letters of credit outstanding, and $55.3 million of remaining availability thereunder. |
Other Financial and Operational Data
In addition to the measures presented in our consolidated financial statements, we use the following non-GAAP financial and operational data to evaluate our business, measure our performance, develop financial forecasts, and make strategic decisions.
| Six Months Ended June 30, 2026 |
Six Months Ended June 30, 2025 |
Year Ended December 31, 2025 |
Year Ended December 31, 2024 |
|||||||||||||
| (dollars in millions) |
||||||||||||||||
| Revenue |
$ | 308.3 | $ | 451.4 | $ | 739.4 | $ | 442.7 | ||||||||
| Gross profit |
54.1 | 61.5 | 102.3 | $ | 31.6 | |||||||||||
| Net income |
35.4 | 43.2 | 60.6 | (9.0 | ) | |||||||||||
| Adjusted EBITDA(1) |
42.3 | 53.2 | 80.5 | 17.0 | ||||||||||||
| Adjusted EBITDA Margin(2) |
13.7% | 11.8% | 10.9% | 3.8% | ||||||||||||
| Free Cash Flow(3) |
5.5 | (7.6 | ) | 77.8 | 72.0 | |||||||||||
| Backlog(4) |
3,614 | 709 | 1,684 | 1,198 | ||||||||||||
| (1) | We define Adjusted EBITDA as net income (loss) attributable to CoVolt Holdings Group, LLC before (i) interest expense (income), net, (ii) provision for income taxes, (iii) depreciation and amortization, (iv) non-cash compensation expense, (v) retention and recruiting costs associated with our management transition, (vi) costs associated with our organizational transformation and strategic review, (vii) costs associated with the wind-down of our non-core operations, (viii) legal settlements and (ix) costs incurred in connection with this offering. Adjusted EBITDA is a non-GAAP financial measure. See “Management’s Discussion and Analysis of Financial Condition and Results of Operations–Non-GAAP Financial Measures” for additional information about Adjusted EBITDA and for a reconciliation to net income (loss), the most directly comparable U.S. GAAP financial measure. |
| (2) | We define Adjusted EBITDA Margin as Adjusted EBITDA divided by revenue. We use Adjusted EBITDA Margin to evaluate the efficiency with which we convert revenue into Adjusted EBITDA, and we believe this metric is useful to investors and analysts in assessing our operating performance and comparing it against that of other companies in our industry. |
| (3) | We define Free Cash Flow as net cash provided by operating activities less purchases of property and equipment (capital expenditures). Free Cash Flow is a non-GAAP financial measure. See “Management’s Discussion and Analysis of Financial Condition and Results of Operations–Non-GAAP Financial Measures” for additional information about Free Cash Flow and for a reconciliation to net cash provided by (used in) operating activities, the most directly comparable U.S. GAAP financial measure. |
| (4) | We define Backlog as the estimated revenue we expect to realize from the remaining transaction price on projects that have been awarded to us or for which we have signed contracts. Backlog is comprised of Signed Backlog and Awarded Backlog and is not a measure defined by U.S. GAAP; accordingly, our methodology for determining Backlog may not be comparable to methodologies used by other companies in determining their backlog amounts. See “Risk Factors–Risks Related to Our Business–Our backlog may not be realized or may not result in profits, and may not accurately represent future revenue.” |
25
Table of Contents
Table of Contents
Investing in our Class A common stock involves a high degree of risk. You should carefully consider and read the following risk factors, together with all of the other information contained in this prospectus, including the section titled “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and our consolidated financial statements and related notes thereto, before deciding to invest in our Class A common stock. The risks described below are not the only ones we face. Our business, financial condition, and/or results of operations could be materially and adversely affected by any of these risks or uncertainties, as well as by risks or uncertainties not currently known to us, or that we do not currently believe are material. In such case, the trading price of our Class A common stock could decline, and you may lose some or all of your investment.
Risks Related to Our Business
Our projects depend on the timely performance of customers, suppliers, subcontractors, and other third parties, and delays or failures by these parties, as well as engineering errors, permitting issues, and other factors, can negatively impact our project schedules, costs, and profitability.
Our business is dependent on successfully constructing utility-scale solar, battery storage, and high voltage (e.g., substations, switchyards, transmission, etc.) projects for our customers on time and within budget. Many of our projects involve challenging engineering, permitting, interconnection, procurement, and construction phases that occur over extended time periods, and we have encountered and may in the future encounter project delays, additional costs, or project performance issues as a result of factors that are beyond our control or due to errors in our work.
These factors and other issues affecting our performance include, among others: engineering errors; damaged equipment or late delivery of equipment; supply chain constraints; inability to meet project schedule requirements or achieve guaranteed performance or quality standards, which can result in increased costs through rework or the payment of liquidated damages to our customers; failure to accurately estimate project costs or establish the scope of our services; unforeseen circumstances or project modifications not included in our cost estimates or covered by our contracts, including concealed or unknown environmental, geological, or site conditions; changes in laws, including additional restrictions, reductions, or repeal of tax credits and other tax or governmental benefits our customers expect to generate with respect to their energy projects; ability to source equipment, components, and intellectual property from non-prohibited foreign entity suppliers in order to maintain eligibility for tax benefits; permitting, interconnection, or regulatory requirements during the course of our work; delays in the delivery of design or engineering information, equipment, or materials; our or our customers’ failure to timely obtain land, permits, rights of way, or other regulatory or environmental approvals; changes to project or customer schedules; and delays or failures to perform by suppliers, subcontractors, or other third parties. For example, certain equipment such as transformers are sensitive to impacts, or solar modules do not produce the expected power output, but no physical damage is visible upon our receipt of the particular equipment item at the site. When those items are put into service, they do not perform properly or fail prematurely. The cause is not always readily ascertainable, which can result in expensive and time-consuming testing, ultimately resulting in disputes over causation.
The successful completion of the majority of our projects is dependent on the timely delivery of customer/owner furnished materials and equipment (e.g., PV modules, inverters, trackers, etc.) and such projects may be delayed or disrupted if such customer/owner furnished materials and equipment are not delivered in accordance with the agreed delivery dates. Our projects may also be delayed or disrupted by protests and other public activism, legal challenges, or other political opposition; geopolitical conflicts; public health crises such as pandemics or epidemics; government shutdowns or under-staffing of regulatory agencies; and changes in the
27
Table of Contents
cost, availability, lead times, or quality of equipment, commodities, materials, or labor. Many of these difficulties and delays, although not caused by us, can negatively impact our ability to complete a project in accordance with the required delivery schedule or performance requirements, or achieve our anticipated operating income margin on the project. When delays occur on a project, there are often disputes over the true causation of the delay or the extent of delay attributable to each party. Even where we believe a delay is excusable and compensable under our contract, customers may disagree, and if we are successful in obtaining relief via a change order, such relief may not fully cover our actual costs. If the customer refuses to grant time extensions to guaranteed contract milestones, we may be forced to mitigate the delays by working out-of-sequence, working overtime, or adding additional labor and construction equipment resources to accelerate our work, which results in losses of labor productivity and increased costs, which may not be recoverable from the customer. We have also experienced delays because the customer is unable to provide backfeed power in accordance with the agreed schedule, which has caused delays to commissioning activities resulting in delays to substantial completion dates. In some cases, to mitigate the delay caused by the late provision of backfeed power, we have brought in generators and load banks at significant additional cost to allow commissioning to proceed in the absence of backfeed power.
Delays and additional costs associated with these factors may be substantial and not recoverable from the customer or third parties, and in some cases, we may be required to compensate our customers for such delays. Many of our EPC contracts include provisions requiring us to pay liquidated damages to our customers if we fail to achieve guaranteed dates such as substantial completion or mechanical completion, which guaranteed dates are often by circuit or other project milestone, or if the project does not meet certain performance guarantees (e.g. guaranteed capacity). These liquidated damages can be significant and can substantially reduce or eliminate the profit margin on a project, or even result in a loss. Furthermore, if we are required to pay liquidated damages or fail to meet performance standards, our customers may terminate our contracts, seek actual damages, or decline to award us future work, any of which could damage our reputation in the industry. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations. For example, we have experienced situations where the customer supplied solar modules do not produce the power output guaranteed by the manufacturer, resulting in disputes over the causation of the project not achieving guaranteed performance/power production.
Adverse weather, natural disasters, and difficult site conditions can disrupt our construction activities, increase our costs, and delay project completion.
Unlike commercial building projects, utility-scale solar and battery storage projects are performed almost entirely outdoors and are subject to disruption from weather events, natural disasters, and emergencies, including wildfires, earthquakes, hurricanes, tropical storms, tornadoes, significant rainfall, floods, hailstorms, droughts, blizzards, lightning strikes, and extreme temperatures. We have experienced hail, lightning strikes, wildfires, windstorms, floods, extreme temperatures, and extreme rain on our projects. Solar panels are susceptible to certain weather-related risks: during installation, solar panels can catch wind like sails, causing high winds to shut down or delay construction activities, and large hail can significantly damage solar panels, causing delays and reconstruction risks. Weather conditions such as prolonged rainfall or snowfall, early thaw in northern regions, high winds, and extreme temperatures can halt or disrupt construction activities for extended periods and negatively impact our ability to complete projects within budget or on schedule, which increases our costs and may expose us to delay liquidated damages. Difficult terrain, mud, and other site conditions can also impact the delivery and distribution of materials, availability of labor, and exposure of our personnel to harsh and hazardous conditions.
When sites are particularly muddy, wet, or snow covered, we may need to double-handle materials, which increases our costs. For example, we plan our work so that when materials such as piles and modules are delivered to the site, we offload them in the field near where the materials will be installed; however, if the site
28
Table of Contents
conditions do not permit offloading in the field, we must store them in a construction yard until conditions improve and then later distribute the materials to the field locations where they will be used. Working in harsh conditions such as extreme heat, cold, or mud lowers production rates, increases costs, and causes delays. Despite contractual protections such as force majeure provisions and insurance coverage, we have not always recovered the costs we have incurred from weather events and adverse site conditions, which has negatively impacted our financial results. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
We generate a significant portion of our revenues from lump sum contracts, and if actual project costs exceed our estimates, we may experience reduced profits or losses.
A substantial portion of our revenues is generated from EPC contracts structured on a lump sum basis, under which we agree to complete a defined scope of work for a lump sum. Under lump sum contracts, we bear the risk that the actual cost of labor, materials, equipment, and other project inputs may exceed our estimates, which could result in reduced profit margins or losses on a project.
When we enter into lump sum contracts, we must estimate the costs we expect to incur in performing the required work, including the costs of labor, materials, equipment, subcontractors, permits, insurance, and overhead. These cost estimates are based on our experience with similar projects, our understanding of the project scope and specifications, prevailing market conditions, geographic location, and various assumptions about future cost trends and project execution. However, utility-scale solar, battery storage, and high voltage projects are complex, involve long construction periods, and are subject to numerous uncertainties that can cause actual costs to differ significantly from our estimates.
Factors that may cause our actual costs to exceed our estimates include, among others: unanticipated increases in the cost of labor, materials, equipment, or subcontractor services due to inflation, supply chain disruptions, tariffs, commodity price volatility, or other market conditions; inaccurate estimates of the quantities of labor, materials, or equipment required to complete the work; unanticipated site conditions, including unforeseen environmental, geological, differing site conditions or unknown/unforeseen subsurface conditions; errors or deficiencies in engineering designs, drawings, or specifications; changes in applicable laws, regulations, codes, or permitting requirements; delays caused by adverse weather, natural disasters, or other force majeure events; delays or failures by our customers, suppliers, subcontractors, or other third parties to perform their obligations, including the supply of defective or damaged materials and equipment; and labor shortages, strikes, work stoppages, or other labor disruptions. Utility-scale solar projects encompass vast areas of land. Our project sites are usually over 1,000 acres. The customers provide geological reports, including soil borings, but such reports are limited and cannot practically identify all conditions on such large tracts of land that we may discover in the performance of our work. If the actual subsurface conditions are materially different from the conditions reflected in the contract documents or those conditions reasonably identified from our site visits, our costs to complete the work can be substantially more than we estimated in our bid. For example, we can and have encountered sinkholes, underground springs/water flow, unknown rock formations, and man-made structures such as buried concrete foundations, concealed wells, drainage tile, and structures. These items can change, and have changed, our design and work plans, sometimes requiring drilling through rock, or the removal of such items, and even requiring a different foundation design or different layout of the solar array to avoid such unforeseen conditions. Additionally, depending on the manufacturer, module model, and type, the wattage, size, and weight of solar modules may differ. To meet performance guarantees, the number of modules and plant layout may need to change, as well as the tracker and foundation design. As the EPC contractor, we provide a lump sum price based on an incomplete design and make certain assumptions on quantities. If we change the design or the assumptions we used in estimating bid quantities prove inaccurate, there can be, and we have experienced, significant quantity growth for which we are responsible. Significant quantity growth can and has caused cost increases in both materials and the labor to install the additional
29
Table of Contents
quantities, negatively impacting anticipated project margins. We have installed defective or damaged materials and equipment, which showed no signs of physical damage, but such defects were not discovered until plant testing and start-up. This can cause rework and delays in achieving guaranteed milestone dates.
In addition, under lump sum contracts, we are typically responsible for cost overruns even if those overruns result from factors beyond our control or that we could not reasonably have anticipated at the time we entered into the contract, unless the contract provides relief for such factors and conditions. While our contracts may include change order provisions that allow us to recover additional costs under certain circumstances, we may not be successful in obtaining change orders or recovering the full amount of our cost overruns. Disputes with customers regarding change orders and cost recovery can be time-consuming, costly, and damaging to customer relationships, and may result in arbitration or litigation. Furthermore, we use the percentage-of-completion method to recognize revenue on our lump sum contracts, which requires us to estimate the total costs expected to be incurred over the life of the contract. If we underestimate the total costs of a contract, we may be required to recognize lower profits or losses in future periods as the project progresses, which could have a material adverse effect on our financial results for those periods. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
Limitations on the availability, or increases in the price, of solar modules, inverters, racking systems, transformers, and other critical equipment, as well as qualified subcontractors, could delay projects and have a material adverse effect on our business and results of operations. For example, the availability of power transformers utilized in electric power plants has been negatively impacted by the inability of manufacturers to meet current market demand, which has increased and is expected to continue to increase. If the supply of power transformers and other critical equipment is unable to meet the demand for such equipment, prices and lead times may continue to increase which could put upward pressure on our costs and adversely affect our profitability. Also, it is not uncommon for customers to change module types or module manufacturers/suppliers after signing an EPC agreement, which can result in a significant redesign of the project to accommodate the different modules. The redesign resulting from the module change is the basis of a change order, but the customers do not always agree to the amount of delay, disruption and additional costs attributed to the module change. Moreover, dependent upon the timing of the module change and any delays in the delivery of the modules, work planned to be performed in favorable weather months can be pushed into winter months resulting in series of cascading delays and cost impacts.
Concentration of customers, specific projects and regions may expose us to heightened financial exposure.
Our business model currently relies on a limited number of customers for a significant portion of our revenues, and we expect this customer concentration to continue for the foreseeable future. For example, our largest customer accounted for approximately 20% of our consolidated revenues and our top ten customers collectively represented approximately 96% of our consolidated revenues for the fiscal year ended December 31, 2025. For the six months ended June 30, 2026, our largest customer represented approximately 45% of our total revenues and our two largest customers collectively represented approximately 59% of our total revenues. The financial performance of our business depends on the ability of each customer to continue to award us projects and to perform its obligations under our EPC contracts. Our financial results could be materially and adversely affected if any of our significant customers fail to fulfill their contractual obligations, reduce or discontinue business with us, or if we are unable to replace lost business on comparable terms. We cannot assure that such performance failures or reductions in business by our customers will not occur, or that if they do occur, such failures will not adversely affect the cash flows or profitability of our business. Moreover, there can be no assurance that we will be able to enter into replacement contracts on favorable terms or at all.
We do not have long-term volume commitments from our customers, and our EPC contracts are typically awarded on a project-by-project basis following competitive bidding processes. Our significant customers
30
Table of Contents
include solar energy and battery storage developers, independent power producers, utilities, and infrastructure-backed platforms that are active in the utility-scale solar and battery storage markets. A significant customer may unilaterally reduce or discontinue business with us at any time or merge with, or be acquired by, a company that decides to reduce or discontinue business with us. Consolidation in the solar energy and battery storage development industry has been ongoing, with larger developers acquiring smaller competitors and private equity and infrastructure funds becoming increasingly active acquirers of development platforms. When a customer is acquired or undergoes a significant change in ownership, the new owners may elect to use different EPC contractors with whom they have existing relationships, may decide to self-perform construction services, or may discontinue projects that were previously in our pipeline.
Our project sites are located across diverse geographic regions throughout the United States, exposing our operations to a wide range of climate, weather, regulatory, and economic conditions. For the year ended December 31, 2025, our solar EPC operations generated approximately $643 million in revenues, representing approximately 87% of our consolidated revenues, and our high-voltage T&D operations generated approximately $96 million in revenues, representing approximately 13% of our consolidated revenues. Because our revenues are concentrated in the utility-scale solar and battery storage EPC market, our business and results of operations are particularly susceptible to adverse economic, regulatory, permitting, political, weather, and other conditions affecting these markets. Any of these conditions could have a material adverse effect on our business, financial condition, and results of operations.
We are also exposed to the credit and financial condition of our customers. A significant customer may encounter financial constraints, based on cost of capital or other reasons, file for bankruptcy protection, or cease operations, any of which could result in reduced or discontinued business with us. The solar energy and battery storage development industry is capital-intensive, and our customers’ ability to continue their project development activities depends on their access to tax equity, debt financing, and equity capital. Volatility in capital markets, rising interest rates, or changes in the availability, reductions, limitations, or repeal of tax credits or other tax or governmental benefits could impair our customers’ financial condition and their ability to proceed with projects. While we have longstanding relationships with many of our significant customers, long-term exposure to a concentrated customer base remains a risk, and any loss of, or significant reduction in business from, one or more of these customers could have a material adverse effect on our business, financial condition, and results of operations.
The imposition of tariffs, duties, and other trade barriers could increase our costs, disrupt supply chains, and have a material adverse effect on our business.
The construction of utility-scale solar and battery storage projects requires significant quantities of equipment and materials, including solar modules, inverters, racking systems, transformers, battery cells, and other components, many of which are manufactured outside the United States. Our EPC contracts often require us to procure some or most of the materials and equipment needed for a project, and our costs and ability to complete projects on time and within budget can be materially affected by tariffs, duties, taxes, assessments, sourcing restrictions, and other trade barriers imposed by the U.S. government or foreign governments.
Recently, there have been significant changes to U.S. trade policies, including substantial new tariffs on foreign imports. In early 2025, the U.S. presidential administration announced significant new tariffs on imports from China, Mexico, Canada, and certain Southeast Asian countries, and has proposed additional new tariffs that may be implemented in the future. Solar modules, inverters, battery storage systems, and other critical equipment used in our projects are frequently manufactured in or sourced from these countries. The extent and duration of increased tariffs, and the resulting impact on general economic conditions and on our business, are uncertain and depend on various factors, including negotiations between the U.S. and affected countries, the responses of
31
Table of Contents
other countries or regions, exemptions or exclusions that may be granted, and the availability and cost of alternative sources of supply.
Any new or additional tariffs on goods imported into the U.S. from China, Southeast Asia, or other countries could significantly increase the cost of equipment and materials used in our projects. Our EPC contracts generally include change order provisions that entitle us to compensation for new or increased tariffs that take effect after we sign the EPC contract, similar to change order provisions for changes in law. However, even where we have contractual entitlement to a change order, our customers may dispute the amount of compensation owed, and we may be unable to recover the full amount of our increased costs. Disputes over tariff-related cost increases could damage our customer relationships. In response to tariffs, we may seek to increase prices to customers on new contracts, which may diminish demand for our services and could have a material adverse effect on our competitive position.
Additionally, tariffs and trade restrictions can disrupt supply chains by limiting the availability of critical equipment and materials or extending lead times for delivery. If we are unable to procure necessary equipment in a timely manner, our projects may be delayed, which could result in liquidated damages, contract terminations, or reputational harm. Other countries have changed, and may continue to change, their own policies on trade as well as business and foreign investment in response to U.S. trade actions, which could further disrupt global supply chains for solar and battery storage equipment. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
Our business is labor-intensive, and we may be unable to attract and retain qualified electricians, project managers, engineers, and other skilled personnel, or may incur significant costs if the cost of labor increases. Additionally, our collective bargaining agreements and multiemployer pension plan obligations could have a material adverse effect on our business.
Our ability to perform our EPC services and grow our business requires hiring, training, and retaining the necessary skilled personnel, which is subject to a number of risks. The demand for labor in our industry has continued to increase in response to growing demand for infrastructure services in the United States related to the energy transition. The pool of skilled workers available in our industry has declined, and may further decline, especially with respect to experienced project managers, qualified engineers, electricians, and craft workers. The amount of travel or relocation required for project management-level positions can impact the number of qualified potential candidates that decide to enter our industry.
A shortage in the supply of personnel creates competitive hiring markets that may result in increased labor expenses, and we have incurred, and expect to continue to incur, significant recruiting and training expenses in order to recruit and train employees. The uncertainty of contract award timing and project delays can also present difficulties in managing our workforce size. Our inability to efficiently manage our workforce may require us to incur costs resulting from excess staff, reductions in staff, or redundancies. Additionally, inflationary pressure in the United States has increased our labor costs, and under certain of our lump sum contracts, we may be unable to pass these increased costs through to our customers. Increased labor costs can also impact our customers’ decision-making with respect to viability or timing of certain projects, which could result in project delays or cancellations. We may also trigger indemnification obligations to our customers if, on projects where we have agreed to comply with certain tax credit eligibility obligations, including the prevailing wage and apprenticeship standards, FEOC requirements or domestic content standards, we fail to do so and this causes our customers to lose tax credit eligibility or bonus federal tax credits under the Inflation Reduction Act of 2022 or the OBBBA.
A portion of our workforce is represented by labor unions and we have signed project labor agreements with such unions limited to the specific applicable project and those project labor agreements incorporate certain provisions of broader collective bargaining agreements, which require us to pay specified wages, provide
32
Table of Contents
certain benefits, and comply with various work rules and conditions. Although the majority of our project labor agreements with the various labor unions prohibit strikes and work stoppages, unionized employees have been known to ignore such provisions; thus, work stoppages could occur in the future. Union organizing activities could also result in additional portions of our workforce becoming unionized, which could increase our labor costs and reduce our operational flexibility.
Our collective bargaining agreements generally require us to participate with other companies in multiemployer pension plans. To the extent a plan is underfunded, we may be subject to substantial liabilities under the Employee Retirement Income Security Act of 1974 (“ERISA”), as amended by the Multiemployer Pension Plan Amendments Act of 1980, if we withdraw or are deemed to withdraw from the plan or the plan is terminated or experiences a mass withdrawal. The amount of any such withdrawal liability could be material. Further, the Pension Protection Act of 2006 added special funding and operational rules generally applicable to multiemployer plans that are classified as “endangered,” “seriously endangered,” or “critical” status based on multiple factors. Plans in these classifications must adopt remedial measures, which may require additional contributions from employers and/or modifications to retiree benefits. Certain plans to which we contribute or may contribute in the future have these funding statuses, and we may be obligated to contribute material amounts to these plans in the future. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
The loss of, or reduction in business from, significant customers could have a material adverse effect on our business, financial condition, and results of operations.
A limited number of customers have historically accounted for a significant portion of our revenues, and we expect this customer concentration to continue for the foreseeable future. For example, our largest customer accounted for approximately 20% of our consolidated revenues and our top ten customers collectively represented approximately 96% of our consolidated revenues for the fiscal year ended December 31, 2025. For the six months ended June 30, 2026, our largest customer represented approximately 45% of our total revenues and our two largest customers collectively represented approximately 59% of our total revenues. Our significant customers include solar energy and battery storage developers, independent power producers, utilities, and infrastructure-backed platforms that are active in the utility-scale solar and battery storage markets. Although we have longstanding relationships with many of our significant customers, the loss of business from, or a significant reduction in business with, one or more of these customers could have a material adverse effect on our business, financial condition, and results of operations.
A significant customer may unilaterally reduce or discontinue business with us at any time or merge with, or be acquired by, a company that decides to reduce or discontinue business with us. Consolidation in the solar energy and battery storage development industry has been ongoing, with larger developers acquiring smaller competitors and private equity and infrastructure funds becoming increasingly active acquirers of development platforms. When a customer is acquired or undergoes a significant change in ownership, the new owners may elect to use different EPC contractors with whom they have existing relationships, may decide to self-perform construction services, or may discontinue projects that were previously in our pipeline. We may also lose key customer relationships if personnel with whom we have established working relationships depart following such transactions.
A significant customer may also encounter financial constraints, based on cost of capital or other reasons, file for bankruptcy protection, or cease operations, any of which could result in reduced or discontinued business with us. The solar energy and battery storage development industry is capital-intensive, and our customers’ ability to continue their project development activities depends on their access to tax equity (or tax credit monetization options, such as transfers of tax credits), debt financing, and equity capital. Volatility in capital markets, rising interest rates, or changes in the availability, reductions, limitations, or repeal of tax credits or other tax or governmental benefits could impair our customers’ financial condition and their ability to proceed
33
Table of Contents
with projects. In the past, solar energy and battery storage developers and project owners have experienced bankruptcies, restructurings, and program cancellations, and similar events could affect our current or prospective customers.
Furthermore, our significant customers may shift their strategic priorities, such as moving away from utility-scale solar toward distributed generation, offshore wind, or other technologies, which could reduce their demand for our EPC services. Our customers may also face pressure from their own investors or lenders to reduce costs, which could lead them to delay projects, reduce project scope, or seek lower-cost EPC alternatives. We do not have long-term volume commitments from our customers, and our EPC contracts are typically awarded on a project-by-project basis. There can be no assurance that we will continue to receive significant business from our current customers at historical levels, or at all. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
Many of our contracts may be canceled, suspended, or not renewed on short notice, and we may be unsuccessful in replacing such contracts.
Our EPC contracts typically do not obligate our customers to undertake any volume of business with us and, in most cases, may be terminated or suspended by our customers on short notice even if we are not in default under the contract. Many of our contracts contain termination for convenience provisions that allow customers to terminate our engagement upon 3 to 10 business days’ notice. Upon a termination for convenience, customers are generally required to pay us for work performed through the termination date, materials procured or committed, reasonable demobilization costs, and subcontractor and supplier cancellation charges; however, our contracts generally do not provide for recovery of lost profits on unperformed work. Such payments may not fully compensate us for the loss of the anticipated project revenue and profit margin, and we may be left with unrecoverable costs associated with mobilization, procurement commitments, and workforce planning. Our LNTP agreements are similarly terminable, and customers are not obligated to proceed from the LNTP phase to a full EPC contract. For additional information regarding our contract terms, see “Business–Customer Contracts.”
Customers may cancel, suspend, or fail to renew contracts for a variety of reasons, many of which are beyond our control. These reasons include changes in the customer’s project economics or financing arrangements; reduction, repeal, or increased restrictions on tax credits or other tax or governmental benefits; permitting delays or denials; grid interconnection issues or delays in obtaining power purchase agreements; changes in the customer’s strategic priorities or development pipeline; consolidation or change of control of the customer; adverse regulatory or policy developments affecting the solar energy and battery storage industry; and general economic conditions affecting the customer’s business. Customers may also reduce the scope of projects or defer commencement of construction, which can significantly reduce the revenue we expected to recognize from a contract.
Our EPC contracts are negotiated on a project-by-project basis, as every project is unique, and do not renew. We do not have long-term volume commitments from our customers, and our EPC contracts are typically awarded following competitive bidding processes. Even customers with whom we have longstanding relationships may elect to use other EPC contractors for future projects based on price, availability, geographic considerations, or other factors. Additionally, repeat customers may seek to renegotiate contract provisions to shift additional risk to us. If we are unwilling to accept such additional risk, we may lose the project to a competitor willing to accept less favorable terms. There can be no assurance that we will continue to receive work from our current customers at historical levels, or at all.
Our inability to replace canceled, suspended, or non-renewed contracts with new business at comparable margins could result in periods of reduced revenue and underutilization of our workforce and equipment. We may incur significant costs in maintaining our workforce and operational capacity during periods of reduced
34
Table of Contents
project activity, which could negatively impact our profitability. Furthermore, contract cancellations or suspensions can disrupt our project scheduling and resource allocation, making it more difficult to efficiently manage our operations across multiple projects. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
We may fail to adequately recover on contract modifications, change orders, or claims against customers, which could reduce our revenues and profitability.
During the course of constructing utility-scale solar, and battery storage, and high voltage projects, we frequently encounter circumstances that require modifications to the original contract scope, specifications, or requirements. We periodically present contract modifications to our customers for changes in contract specifications or requirements, as a result of added scope under such contracts, or for events outside our control which have impacted the cost or time to perform our obligations under the contracts. These circumstances may include, among other things, unforeseen site conditions such as unknown environmental, geological, or subsurface conditions; delays caused by customers, subcontractors, or other third parties; changes in project scope requested by our customers; damage to materials and equipment, permitting delays or changes in regulatory requirements; significant weather events or natural disasters; and supply chain disruptions affecting the cost or availability of materials and equipment.
We consider unapproved change orders to be contract modifications for which customers have not yet agreed to both scope and price. We consider claims to be contract modifications which have been denied by our customers, and for which we seek, or will seek, to collect from such customers. While we generally negotiate with our customers for additional compensation when we incur costs or delays attributable to factors beyond our control or outside the original contract scope, we may be unable to obtain, through negotiation, arbitration, litigation, or otherwise, adequate amounts to compensate us for the additional work performed or expenses incurred. For example, we have experienced conditions beyond our control that our customers recognize that we are entitled to compensation (time and money) such as unforeseen subsurface conditions like buried concrete foundations or extreme weather conditions, but customers are unwilling to fully compensate us for either the full cost or the actual delay.
The process of resolving change orders and claims can be lengthy, costly, and contentious. Litigation or arbitration with respect to these matters is generally time-consuming and expensive, involves significant uncertainty as to the timing and amount of any resolution, and can adversely affect our relationships with existing or potential customers. Even where we believe we have strong legal grounds for recovery, customers may dispute our entitlement to additional compensation, challenge the reasonableness of our claimed costs, or assert counterclaims against us. Furthermore, we could be required to invest significant working capital to fund cost overruns while the resolution of a claim is pending, which can strain our liquidity and financial resources.
We recognize amounts associated with change orders and claims as revenue when it is probable that a significant reversal in the amount of cumulative revenue recognized will not occur or when the uncertainty associated with the variable consideration is resolved. Actual amounts collected in connection with change orders and claims have in the past and may in the future differ from estimated amounts. Consequently, the timing for recognition of revenues and profit or loss and any subsequent changes in estimates is uncertain and could result in a reduction or an elimination of previously reported revenues or profits, or the recognition of losses on the associated contract. Failure to obtain adequate and prompt compensation for change orders and claims can result in a material reduction of revenues and gross profit, or the recognition of significant losses on affected projects. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
35
Table of Contents
The nature of our EPC business exposes us to potential liability for warranty, engineering, design defects, construction quality, and performance guarantee claims that could have a material adverse effect on our financial condition.
As an EPC contractor for utility-scale solar, battery storage, and high voltage projects, we are responsible for delivering completed projects that meet specified performance standards, quality requirements, and design specifications. Our EPC contracts typically include warranties covering our workmanship and the materials we supply for periods ranging from one to several years following project substantial completion. We may also provide performance guarantees related to energy production, system availability, or other operational metrics. If the projects we construct fail to meet warranted quality standards or guaranteed performance levels, we may be required to perform corrective work, replace defective materials or equipment, pay damages to our customers, or provide other remedies at our expense.
The construction of utility-scale solar and battery storage projects involves complex engineering, design, and construction activities that carry inherent risks of defects or deficiencies. These risks include errors or omissions in engineering designs or construction drawings; improper installation of solar modules, inverters, racking systems, electrical components, or battery storage equipment; defects in materials or equipment supplied by us or our subcontractors; failure of installed systems to achieve expected energy production or efficiency levels; and latent defects that may not become apparent until after project completion. Additionally, we may be held responsible for defects in work performed by our subcontractors or for defects in equipment or materials supplied by third-party vendors, even if we did not directly cause such defects.
Performance guarantee claims can be particularly significant in the utility-scale solar and battery storage industry, where project economics are highly sensitive to energy production levels. Our customers often enter into power purchase agreements or receive financing based on projected energy output, and shortfalls in actual performance can have substantial financial consequences for them. If a project we construct fails to meet guaranteed performance levels, we may be required to pay liquidated damages, make capital improvements to enhance system performance, or provide other remedies that could be costly and time-consuming.
Furthermore, warranty and performance guarantee claims can arise years after project completion, making it difficult to predict our ultimate exposure. We establish reserves for warranty obligations based on historical experience and management estimates, but actual warranty costs may exceed our reserves. We also maintain insurance coverage for certain types of claims, but our insurance may not cover all potential liabilities, and coverage limits may be insufficient to fully protect us against significant claims. Warranty, design defect, construction quality, or performance guarantee claims, whether or not ultimately determined to be our responsibility, could damage our reputation in the industry and adversely affect our ability to win new business. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
We can incur liabilities or suffer negative financial or reputational impacts relating to health and safety matters inherent in large-scale solar and battery storage construction operations, including risks of worksite injuries and fatalities.
The construction of utility-scale solar, and battery storage, and high voltage projects involves inherently hazardous activities that expose our employees, subcontractors, and other personnel to significant health and safety risks. Our construction operations involve working at heights, operating heavy machinery and equipment, electrical work including high-voltage systems, excavation and trenching, lifting and rigging operations, and exposure to extreme weather conditions. These activities create risks of serious injuries and fatalities, including falls, electrocution, struck-by incidents, crushing injuries, heat-related illnesses, and other workplace accidents. Construction activities are performed in an environment that is difficult to control and thus, there is a potential for serious accidents in the future.
36
Table of Contents
Battery storage projects present unique health and safety risks beyond those associated with traditional solar construction. Lithium-ion battery systems, which are commonly used in utility-scale battery storage projects, can experience thermal runaway events that may result in the melting of materials, fires, explosions, or the release of toxic gases. Our personnel may be exposed to hazardous materials during the installation, commissioning, and maintenance of battery storage systems. As the battery storage market continues to grow and evolve, we may encounter new or unanticipated safety risks associated with emerging battery technologies or installation methods.
Our operations are subject to extensive federal, state, and local laws and regulations governing occupational health and safety, including the Occupational Safety and Health Act and regulations promulgated by the Occupational Safety and Health Administration. We are required to maintain comprehensive safety programs, provide training to our employees, and comply with detailed safety standards applicable to construction activities. Violations of these requirements can result in significant penalties, citations, and in serious cases, criminal prosecution of responsible individuals. We may also be subject to stop-work orders or other regulatory actions that could delay our projects and increase costs.
Workplace accidents and acts of violence can result in substantial liabilities, including workers’ compensation claims, third-party personal injury or wrongful death lawsuits, property damage claims, and regulatory fines and penalties. We have experienced two active shooter events, one at an office location and one at a project site, and there can be no assurance that similar incidents will not occur in the future. We maintain insurance coverage for certain workplace liabilities, but our insurance may not cover all potential claims, and coverage limits may be insufficient to fully protect us against significant losses. Additionally, workplace accidents can damage our reputation, impair our ability to attract and retain qualified employees, and adversely affect our relationships with customers who prioritize safety performance when selecting EPC contractors. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
Our high-voltage substation, T&D, and data center services present distinct risks that could adversely affect our business, financial condition, and results of operations.
Our high-voltage platform, which includes substation construction, T&D infrastructure, and high-voltage work for data center interconnections, involves work on or adjacent to energized grid infrastructure and is subject to more stringent regulatory requirements (including NERC and Federal Energy Regulatory Commission (“FERC”) standards) than our solar and storage EPC work. Errors in high-voltage design or construction can result in equipment damage, power outages, grid disturbances, and regulatory penalties that may significantly exceed the contract value. Skilled high-voltage electricians and high-voltage engineers are scarce, and our ability to execute this work depends on maintaining a specialized, licensed workforce. Our data center customers are a small number of large hyperscale technology companies whose construction programs are subject to rapid changes in capital allocation. A slowdown in hyperscaler capital expenditures or a shift in preferred contractors could significantly reduce demand for this part of business. As of June 30, 2026, approximately 6% of our total backlog consisted of high-voltage substation and T&D work for data center customers. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
We are subject to litigation, claims, and legal proceedings in the ordinary course of our business, including personal injury claims, breach of contract disputes, and bonding claims, which could result in significant liabilities and divert management attention.
We are, and may in the future become, subject to various lawsuits, claims, and legal proceedings arising in the ordinary course of our business, including claims for personal injury or wrongful death, breach of contract, professional liability, employment-related disputes, and claims by subcontractors and suppliers. The
37
Table of Contents
construction industry generally, and the utility-scale solar and battery storage construction industry specifically, involves significant risks of liability due to the nature of the work performed, the large number of personnel involved, and the complex contractual relationships among project participants.
Personal injury and wrongful death claims may arise from accidents at our construction sites, including claims by our employees, employees of our subcontractors, and third parties. Although we maintain workers’ compensation insurance and general liability insurance, the cost of defending against such claims, and any settlements or judgments, could be substantial and may exceed our insurance coverage. Employment-related claims may include allegations of discrimination, harassment, retaliation, wrongful termination, worker misclassification, wage and hour violations, employee leave, and other claims with respect to labor or employment practices. These claims can be time-consuming and expensive to defend, regardless of their merit.
We may also be subject to breach of contract claims by our customers, subcontractors, suppliers, and other parties with whom we do business. Disputes may arise over the scope of work, quality of performance, entitlement to change orders, responsibility for delays or cost overruns, and other contractual matters. We may assert claims against our customers for additional compensation, and our customers may assert counterclaims against us. Resolution of these disputes through negotiation, arbitration, or litigation can be costly and time-consuming and may damage our business relationships.
In addition, we are required to provide surety bonds on many of our projects, and claims against our bonds can result in significant liabilities. If a surety is required to pay on a bond issued on our behalf, we are typically obligated to reimburse the surety through the surety general indemnity agreements, which could adversely affect our liquidity and financial condition. Any adverse outcome in litigation or legal proceedings could result in significant monetary damages, injunctive relief, or other remedies that could have a material adverse effect on our business, financial condition, and results of operations. Furthermore, the defense of legal proceedings, even if ultimately successful, can divert management attention from the operation of our business and result in significant legal fees and other expenses.
We may be unable to compete for projects if we are not able to obtain sufficient surety bonds, letters of credit, or other financial assurances required by our customers.
A portion of our business depends on our ability to provide surety bonds, letters of credit, or other financial assurances to our customers. Certain of our EPC contracts require us to maintain surety bonds for the benefit of customers during the construction and warranty periods. Current or future market conditions, including losses incurred in the construction industry or as a result of large corporate bankruptcies, as well as changes in our sureties’ assessment of our operating and financial risk, could cause our surety providers and lenders to decline to issue or renew, or substantially reduce the amount of, bid or performance bonds for our work and could increase our costs associated with collateral. These actions could be taken on short notice. If our surety providers or lenders were to limit or eliminate our access to bonding, letters of credit, or guarantees, our alternatives would include seeking capacity from other sureties and lenders or finding more business that does not require bonds or that allows for other forms of collateral for project performance, such as cash. We may be unable to secure these alternatives in a timely manner, on acceptable terms, or at all, which could affect our ability to bid for or work on future projects requiring financial assurances.
Under standard terms in the surety market, sureties issue or continue bonds on a project-by-project basis and can decline to issue bonds at any time or require the posting of additional collateral as a condition to issuing or renewing bonds. If we were to experience an interruption or reduction in the availability of bonding capacity, we may be unable to compete for or work on certain projects that require bonding.
38
Table of Contents
If we expand into new service areas, such as operations and maintenance or other adjacent businesses, we may face additional risks and liabilities for which we have limited experience.
As part of our growth strategy, we may expand into new service areas beyond our core EPC business, including operations and maintenance (“O&M”) services for utility-scale solar and battery storage projects, or other adjacent businesses. Expansion into new service areas involves inherent risks, including the need to develop new capabilities and expertise, hire and train personnel with different skill sets, invest in new systems and infrastructure, and establish relationships with new customers or market segments. We may not be successful in these efforts, and any new business lines may not achieve profitability or may take longer than anticipated to generate returns on our investment. Additionally, expansion into new areas could divert management attention and resources from our core EPC business.
If we were to enter the O&M market, we would face risks specific to that business. O&M contracts typically involve long-term performance obligations under which the service provider may be responsible for achieving certain availability, performance, or energy production targets. Failure to meet these targets could result in liquidated damages or other remedies. Equipment failures, component degradation, severe weather events, or other factors beyond our control may cause facilities to underperform, potentially resulting in liability. We may also become responsible for identifying and addressing equipment defects, design flaws, or installation errors that were not apparent at the time of project completion, which could result in costly repairs or replacement of equipment.
O&M services would also require us to maintain a geographically dispersed workforce of trained technicians capable of responding to maintenance needs and emergencies at project sites across multiple states. Managing this workforce efficiently and ensuring adequate staffing levels to meet contractual obligations can be challenging, particularly during periods of high demand or in remote locations. We may also face liability for personal injuries or property damage occurring at facilities we operate or maintain.
Furthermore, the O&M market is competitive, with established service providers, including specialized O&M companies, equipment manufacturers, and project owners who may choose to self-perform O&M services. As a new entrant, we may face challenges in winning O&M contracts and may need to accept lower margins to build a track record in this market. Similar risks would apply to other new service areas we may enter. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
If the market for technologies using artificial intelligence does not grow at the rate some parties expect, our customers or prospective customers may reduce their projected needs for power, which may impact the market for our offerings.
Some of our customers and prospective customers operate or otherwise rely on data centers and other similar infrastructure that can support, among other things, the growing demand for technologies that use artificial intelligence. Their business plans, including their construction of or expansion of infrastructure facilities that they intend to power using our offerings, may rely in part on assumptions around the growth of artificial intelligence technologies, which may prove to be unwarranted. If these assumptions prove incorrect, it may impact the business plans of these customers or prospective customers, which may reduce their need for our products or services, and may even lead to them canceling or renegotiating contracts with us. In addition, our own estimates of the market opportunity for EPC services tied to the buildout of power infrastructure supporting artificial intelligence, machine learning, and generative artificial intelligence workloads are inherently uncertain and based on assumptions that may not prove to be accurate, and if demand for the construction of these facilities grows less quickly than anticipated or declines, our future cash flows may be adversely affected. Such market disruptions or future lack of customer demand for power in the amounts we anticipate could adversely affect our business, results of operations, and financial condition.
39
Table of Contents
Disruptions to our information technology systems or cybersecurity breaches could expose us to significant liabilities, reputational harm, and operational disruption.
We rely on information technology systems to manage and support our business operations, including project management, engineering and design, estimating and bidding, procurement, scheduling, financial reporting, human resources, and communications with customers, suppliers, and subcontractors. Our systems store and process sensitive information, including proprietary business information, project designs and specifications, employee personal information, customer data, and financial records. Any significant disruption to our information technology systems, or any failure to maintain the security, integrity, or availability of these systems and the data they contain, could adversely affect our business operations and financial results.
Our information technology systems and those of our third-party service providers are vulnerable to damage or interruption from a variety of sources, including power outages, telecommunications failures, hardware or software failures, human error, natural disasters, and cyberattacks. Cybersecurity threats have become increasingly sophisticated and are constantly evolving, and may include ransomware attacks, malware infections, phishing schemes, denial-of-service attacks, social engineering, and other methods designed to gain unauthorized access to our systems, disrupt our operations, or steal, destroy, or manipulate our data. Threat actors may include nation-states, organized criminal groups, hacktivists, and malicious insiders, and their motivations may range from financial gain to industrial espionage to disruption of critical infrastructure.
The solar energy and battery storage, high-voltage substation and construction industries have become increasingly attractive targets for cyberattacks due to the critical nature of energy infrastructure and the sensitive project information maintained by industry participants. A successful cyberattack on our systems could result in the theft or disclosure of confidential business information, customer data, or employee personal information; the corruption or loss of critical project data; disruption to our project management, scheduling, or financial systems; delays in project execution and delivery; and liability for damages, regulatory penalties, or costs of remediation.
We have implemented security measures and controls designed to protect our information technology systems and data from unauthorized access or cyberattacks. However, no security measures are completely effective, and we cannot guarantee that our systems will not be compromised. We may be unable to anticipate or prevent all cyberattacks, particularly as attack methods continue to evolve and become more sophisticated. Additionally, our employees, subcontractors, and third-party service providers may inadvertently compromise the security of our systems through human error, negligence, or failure to follow security protocols. We maintain cybersecurity insurance coverage, but such coverage may not be sufficient to cover all losses arising from a significant cybersecurity incident. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
Our construction schedules, project economics, and results of operations are subject to physical risks, including severe weather events, natural disasters, and risks associated with climate change that can halt site work or damage projects in progress.
The construction of utility-scale solar, battery storage and high-voltage substation projects is conducted outdoors and is inherently subject to physical risks from weather conditions, natural disasters, and other environmental factors. Our project sites are located across diverse geographic regions throughout the United States, exposing our operations to a wide range of climate and weather conditions that can disrupt construction activities, damage work in progress, and adversely affect our ability to complete projects on time and within budget.
Severe weather events, including hurricanes, tropical storms, tornadoes, floods, hail storms, blizzards, ice storms, and extreme temperatures, can halt or disrupt construction activities for extended periods, damage
40
Table of Contents
installed equipment and materials, and create unsafe working conditions for our personnel. For example, hurricane season in the southeastern United States and Gulf Coast regions can result in project shutdowns lasting days or weeks, and the aftermath of such storms may further delay construction due to damaged infrastructure, supply chain disruptions, and competing demands for labor and materials in affected areas. Similarly, projects in northern regions may experience construction delays during winter months due to frozen ground conditions, heavy snowfall, or extreme cold that prevents outdoor work.
Natural disasters such as wildfires, earthquakes, and flooding can cause significant damage to project sites, equipment, and materials, and may render sites inaccessible for extended periods. Wildfires have become increasingly frequent and severe in certain regions of the United States, particularly in the western states where we construct projects. Even if a project site is not directly affected by a wildfire, smoke, air quality concerns, and evacuation orders can halt construction activities and impact worker health and safety. Earthquakes can damage foundations, installed equipment, and site infrastructure, potentially requiring costly repairs or reconstruction.
Climate change may increase the frequency and severity of extreme weather events, making our construction operations more vulnerable to weather-related disruptions over time. Rising temperatures may also reduce worker productivity during summer months and increase the risk of heat-related illnesses, while changing precipitation patterns may affect site conditions and the timing of construction activities. We maintain, or cause our customers to maintain, insurance coverage for certain weather-related losses and natural disasters, but such insurance may not cover all potential losses, and coverage limits may be insufficient to fully protect us against significant events.
Any deterioration in the quality or reputation of our brand, which can be exacerbated by the effect of social media or significant media coverage, could have a material adverse effect on our business, financial condition, and results of operations.
Our brand and our reputation are among our most important assets, and our ability to attract and retain customers, as well as qualified employees, depends on brand recognition and reputation. A variety of events could result in damage to our reputation, some of which are outside of our control, including: acts or omissions that adversely affect our business such as a crime, scandal, cyber-related incident, litigation, or other negative publicity; failure to successfully perform, or negative publicity related to, a high-profile project; actual or potential involvement in a catastrophic fire, explosion, mechanical failure of infrastructure, or similar event; or actual or perceived responsibility for a serious accident or injury. Increased media coverage and interest in energy transition matters and our industry, along with the intensification of media coverage generally, including through the considerable expansion in the use of social media, have increased the volume and speed at which negative publicity arising from these events can be generated and spread, and we may be unable to timely respond to, correct any inaccuracies in, or adequately address negative perceptions arising from such media coverage. If the reputation or perceived quality of our brand declines or customers lose confidence in us, our business, financial condition, and results of operations could be adversely affected.
We depend on the continued services of key personnel, including our senior management team and skilled project managers, and our inability to attract, retain, or replace such personnel could adversely affect our business.
Our success depends in significant part on the continued contributions of our senior management team, including our executive officers, and other key employees who possess specialized knowledge, skills, and experience that are critical to our operations. Our senior executives have extensive experience in the utility-scale solar, battery storage, and high voltage construction industry and have developed important relationships with our customers, suppliers, subcontractors, and other business partners. The loss of one or more members
41
Table of Contents
of our senior management team, or their failure to effectively transition their responsibilities, could disrupt our operations, harm our customer relationships, and adversely affect our ability to execute our business strategy.
In addition to our senior management, we rely on experienced project managers, engineers, estimators, and other key personnel who oversee and are responsible for the execution of our EPC projects. These individuals possess specialized technical knowledge and project management skills that are essential to delivering projects on time, within budget, and in accordance with quality standards. The market for qualified project management and technical personnel in the solar energy and battery storage construction industry is highly competitive, and we may be unable to attract and retain the personnel we need. Our competitors and other companies in our industry actively seek to recruit our employees, and we may lose key personnel to competitors who offer more attractive compensation packages or career opportunities.
We do not maintain key person life insurance on any of our executives or key employees. Although we have employment agreements with certain of our executive officers and key employees, these agreements do not guarantee their continued service, and they may terminate their employment at any time. We may also have difficulty identifying, hiring, and integrating qualified successors for departing executives or key employees. Our ability to attract and retain qualified personnel depends on a number of factors, some of which are beyond our control, including prevailing wage rates, competition for talent, and our reputation in the industry. The loss of key personnel, or our inability to attract and retain qualified personnel, could have a material adverse effect on our business, financial condition, and results of operations.
Our insurance coverage may be inadequate to cover all losses or liabilities we may incur, and insurance may become more difficult or expensive to obtain in the future.
We maintain insurance coverage for various risks associated with our business, including general liability, professional liability, workers’ compensation, automobile liability, aviation/drone liability, cyber, property, builder’s risk, and pollution liability insurance. We also maintain umbrella and excess liability policies that provide additional coverage above the limits of our primary policies. We also generally negotiate our contracts to require our customers to provide builders risk insurance for our benefit on the projects we work. However, such insurance coverage is subject to self-insured retentions, deductibles, coverage limits, exclusions, and other terms and conditions that may result in our not being fully compensated for losses we incur. Additionally, certain types of losses may be uninsurable or may only be insurable at costs that we consider to be prohibitive.
The construction industry, and the solar energy and battery storage construction industry in particular, has experienced significant increases in insurance costs and reductions in available coverage in recent years. Insurers have become more selective in the risks they are willing to underwrite, and coverage for certain risks, such as wildfire, flood, hail damage, and other natural catastrophe exposures, has become more limited and expensive. We may be unable to obtain insurance coverage on acceptable terms, or at all, for certain risks, and we may be required to accept higher deductibles or lower coverage limits than we have historically maintained. Any significant uninsured or underinsured loss could have a material adverse effect on our financial condition.
Our insurance policies are subject to annual renewal, and there can be no assurance that we will be able to renew our policies at comparable coverage levels and premiums. Insurance carriers may decline to renew our policies, impose significant premium increases, or reduce coverage based on our claims history, changes in their risk appetite, or general market conditions. Furthermore, our insurers may become insolvent or otherwise unable to pay claims, leaving us without coverage for insured losses.
We may also be required to provide evidence of insurance coverage to our customers as a condition of being awarded contracts, and any inability to obtain required coverage could limit our ability to compete for certain projects. Additionally, claims against our insurance policies, even if ultimately covered, can result in increased
42
Table of Contents
premiums, higher deductibles, or reduced coverage availability in subsequent policy periods. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
Our use of the percentage-of-completion method of revenue recognition requires subjective estimates that, if incorrect, could require us to recognize losses or revise previously reported revenues.
We recognize revenues on our lump sum EPC contracts using the percentage-of-completion method in accordance with Accounting Standards Codification Topic 606 (“ASC 606”). This method requires us to estimate, at each reporting date, the total costs expected to be incurred to complete each contract and to recognize revenue based on the ratio of costs incurred to estimated total costs. These estimates require significant judgment and are subject to uncertainty, particularly on long-duration projects subject to weather, supply chain, site condition, and other risks described elsewhere in this prospectus. If our cost-to-complete estimates prove to be inaccurate, whether due to unforeseen site conditions, subcontractor cost increases, design changes, or other factors, we may be required to recognize lower profits or losses in future periods on a cumulative catch-up basis, which could result in material adverse adjustments to our reported revenues and earnings in the period the revised estimate is recognized. For contracts where total estimated costs exceed total estimated revenues, we recognize the full expected loss immediately in the period in which the loss becomes known, which could result in a significant charge to earnings. Changes in cost estimates on a small number of large projects could have a disproportionate impact on our quarterly and annual financial results. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
Our backlog may not be realized or may not result in profits, and may not accurately represent future revenue.
We define backlog as the total expected revenue from the uncompleted portions of existing contracts, including new contracts for which we have received a written award notice, notice to proceed or for which we have an executed contract. As of June 30, 2026, our backlog was approximately $3.6 billion. Although backlog reflects business that we consider to be firm, cancellations, scope reductions, or deferrals may occur, and we cannot guarantee that the revenues projected in our backlog will be realized or, if realized, will result in profits. Backlog should not be considered a reliable indicator of our future revenues or profitability, and investors should not unduly rely on backlog information in evaluating our business or prospects.
Backlog is difficult to determine with precision because our EPC contracts for utility-scale solar, battery storage, and high voltage projects are subject to delays, changes in scope, and terminations that can significantly affect the amount and timing of our revenue recognition. The duration of our projects can extend from several months to more than a year, and a variety of factors can affect whether and when backlog is converted to revenue. Customers may cancel or defer projects due to changes in their financing arrangements, permitting delays, grid interconnection issues, changes in project economics, shifts in strategic priorities, or general economic conditions affecting their business. Many of our EPC contracts permit customers to terminate for convenience, subject to payment for work completed and certain termination fees, which may not fully compensate us for the loss of the anticipated project revenue and margin.
Furthermore, our backlog may not convert to revenue at the rates or within the timeframes we anticipate. Projects may be delayed due to factors beyond our control, including adverse weather conditions, supply chain disruptions, labor shortages, equipment delivery delays, or regulatory approvals. Delays in the commencement or progress of projects can push revenue recognition into future periods, affecting our quarterly and annual financial results. Additionally, projects included in our backlog may ultimately be completed at lower margins than originally estimated due to cost overruns, change orders that are not fully compensated, performance issues, or other unforeseen circumstances. Cost increases related to labor, materials, tariffs, or other factors may erode the profitability of projects in our backlog, particularly under lump sum contracts where we bear the risk of cost overruns.
43
Table of Contents
We may also experience variability in the timing and amount of revenue recognized from our backlog due to the percentage-of-completion accounting method we use for our EPC contracts. Changes in estimated costs to complete projects can result in adjustments to previously recognized revenue, which may increase or decrease our reported revenues and profits in any given period. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
Our business requires significant working capital, and our cash flow is subject to timing mismatches between project expenditures and customer payments that could strain our liquidity.
The construction of utility-scale solar, battery storage and high-voltage substation projects is capital-intensive and requires us to make substantial expenditures for labor, materials, equipment, and subcontractor services, often in advance of receiving corresponding payments from our customers. Our EPC contracts typically provide for progress payments based on the achievement of specified milestones or the completion of defined work packages, and the timing of these payments may not align with the timing of our expenditures. We may be required to fund significant working capital needs during the early stages of a project, when mobilization, procurement, and site preparation costs are incurred before milestone payments commence. Additionally, our customers may dispute milestone achievements, withhold payments for alleged defects, withhold retainage amounts until project completion, or delay payments for administrative or financial reasons, further extending the gap between our cash outflows and inflows.
If we are unable to manage our working capital effectively, we may need to rely on our credit facilities or other sources of financing to fund our operations, which could increase our borrowing costs and reduce our financial flexibility. During periods of high project activity or rapid growth, our working capital requirements may exceed our available resources, potentially limiting our ability to pursue new projects or requiring us to incur additional indebtedness on unfavorable terms. Our working capital needs may also increase as a result of supply chain disruptions, tariff-related cost increases, or project delays that extend the duration of our expenditure cycle. Any inability to maintain adequate liquidity to fund our working capital requirements could have a material adverse effect on our business, financial condition, and results of operations.
Significant backlogs in grid interconnection queues may delay or prevent our customers’ projects from reaching construction, reducing demand for our EPC services.
The interconnection of utility-scale solar and battery storage projects to the electric grid requires completion of a multi-step process administered by regional transmission organizations (“RTOs”), independent system operators (“ISOs”), and individual utilities, which includes interconnection studies, system impact analyses, facility studies, and the negotiation of interconnection agreements. In recent years, the volume of interconnection requests has dramatically outpaced the capacity of grid operators to process them, resulting in extensive queue backlogs and wait times that can extend for several years in many regions of the United States. According to publicly available data, the average time from interconnection request to commercial operation for utility-scale projects has increased significantly, and a substantial percentage of projects that enter interconnection queues are ultimately withdrawn before reaching construction.
These interconnection delays directly affect our business because our customers generally cannot commence construction of their projects, and therefore cannot engage us under EPC contracts, until they have obtained an interconnection agreement and have sufficient certainty regarding their grid connection timeline and costs. Prolonged interconnection timelines reduce the number of projects that are ready for construction in any given period, which constrains our addressable market and can result in periods of reduced project activity. Additionally, our customers may face significant and unpredictable interconnection upgrade costs, which can alter project economics and lead to project cancellations or deferrals. Changes to interconnection procedures, including reforms implemented by the Federal Energy Regulatory Commission (“FERC”) under Order No. 2023
44
Table of Contents
and subsequent orders, may alter queue processing timelines and requirements in ways that benefit or disadvantage our customers’ projects. There can be no assurance that interconnection reforms will be implemented in a timely or effective manner, or that such reforms will reduce the backlog to levels that materially benefit our business. Any continued or worsening interconnection delays could have a material adverse effect on our business, financial condition, and results of operations.
Our inability to successfully execute our acquisition strategy may adversely impact our growth, and acquisitions involve risks that could have a material adverse effect on our business.
Our business strategy includes expanding our presence in the industries we serve and adjacent industries through strategic acquisitions of companies that complement or enhance our business. The number of acquisition targets that meet our criteria may be limited, and we may face competition for acquisition opportunities from other potential acquirers who may offer more favorable terms or have greater financial resources. Failure to consummate future acquisitions could negatively affect our growth strategies. Additionally, our past and future acquisitions may involve significant cash expenditures or stock issuances, the incurrence or assumption of debt and other known and unknown liabilities, and exposure to burdensome regulatory requirements. We may discover previously unknown liabilities associated with an acquired business, and we may have inadequate or no recourse under applicable indemnification provisions or representation and warranty insurance coverage.
The success of our acquisition strategy also depends on our ability to successfully integrate the operations of acquired businesses with our existing operations and realize the anticipated benefits, such as expansion of our service offerings, elimination of redundant costs, and cross-selling opportunities. Our ability to integrate and realize benefits can be negatively impacted by, among other things: failure of an acquired business to achieve the results we expect; diversion of our management’s attention from operational matters; difficulties incorporating the operations and personnel, or inability to retain key personnel, of an acquired business; the complexities and difficulties associated with managing our business as it grows and becomes more complex; additional financial reporting and accounting challenges; unanticipated events or liabilities associated with an acquired business; and risks and liabilities arising from the prior operations of an acquired business, such as performance, operational, safety, cybersecurity, environmental, or compliance issues, some of which we may not have discovered during due diligence and may not be covered by indemnification obligations or insurance. We cannot be sure that we will be able to successfully complete the integration process without substantial costs, delays, disruptions, or other operational or financial problems. Failure to successfully integrate acquired businesses could have a material adverse effect on our business, financial condition, and results of operations.
We use AI technologies in our business, and the deployment, use, and maintenance of these technologies involve significant technological and legal risks.
We use artificial intelligence, machine learning, data science and similar technologies (collectively, “AI”) technologies in our business, and we are making investments to continuously evaluate, develop, deploy, use, maintain, and improve our use of such technologies. The market for AI technologies is rapidly evolving and these technologies are yet to become widely accepted in many industries, including the energy infrastructure industry. We cannot be sure that the market will continue to grow or that it will grow in ways we anticipate. We are in varying stages of evaluation and implementation in relation to AI technologies, and we may not be successful in our ongoing development of these technologies in the face of novel and evolving technical, reputational, and market factors. We are currently leveraging a small number of mainstream, third-party AI tools, including Microsoft 365 Copilot for Enterprise and AI Clearing. We have not initiated the development of any proprietary AI technology.
45
Table of Contents
Our use of AI could also result in unintended consequences. For example, AI algorithms and models that are used may have undisclosed inherent limitations, be flawed or contain errors or may be based on datasets that are biased, outdated, collected in violation of applicable laws, or insufficient.
We also face competition in relation to the evaluation, development, deployment, use, maintenance, and improvement of AI technologies. Our competitors or our customers may develop or use technologies that are similar or superior to ours, are more cost-effective, or are quicker to develop and deploy. Our failure to successfully commercialize product offerings involving AI technologies, or our failure to offer or deploy new technologies as effectively, as quickly or as cost-efficiently as our competitors, could impair our ability to expand our business and deliver value to our customers. We expect that increased investment will be required in the future to continuously implement data-driven solutions and improve our use of AI technologies.
The technologies underlying AI and its use cases are rapidly developing, and remain subject to existing laws, including privacy, consumer protection and federal equal opportunity laws. As a result, it is not possible to predict all of the legal, operational or technological risks related to the use of AI. Such uncertainty in the legal regulatory regime relating to AI, such as evolving review by agencies including the SEC and the FTC, may require significant resources to modify and maintain business practices to comply with U.S. and non-U.S. laws and regulations, the nature of which cannot be determined at this time.
As with many technological innovations, there are significant risks involved in evaluating, developing, deploying, using, maintaining and improving these technologies, and there can be no assurance that the usage of or our investments in such technologies will always enhance our data-driven solutions or be beneficial to our business, including our efficiency or profitability. Any of the foregoing, together with developing guidance and/or decisions in this area, may affect our use of AI and our ability to provide and improve our services, require additional compliance measures and changes to our operations and processes, and result in increased compliance costs and potential increases in civil claims against us. Any actual or perceived failure to comply with evolving regulatory frameworks around the development and use of AI technologies could adversely affect our business, results of operations, and financial condition.
Risks Related to Our Industry
Negative macroeconomic conditions, including inflation, rising interest rates, and tighter credit markets, can reduce demand for solar energy and battery storage projects and have a material adverse effect on our industry, as well as our business, financial condition, and results of operations.
Stagnant or deteriorating economic conditions, including a prolonged economic downturn or recession, as well as significant events that have an impact on financial or capital markets, can adversely impact the demand for our EPC services and result in the delay, reduction, or cancellation of utility-scale solar and battery storage projects. Macroeconomic conditions, including inflation, slow growth or recession, changes to fiscal and monetary policy, changes in global trade relationships, and tighter credit and higher interest rates could materially and adversely affect demand for our services and the availability and cost of the materials and equipment that we need to deliver our services or that our customers need for their projects. During periods of elevated economic uncertainty, our customers, including solar energy and battery storage developers, independent power producers, utilities, and infrastructure-backed platforms may reduce or eliminate their spending on EPC services.
Inflation and rising interest rates can increase our costs for materials, components, labor, and other inputs, and may not be fully recoverable through price increases to our customers, particularly under lump sum EPC contracts where we bear the risk of cost overruns. Higher interest rates also increase our cost of capital and may make it more difficult or expensive for us to raise additional financing to fund our operations or working
46
Table of Contents
capital needs. Additionally, our customers often rely on external financing, including tax equity, debt facilities, and project finance arrangements, to fund utility-scale solar and battery storage projects. Increased borrowing costs or reduced availability of capital in the market could delay or curtail our customers’ projects, reducing demand for our EPC services.
In addition, volatility in the debt or equity markets, as well as prolonged higher interest rates, may negatively impact our customers’ access to or willingness to raise capital and result in the reduction or elimination of spending on the EPC services we provide. Our vendors, suppliers, and subcontractors may also be, to varying degrees, adversely affected by these conditions. A reduction in cash flows or the lack of availability of debt or equity financing for our customers on favorable terms could result in a reduction in our customers’ spending for our services and also impact the ability of our customers to pay amounts owed to us, which could have a material adverse effect on our business, financial condition, and results of operations.
The reduction, elimination, or expiration of government incentives for solar energy and battery storage, including federal tax credits under the Inflation Reduction Act and related legislation, could significantly reduce demand for EPC services across the industry.
Federal and certain state and local government bodies provide incentives to owners, end-users, and manufacturers designed to promote the use of solar energy and battery storage, primarily in the form of tax credits. Consequently, the attractiveness of solar energy and battery storage projects depends in part on the availability of certain government incentives. We derive our revenues primarily from providing EPC services for utility-scale solar energy and battery storage projects, and the reduction, elimination, or expiration of these incentives, including tax credits for solar and battery storage projects or renewable portfolio standards, may negatively affect the competitiveness of solar electricity relative to conventional and non-solar renewable sources of electricity. This could reduce the number of new solar and battery storage projects and, consequently, reduce demand for our EPC services.
The Inflation Reduction Act of 2022 (the “IRA”), signed into law in August 2022, extended the production tax and investment tax credits under Sections 45 and 48 of the Code (the “Legacy Credits”) and introduced the technology neutral clean electricity investment and production tax credits under Section 48E and 45Y of the Code, respectively, (the “Tech Neutral Credits” and together with the Legacy Credits, the “Clean Energy Tax Credits”). Our customers expect to benefit from the Legacy Credits and Tech Neutral Credits from the development and production of clean energy facilities. The IRA imposed a number of requirements in order to establish eligibility for the Clean Energy Tax Credits, in particular, requirements with respect to payments of prevailing wages and utilization of apprentices during prescribed time periods. The IRA also incentivized the location of certain projects by providing for an energy community bonus and the use of domestic components through the domestic content bonus.
Subsequently, the One Big Beautiful Bill Act of 2025, H.R. 1 (“OBBBA”), limited the availability of Tech Neutral Credits by, inter alia, imposing restrictions on ownership, debt, and effective control (including through the grant of rights through various agreements or licensing rights that are otherwise retained by such entities) in respect of certain “prohibited foreign entities.” The OBBBA also included restrictions with respect to the use of certain components and taxpayers that receive material assistance from certain “prohibited foreign entities,” thereby potentially increasing costs and reducing demand, or restricting our customers’ access to Tech Neutral Credits. Preliminary interim guidance has been released by the U.S. Department of Treasury and IRS that further clarified methods for calculating material assistance cost ratios and provided a safe harbor for purposes of determining a taxpayer’s material assistance from a “prohibited foreign entity.” The U.S. Department of Treasury and the IRS have indicated that more comprehensive guidance relating to these limitations is forthcoming which will be relevant to ours and our customers’ businesses and operations. The OBBBA also accelerated the deadline by which our customers must begin construction of a project or facility in order to be
47
Table of Contents
eligible for Tech Neutral Credits. The full implication of the OBBBA as it relates to tax credit modifications and “prohibited foreign entity” restrictions and its accompanying guidance cannot be known with certainty.
Eligibility for tax credits and other incentive programs requires compliance with detailed statutory and regulatory requirements, including prevailing wage and apprenticeship requirements, beginning construction and placed-in-service deadlines, emissions qualifications, limitations on ownership, debt, and control by and from certain foreign entities, limitations on sourcing of components from certain foreign entities, domestic content and energy community requirements (as applicable), and ongoing reporting and certification obligations. If our customers, or we, on behalf of our customers, are unable to satisfy applicable Clean Energy Tax Credit requirements, our customers may abandon or not proceed with projects.
Additionally, any reduction, elimination, or discriminatory application of tax credits or benefits, government subsidies and economic incentives that would otherwise be available to our customers because of policy changes, or the reduced need for such subsidies and incentives, may require our customers to seek additional financing, which may not be obtainable on commercially attractive terms or at all, or to abandon or not proceed with projects. Furthermore, certain state-level renewable portfolio standards and clean energy mandates that have historically supported demand for utility-scale solar projects may be weakened, repealed, or not enforced, which could further reduce the pipeline of projects requiring our EPC services. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
Technological advancements in other forms of power generation could reduce investment in solar and battery storage projects and decrease demand for our EPC services.
Technological advancements in other forms of power generation could result in reduced investment in solar and battery storage projects and reduced demand for our EPC services, which could have a material adverse effect on our business, financial condition, and results of operations. For example, if other forms of power generation, including natural gas, nuclear, coal, or other solar energy and battery storage technologies such as wind, geothermal, or hydrogen, are able to generate and deliver electricity at lower cost or with improved operational and/or environmental efficiency relative to solar and battery storage projects, demand for our services could be significantly reduced.
Additionally, any technological advancements may result in increased investment in other forms of power generation in lieu of investment in our industry, which could result in changing customer priorities and lead to reduced demand. For example, advancements in small modular nuclear reactors, next-generation wind turbines, or long-duration energy storage technologies that compete with lithium-ion battery storage systems could shift capital investment away from utility-scale solar and co-located battery storage projects that constitute the core of our EPC business.
Our future success will depend, in part, on our ability to anticipate and adapt to these and other potential changes in a cost-effective manner and to offer services that meet customer demands and evolving industry standards. Our failure to do so or the incurrence of significant expenditures in adapting to such changes could have a material adverse effect on our business, financial condition, and results of operations. Furthermore, we view our expertise in utility-scale solar and battery storage construction as a competitive strength, which we believe differentiates our service offerings. If our proprietary processes or specialized construction capabilities become obsolete through technological advancements or otherwise, we may not be able to differentiate our service offerings and some of our competitors may be able to offer more attractive services to our customers.
Our industry is highly competitive, and competitive pressures from other EPC contractors, self-performing customers, and new market entrants could negatively affect our pricing, market share, and profitability.
We cannot be certain that we will maintain or enhance our competitive position or maintain our current customer base. Our industry is served by numerous companies, from small, owner-operated private companies
48
Table of Contents
to large multinational public companies. Relatively few barriers prevent entry into some areas of our business, and as a result, any organization that has adequate financial resources and access to technical expertise may become one of our competitors. In addition, some of our competitors have significant financial, technical, and marketing resources, and may have or develop expertise, experience, and resources to provide EPC services that are superior in both price and quality to our services. Certain of our competitors may also have lower overhead cost structures, and therefore may be able to provide services at lower rates than us. Less experienced competitors and new contractors trying to compete in our space may not fully understand certain risks and costs; thus, under bidding us and certain projects to negatively impact our win rate.
Additionally, many of our existing or prospective customers are now capable, or may in the future become capable, of self-performing the same types of EPC services we provide. Certain solar energy and battery storage developers and utilities have in-house construction capabilities and may face pressure or be compelled to self-perform an increasing amount of the services we currently perform for them, thereby reducing the services they outsource to us in the future. We also subcontract certain of our services, and certain of these subcontractors may develop into competitors on prime contracts with our customers.
Furthermore, a substantial portion of our revenues is directly or indirectly dependent upon obtaining new EPC contracts, which is unpredictable and often involves complex and lengthy negotiations and bidding processes that are impacted by a wide variety of factors, including price, governmental approvals, financing contingencies, commodity prices, environmental conditions, overall market and economic conditions, and a potential customer’s perception of our ability to perform the work. The competitive environment we operate in can also affect the timing of contract awards and the commencement or progress of work under awarded contracts. Based on rapidly changing competition and market dynamics, we have experienced, and may in the future experience, more competitive pricing for certain projects. As a result of the factors described above, the competitive environment we operate in could have a material adverse effect on our business, financial condition, and results of operations.
Volatility in the debt or equity markets may negatively impact our customers’ access to capital, resulting in project delays, cancellations, or reduced demand for our services.
Our business is exposed to risks associated with the solar energy and battery storage industry, including our customers’ ability to secure financing for utility-scale solar and battery storage projects. Our customers typically finance their projects through a combination of tax equity, debt facilities, and equity capital. Volatility in the debt or equity markets, as well as prolonged higher interest rates, may negatively impact our customers’ access to or willingness to raise capital and result in the reduction or elimination of spending on the EPC services we provide.
A reduction in cash flows, short term liquidity issues, or the lack of availability of debt or equity financing for our customers on favorable terms could result in a reduction in our customers’ spending for our services and also impact the ability of our customers to pay amounts owed to us. Furthermore, many of our customers for larger projects are project-specific entities that do not have significant assets other than their interests in the project and could be more likely to encounter financial difficulties relating to their businesses. We ultimately may be unable to collect amounts owed to us by customers experiencing financial difficulties, and accounts receivable from such customers may become uncollectible and ultimately have to be written off.
Slowing economic conditions in the power industry can also impair the financial condition of our customers and hinder their ability to pay us on a timely basis or at all. To the extent a customer files bankruptcy, payment of amounts owed can be delayed and certain payments we receive prior to the filing of the bankruptcy petition may be avoided and returned to the customer’s bankruptcy estate. In the past, solar energy and battery storage developers and project owners have experienced bankruptcies, restructurings, and program cancellations, and similar events could affect our current or prospective customers.
49
Table of Contents
Tax equity financing and tax credit transfers, which are a critical component of project financing for utility-scale solar and battery storage projects, is provided by a limited number of large corporations or financial institutions and investors. Disruptions in the tax equity or tax credit transfer market, changes in the appetite or tax capacity of tax equity investors or tax credit buyers, or reductions in the availability of tax equity or tax credit transfer participants due to legislative changes affecting the value of tax credits or the risk associated with investing or purchasing credits could significantly impact our customers’ ability to finance projects. Additionally, rising interest rates increase the cost of debt financing for our customers, which may render certain projects economically unviable or cause customers to delay construction until financing conditions improve. We have limited visibility into our customers’ financing arrangements, and unexpected financing difficulties could result in project delays, scope reductions, or cancellations after we have already committed resources to a project. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
Projects in our industry can have long sales cycles requiring significant upfront investment of resources, which may not result in executed contracts or revenue.
The sales cycles for our customers’ utility-scale solar and battery storage projects vary substantially and can take many months or years to mature. As a result of these long sales cycles, we may need to make significant upfront investments of resources, including sales and marketing, engineering, and project development expenses, in advance of the signing of EPC contracts, commencing construction, and recognizing any revenue, which may not be recognized for several additional months following contract signing.
Utility-scale solar and battery storage projects require extensive permitting, interconnection studies, land acquisition, financing arrangements, and regulatory approvals before construction can commence. These pre-construction phases can extend for years, and during this period, we may invest significant time and resources in project pursuit activities, including detailed site assessments, engineering studies, and bid preparation, without any assurance that we will be awarded the EPC contract. Our potential inability to enter into contracts with potential customers on favorable terms after making such upfront investments could cause us to forfeit certain nonrefundable payments or otherwise have a material adverse effect on our business, financial condition, and results of operations.
Furthermore, our customers’ projects may be delayed or cancelled due to factors beyond our control, including tax law or regulatory changes, permitting delays, grid interconnection queue backlogs, environmental challenges, community opposition, or changes in project economics. These delays can extend the sales cycle even further and may ultimately result in project cancellations after we have already invested significant resources. In addition, our customers may choose to award EPC contracts to competitors, even after we have invested substantial resources in pursuing a particular project. Competitive bidding processes in our industry are intense, and customers may select other EPC contractors based on price, perceived qualifications, existing relationships, or other factors, leaving us with unrecoverable pursuit costs. We also face the risk that customers may decide to self-perform EPC services after initially seeking bids from third-party contractors, which would similarly result in us being unable to recover our upfront investment. These dynamics can result in significant expenditures that do not translate into revenue. Any such delays or cancellations could have a material adverse effect on our business, financial condition, and results of operations.
Consolidation, competition, and capital constraints in the solar energy and battery storage industry can result in reduced spending by, or the loss of, our customers.
Our business is exposed to risks associated with the solar energy and battery storage industry that are not subject to our control, including power prices, the availability and attractiveness of incentives for solar energy and battery storage, the demand for solar energy and battery storage sources, and legislative and regulatory
50
Table of Contents
actions, as well as public opinion, regarding the impact of fossil fuels on the climate and environment. Specifically, lower power prices, or the perceived risk thereof, can result in decreased or delayed spending by our customers on utility-scale solar and battery storage projects.
Consolidation, competition, and capital constraints in the solar energy and battery storage industry can result in reduced spending by, or the loss of, one or more of our customers. The solar energy and battery storage development industry has experienced periods of significant consolidation as larger developers acquire smaller competitors, and private equity and infrastructure funds have become increasingly active acquirers of development platforms. This consolidation can result in the loss of customers if an acquiring company has existing relationships with other EPC contractors or decides to self-perform construction services. Furthermore, when our customers are acquired or undergo significant ownership changes, the new owners may elect to discontinue projects that were previously in our pipeline, renegotiate contract terms, or shift their development focus to other technologies or geographies where we have less presence. We may also lose key customer relationships if personnel with whom we have established working relationships depart following such transactions.
A number of factors can adversely affect the power industry, including prevailing power prices, the economic impact of supply chain and other logistical issues, financing conditions, potential bankruptcies, global and U.S. trade relationships, changes in regulations, including modifications to tax credits and solar energy and battery storage mandates, and other geopolitical conflicts and events. A significant customer may encounter financial constraints based on cost of capital or other reasons, file for bankruptcy protection, or cease operations, any of which could result in reduced or discontinued business with us. Additionally, our customers may face pressure from their own investors or lenders to reduce costs, which could lead them to delay projects, reduce project scope, or seek lower-cost EPC alternatives. Changes in our customers’ strategic priorities, such as a shift away from utility-scale solar toward distributed generation or other technologies, could also reduce their demand for our services. The loss of business from a significant customer could have a material adverse effect on our business, financial condition, and results of operations.
Risks Related to Our Legal and Regulatory Concerns
Regulatory requirements applicable to our industry, including environmental, health, safety, and permitting requirements, and changes in such regulations, may adversely affect demand for our services.
The federal, state, and local regulations affecting the solar energy and battery storage and construction industries, including environmental, health, safety, and permitting requirements, as well as materials sourcing and transportation obligations, have a material effect on our business. These regulations are complex and subject to change both in substance and interpretation, and regulations across various jurisdictions can differ or conflict, all of which can negatively impact our or our customers’ ability to efficiently operate. In recent years, customers in our industry have faced heightened regulatory requirements and increased regulatory enforcement, as well as private legal challenges related to compliance with such regulatory requirements, which have resulted in delays, reductions in scope, and cancelations of utility-scale solar and battery storage projects.
Our EPC services require us to navigate a complex web of permitting and regulatory approvals at the federal, state, and local levels. Utility-scale solar and battery storage projects typically require environmental impact assessments, land use permits, building permits, electrical permits, and approvals from agencies responsible for protecting wetlands, endangered species, and cultural resources. Delays in obtaining these permits, or changes to permitting requirements during the course of a project, can result in significant schedule delays, cost overruns, and potential liability for liquidated damages under our EPC contracts. Furthermore, our inability to meet regulatory requirements applicable to our customers could result in decreased demand for our services.
51
Table of Contents
For example, on July 7, 2025, the Trump Administration issued an executive order directing the Secretary of the Interior to revise regulations, guidance, policies, and practices to eliminate any preferential treatment to wind and solar facilities in comparison to dispatchable energy sources. On July 29, 2025, the Secretary of Interior issued an order directing the Department of Interior to identify and halt support for policies biased in favor of wind and solar energy, including with respect to land use authorizations, environmental and wildlife permits, and other actions such as temporary use permits and access road authorizations. These and similar governmental actions can impact continuous or future investment and development of solar projects on federal land or that require federal permits or approvals, and therefore reduce the demand for our EPC services. For example, certain government officials or entities may take a different interpretation on permitting requirements and the associated fees that can delay the project and increase our costs. There are typically exemptions for utility scale solar projects from inspections by local authorities, but there is no guarantee that the state or local authorities will honor such intended exemptions.
With respect to our EPC contracts where we are responsible for procuring all or a portion of the materials needed for projects, we are often required to comply with complex sourcing and transportation regulations, which can involve cross-border movement of materials. Changes to, or our failure to comply with, these regulatory requirements can result in project delays and additional project costs, which may be substantial and not recoverable from third parties, and in some cases, we may be required to compensate the customer for such delays, including in circumstances where we have guaranteed project completion by a scheduled date and incur liquidated damages if we do not meet such schedule. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
The unavailability, reduction, or accelerated termination of government and economic incentives, including as a result of recent legislation such as the OBBBA, could have a material adverse effect on our business.
As stated above, we and our customers benefit from certain government subsidies and economic incentives, including solar energy and battery storage tax credits, rebates, and other incentives that support the development and adoption of solar energy and battery storage solutions. The IRA introduced and extended several U.S. federal income tax credits to promote clean energy development, including the Tech Neutral Credits. The IRA has driven significant investments in clean energy developments since its enactment and thereby increased demand from our customers for our EPC services.
However, under the OBBBA, which was signed into law on July 4, 2025, the Tech Neutral Credits for solar and wind projects are scheduled to terminate on an accelerated schedule. Solar projects must either (1) begin construction (as determined for U.S. federal income tax purposes) on or before July 4, 2026 or (2) be placed in service (as determined for U.S. federal income tax purposes) on or before December 31, 2027 to be eligible for these tax credits. Moreover, following the enactment of the OBBBA, the Trump Administration issued an executive order requiring the U.S. Department of the Treasury, among other things, to enforce the accelerated termination of the Tech Neutral Credits for solar projects. Following the executive order, the Treasury and the U.S. Internal Revenue Service released IRS Notice 2025-42, which eliminated the opportunity for most developers and other project owners to be treated as having begun construction of a solar project by paying or incurring at least five percent (5%) of the total costs of the relevant project. Instead, the guidance requires developers to demonstrate physical work of a significant nature to substantiate when construction began for purposes of the Tech Neutral Credits’ termination deadlines.
The accelerated sunset of the Tech Neutral Credits for solar under the OBBBA, along with the Trump Administration’s recent enforcement efforts, could limit the availability of U.S. federal income tax credits for future solar projects and therefore could have a material adverse impact on future levels of investment in utility-scale solar projects in the United States, which could result in a significant reduction in the demand for our EPC services. In addition, as described above, the OBBBA created new limitations and restrictions relating
52
Table of Contents
to the direct or indirect ownership, influence, or control of U.S. clean energy projects by, and the inclusion of equipment and components within U.S. clean energy projects provided by, citizens of and entities organized under the laws of or having their principal place of business in certain non-U.S. countries, including the People’s Republic of China (the “PRC”), and certain affiliated entities thereof. Solar and battery storage projects that fail to comply with these limitations and restrictions generally will be ineligible to claim the Tech Neutral Credits (in the case of solar projects) and the Tech Neutral Credits under Section 48E of the Code (in the case of battery storage projects). These new limitations and restrictions may negatively affect the competitiveness of utility-scale solar projects and co-located solar and battery storage projects relative to conventional sources of electricity, which could reduce the number of new utility-scale solar and battery projects and result in a significant reduction in the demand for our EPC services. Moreover, the restrictions on the inclusion of equipment and components provided by entities with nexus to the PRC may require us to reevaluate our suppliers and underlying supply chains and could materially increase the cost of providing EPC services to our customers. In response to these developments, we continue to monitor the evolving regulatory and incentive landscape and work closely with our customers to help ensure compliance with applicable requirements, including prevailing wage, apprenticeship, and domestic content standards that may affect eligibility for remaining tax credits. However, there can be no assurance that our efforts to adapt to these changes will be sufficient to offset the potential reduction in demand for our EPC services.
Further, as demonstrated by the above discussion of the OBBBA and related changes in law, government incentives are subject to inherent uncertainties and may be discontinued, repealed, or amended at any time. Any reduction, elimination, or discriminatory application of government subsidies and economic incentives that would otherwise be available to our customers because of further policy changes, or the reduced need for such subsidies and incentives, may require our customers to seek additional financing, which may not be obtainable on commercially attractive terms or at all, or abandon or not proceed with projects. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
Our projects may be subject to compliance with North American Electric Reliability Corporation reliability standards and other grid-related regulations, and failure to comply could result in penalties and project delays.
Utility-scale solar and battery storage projects that interconnect to the bulk power system may be subject to mandatory reliability standards established by the North American Electric Reliability Corporation (“NERC”) and enforced by FERC. These reliability standards govern various aspects of the planning, design, construction, operation, and maintenance of facilities that are connected to the bulk electric system, including requirements related to protection systems, facility ratings, communications, and cybersecurity. Compliance with NERC standards is mandatory, and violations can result in substantial civil penalties.
As an EPC contractor, we may be responsible for designing and constructing projects in a manner that enables our customers to comply with applicable NERC standards. Errors or omissions in our engineering designs, construction work, or commissioning activities could result in facilities that do not meet NERC requirements, potentially exposing our customers to penalties and requiring costly modifications to achieve compliance. Our customers may seek to recover such costs from us through warranty claims, indemnification demands, or litigation.
In addition, the interconnection of utility-scale solar and battery storage projects to the electric grid is subject to extensive regulation by FERC, state public utility commissions, and RTOs or ISOs. The interconnection process involves detailed technical studies, engineering reviews, and compliance demonstrations that can be lengthy and complex. Changes in interconnection requirements or reliability standards during the course of a project could require modifications to our designs or construction plans, resulting in delays and additional costs.
Furthermore, the regulatory landscape for grid-connected solar energy and battery storage facilities continues to evolve as regulators address challenges related to the integration of variable generation resources and
53
Table of Contents
battery storage systems into the electric grid. New or modified reliability standards, interconnection requirements, cost allocation methodologies or grid rules could increase the complexity and cost of our projects, require us to develop new technical capabilities, or create uncertainty that delays project development. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
We are subject to complex federal, state, and local environmental, health, and safety laws and regulations that could expose us to significant liabilities or require costly compliance measures.
Our EPC operations are subject to a complex and rapidly evolving set of federal, state, local, and international environmental, health, and safety laws and regulations. These laws govern the generation, use, storage, release, management, and disposal of, or exposure to, hazardous materials and wastes, the remediation of contaminated sites, fuel storage, wastewater and stormwater discharges, air emissions, the protection of natural resources (such as protected wetlands or threatened and endangered species and their habitat), and occupational health and safety. These laws, rules, and regulations require us to obtain and maintain regulatory licenses, permits, and other approvals, comply with the requirements of such licenses, permits, and other approvals, and perform environmental impact studies prior to commencing new projects or making changes to existing projects.
We could be held liable for significant penalties and damages under certain environmental laws and regulations or be subject to revocation of certain licenses or permits, which could have a material adverse effect on our business, financial condition, and results of operations. We perform work, including directional drilling and site grading, in and around environmentally sensitive areas such as rivers, lakes, and wetlands. Due to the inconsistent nature of the terrain and water bodies, it is possible that such work may cause the release of subsurface materials that contain contaminants in excess of amounts permitted by law, potentially exposing us to remediation costs and fines.
For example, the Clean Water Act (the “CWA”) and comparable state laws and regulations applicable to our construction activities require us to establish authorization for the discharge of stormwater, which may require the development and implementation of a Stormwater Pollution Prevention Plan (“SWPPP”) to describe the construction activities and the pollution prevention practices that will be implemented in connection with those activities. Additionally, we lease or have care, custody, or control over numerous properties and facilities, including certain of which that contain fuel storage tanks or otherwise involve operations including the generation, use, storage, or management of hazardous materials and wastes. Under certain environmental laws, we could be held responsible for costs (including remediation costs and fines) relating to contamination at our past or present properties and facilities.
Our operations are also inherently hazardous and subject to extensive laws and regulations relating to the maintenance of safe conditions in the workplace. While we have invested substantial resources in our occupational health and safety programs, our industry involves a high degree of operational risk, and there can be no assurance that we will avoid significant liability exposure. We have suffered accidents in connection with our operations, and we anticipate that our operations may result in additional accidents in the future, some of which could be serious. As a result of these events, we could be subject to substantial penalties, revocation of operating licenses, criminal prosecution, or civil litigation, including claims for bodily injury or loss of life, that could result in substantial costs and liabilities.
Moreover, new or amended laws and regulations, changes in the interpretation of existing laws, and increased regulatory scrutiny could require us to incur significant costs or result in new or increased liabilities. For instance, changes to the definition of “waters of the United States” by the Environmental Protection Agency may broaden the scope of the CWA, potentially impacting construction activities near certain waterways. Although we maintain
54
Table of Contents
environmental insurance policies to address certain environmental risks, we can give no assurance that we will be able to maintain such policies in the future or that such policies will cover the full cost of environmental liabilities. The obligations, liabilities, fines, and costs associated with these events and conditions may be material and could have a material adverse effect on our business, financial condition, and results of operations.
Changes in tax laws or our tax estimates or positions could have a material adverse effect on our business, financial condition, and results of operations.
We are subject to extensive tax liabilities imposed by multiple jurisdictions, including income taxes, indirect taxes (excise/duty, sales/use, gross receipts, and value-added taxes), payroll taxes, franchise taxes, withholding taxes, and ad valorem taxes. New tax laws, treaties, and regulations, and changes in existing tax laws, treaties, and regulations, are continuously being enacted or proposed, all of which can result in significant changes to the tax rate on our earnings and have a material impact on our earnings and cash flows from operations. Since future changes to tax legislation and regulations are unknown, we cannot predict the ultimate impact such changes may have on our business.
In addition, significant judgment is required in determining our provision for income taxes. In the ordinary course of our business, there are many transactions and calculations where the ultimate tax determination is uncertain. We are and will be regularly under audit by tax authorities, and our tax estimates and tax positions could be materially affected by many factors, including the final outcome of tax audits and related litigation, the introduction of new tax accounting standards, legislation, regulations and related interpretations, our mix of earnings, our ability to realize deferred tax assets, and changes in uncertain tax positions. A significant increase in our tax rate or change to our tax positions could have a material adverse effect on our business, financial condition, and results of operations.
Our future effective tax rates could be subject to volatility or adversely affected by a number of factors, including: allocation of expenses to and among different jurisdictions; changes in the valuation of our deferred tax assets and liabilities; expected timing and amount of the release of any tax valuation allowances; tax effects of stock-based compensation; costs related to intercompany restructurings; changes in tax laws, tax treaties, regulations or interpretations thereof; or lower than anticipated future earnings in jurisdictions where we have lower statutory tax rates and higher than anticipated future earnings in jurisdictions where we have higher statutory tax rates. In addition, we may be subject to audits of our income, sales, and other taxes by U.S. federal, state, and local taxing authorities. Outcomes from these audits could have a material adverse effect on our business, financial condition, and results of operations.
Moreover, we may also trigger indemnification obligations to our customers if, on projects where we have agreed to comply with certain prevailing wage and apprenticeship standards or domestic content standards, we fail to do so and this causes our customers to lose bonus federal tax credits under the IRA. Any such indemnification obligations could be significant and could have a material adverse effect on our business, financial condition, and results of operations.
We could be adversely affected by our failure to comply with anti-corruption, anti-bribery, export control, and economic sanctions laws applicable to our business.
Applicable U.S. and non-U.S. anti-corruption and anti-bribery laws, including but not limited to the U.S. Foreign Corrupt Practices Act (“FCPA”), prohibit us from, among other things, corruptly making payments to non-U.S. officials for the purpose of obtaining or retaining business. Our policies mandate compliance with all applicable anti-corruption and anti-bribery laws, and our procedures and practices are designed to ensure that our employees and intermediaries comply with these laws. However, it is possible that our employees, subcontractors, agents, and partners may take actions in violation of our policies, company-wide standards, procedures, and anti-corruption and anti-bribery laws, and that the controls we undertake to facilitate lawful
55
Table of Contents
conduct, which include internal control policies, could be intentionally circumvented or become inadequate because of changed conditions. Liability for such actions or inadvertences could result in severe criminal or civil fines, penalties, forfeitures, disgorgements, or other sanctions, which in turn could have a material adverse effect on our reputation, business, financial condition, and results of operations. In addition, detecting, investigating, and resolving actual or alleged violations can be expensive and consume significant time and attention of our senior management, in-country management, and other personnel.
Additionally, pursuant to our EPC and other contracts where we have assumed responsibility to procure all or part of the materials needed for certain projects, we may source materials from outside the U.S. and be subject to non-U.S. laws associated with the procurement and transportation of such materials. The laws and regulations associated with such cross-border procurement activities are complex, and our failure to comply with such laws or regulations may result in criminal or civil fines, penalties, sanctions, or other liabilities, which could have a material adverse effect on our business, financial condition, and results of operations.
Our EPC services may also be subject to export control regulations, including the Export Administration Regulations administered by the U.S. Department of Commerce’s Bureau of Industry and Security. We are also subject to foreign assets control and economic sanctions regulations administered by the U.S. Department of the Treasury’s Office of Foreign Assets Control, which restrict or prohibit our ability to transact with certain foreign countries, individuals, and entities. Export control regulations may restrict our ability to exchange technical information with foreign manufacturers and suppliers, and economic sanctions regulations may restrict our ability to source from certain suppliers.
Although we believe our policies and procedures will mitigate the risk of violations of such laws, our employees and intermediaries may take actions in violation of our policies or these laws. Any such violation, even if prohibited by our policies, could subject us to criminal or civil penalties or other sanctions, which could have a material adverse effect on our reputation, business, financial condition, and results of operations. In addition, changes in U.S. foreign policy, including as a result of the new presidential administration, could lead to additional export barriers or economic sanctions being imposed against foreign jurisdictions. Any such change in U.S. foreign policy could restrict or prohibit our ability to transact with, source from, or export to certain foreign countries, individuals, and entities (including manufacturers and suppliers) or to conduct business outside of the U.S. Changes to U.S. foreign trade policy that restrict our ability to transact with other countries, individuals, or entities or to conduct business outside the U.S. could have a material adverse effect on our business, financial condition, and results of operations.
Our business may be adversely affected by risks associated with forced labor laws and supply chain traceability requirements, including the Uyghur Forced Labor Prevention Act.
A significant portion of the global supply of polysilicon, a critical raw material used in the production of crystalline silicon solar modules, is manufactured in the Xinjiang Uyghur Autonomous Region of the People’s Republic of China. The Uyghur Forced Labor Prevention Act (“UFLPA”), which became effective on June 21, 2022, establishes a rebuttable presumption that goods mined, produced, or manufactured, in whole or in part, in the Xinjiang Uyghur Autonomous Region, or by certain entities identified by the U.S. government, are produced using forced labor and are therefore prohibited from importation into the United States under Section 307 of the Tariff Act of 1930. U.S. Customs and Border Protection (“CBP”) actively enforces the UFLPA by detaining shipments of solar modules and related components at U.S. ports of entry pending review of supply chain documentation.
Although it is unusual for us to directly import solar modules, customers could request or require us to procure modules on their behalf, and where our customers procure modules directly, delays or detentions at the border can materially impact our project schedules. CBP detentions of solar module shipments have caused, and may continue to cause, significant delays in module deliveries, resulting in project schedule disruptions, potential
56
Table of Contents
liquidated damages exposure, increased storage and demurrage costs, and strained relationships with our customers. We and our suppliers may be required to invest significant resources in supply chain traceability and documentation systems to demonstrate compliance with the UFLPA, and there can be no assurance that such efforts will be sufficient to prevent detentions or that detained goods will ultimately be released. If we or our suppliers are unable to demonstrate to CBP’s satisfaction that solar modules in our supply chain were not produced using forced labor, such modules could be excluded from entry into the United States, requiring us to source alternative modules, potentially at higher cost and with extended lead times. More broadly, our projects depend on the timely delivery of customer-supplied equipment and materials, including modules, inverters, and trackers. Delays in the delivery of such customer-furnished equipment, whether due to UFLPA enforcement, other regulatory actions, supply chain disruptions, manufacturing delays, or transportation issues, can materially impact our project schedules, increase our costs, and expose us to potential liquidated damages, even though such delays are beyond our control. Any of the foregoing could have a material adverse effect on our business, financial condition, and results of operations.
Risks Related to Our Capital Structure
Our sole material asset after the completion of this offering will be our interest in CoVolt Holdings, and, as a result, we will depend on distributions from CoVolt Holdings to pay our taxes and expenses (including payments under the Tax Receivable Agreement) and pay dividends. CoVolt Holdings’ ability to make such distributions may be subject to various limitations and restrictions.
Upon the consummation of this offering, we will be a holding company and our sole material asset will be our interest in CoVolt Holdings. As such, we will have no independent means of generating revenue or cash flow, and our ability to pay our taxes and operating expenses or declare and pay dividends in the future, if any, will be dependent upon the financial results and cash flows of CoVolt Holdings and its subsidiaries and distributions we receive from CoVolt Holdings. There can be no assurance CoVolt Holdings will generate sufficient cash flow to distribute funds to us or that applicable state law and contractual restrictions, including negative covenants in any applicable debt instruments, will permit such distributions. CoVolt Holdings is currently, and may in the future be, subject to debt instruments or other agreements that restrict its ability to make distributions to us, which may in turn affect CoVolt Holdings’ ability to pay distributions to us and thereby adversely affect our cash flows.
We anticipate that CoVolt Holdings will continue to be classified as a partnership for U.S. federal income tax purposes and, as such, generally will not be subject to any entity-level U.S. federal income tax. Instead, any taxable income of CoVolt Holdings will be allocated to holders of Common Units, including us. Accordingly, we will incur income taxes on our allocable share of any net taxable income of CoVolt Holdings. Under the terms of the CoVolt Holdings LLC Agreement, CoVolt Holdings will be obligated, subject to various limitations and restrictions, including with respect to our debt agreements, to make tax distributions to holders of Common Units, including us. In addition to tax expenses, we will also incur expenses related to our operations, including payments under the Tax Receivable Agreement, which we expect will be significant. See “Certain Relationships and Related Party Transactions–Tax Receivable Agreement.” We intend, as its managing member, to cause CoVolt Holdings to make cash distributions to the holders of Common Units in an amount sufficient to (i) fund all of their tax obligations in respect of taxable income allocated to them and (ii) cover our operating expenses, including payments under the Tax Receivable Agreement. However, CoVolt Holdings’ ability to make such distributions may be subject to various limitations and restrictions, such as restrictions on distributions that would either violate any contract or agreement to which CoVolt Holdings is then a party, including debt agreements, or any applicable law, or that would have the effect of rendering CoVolt Holdings insolvent. If we do not have sufficient funds to pay tax or other liabilities, or to fund our operations (including, if applicable, because of an acceleration of our obligations under the Tax Receivable Agreement), we may have to borrow funds, which could materially and adversely affect our liquidity and financial condition, and subject us to
57
Table of Contents
various restrictions imposed by any lenders of such funds. To the extent we are unable to make timely payments under the Tax Receivable Agreement for any reason, such payments generally will be deferred and will accrue interest until paid; provided, however, that nonpayment for a specified period may constitute a material breach of a material obligation under the Tax Receivable Agreement resulting in the acceleration of payments due under the Tax Receivable Agreement. See “Certain Relationships and Related Party Transactions–Tax Receivable Agreement.”
In addition, if CoVolt Holdings does not have sufficient funds to make distributions, our ability to declare and pay cash dividends will also be restricted or impaired, although we do not anticipate declaring or paying any cash dividends on our Class A common stock in the foreseeable future. See “Dividend Policy.”
Under the CoVolt Holdings LLC Agreement, we intend to cause CoVolt Holdings, from time to time, to make distributions in cash to the holders of Common Units (including us) in amounts sufficient to cover the taxes imposed on their allocable share of taxable income of CoVolt Holdings. As a result of (i) potential differences in the amount of net taxable income allocable to us and to the other holders of Common Units, (ii) the significantly lower tax rate applicable to corporations as opposed to non-corporate taxpayers, and (iii) certain tax benefits covered by, and payments under, the Tax Receivable Agreement, these tax distributions may be in amounts that significantly exceed our tax liabilities. Our board of directors will determine the appropriate uses for any excess cash so accumulated, which may include, among other uses, the payment of obligations under the Tax Receivable Agreement and the payment of other expenses. We will have no obligation to distribute such cash (or other available cash) to our shareholders. As a result, the holders of Common Units (other than us) may benefit from value, if any, attributable to such cash balances if they acquire shares of Class A common stock in exchange for their Common Units, notwithstanding that such holders may have participated previously as holders of Common Units in distributions that resulted in such excess cash balances to us. See “Description of Capital Stock.” To the extent we do not distribute such excess cash as distributions on our Class A common stock we may take other actions with respect to such excess cash, for example, holding such excess cash, or lending or contributing it (or a portion thereof) to CoVolt Holdings, which may result in shares of our Class A common stock increasing in value relative to the value of Common Units.
The tax distributions to the holders of Common Units (including us) may be substantial and may, in the aggregate, exceed the amount of taxes that CoVolt Holdings would have paid if it were a similarly situated corporate taxpayer. Funds used by CoVolt Holdings to satisfy its obligation to make tax distributions will not be available for reinvestment in our business, except to the extent we or certain other Continuing Equity Owners use any excess cash received to reinvest in CoVolt Holdings for additional Common Units. Moreover, because cash available for additional tax distributions will be determined by taking into account the ability of CoVolt Holdings and its subsidiaries to take on additional borrowing, CoVolt Holdings may be required to increase its indebtedness in order to fund additional tax distributions. Such additional borrowing may adversely affect our results of operations, cash flows and financial position by, without limitation, limiting our ability to borrow in the future for other purposes, such as capital expenditures, and increasing our interest expense and leverage ratios.
The Tax Receivable Agreement with CoVolt Holdings and the TRA Holders requires us to make cash payments to the TRA Holders in respect of certain tax benefits to which we may become entitled, and we expect that such payments will be substantial.
In connection with the completion of this offering, we will enter into the Tax Receivable Agreement with CoVolt Holdings and the TRA Holders. Under the Tax Receivable Agreement, we will be required to make cash payments to the TRA Holders equal to % of the cash tax savings, if any, that we actually realize, or in certain circumstances are deemed to realize, as a result of Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions. We will be required to make such payments to
58
Table of Contents
the TRA Holders even if all of the TRA Holders were to exchange or redeem their remaining Common Units and were to dispose of any other interest they hold in us. The payment obligations under the Tax Receivable Agreement are an obligation of us and not of CoVolt Holdings. We expect that the amount of the cash payments we will be required to make under the Tax Receivable Agreement will be substantial. Any payments made by us to the TRA Holders under the Tax Receivable Agreement will not be available for reinvestment in our business and will generally reduce the amount of overall cash flow that might have otherwise been available to us. To the extent that we are unable to make timely payments under the Tax Receivable Agreement for any reason, the unpaid amounts will be deferred and will accrue interest until paid by us; provided, however, that nonpayment for a specified period may constitute a material breach of a material obligation under the Tax Receivable Agreement resulting in the acceleration of payments due under the Tax Receivable Agreement. See “Certain Relationships and Related Party Transactions–Tax Receivable Agreement.” Payments under the Tax Receivable Agreement are not conditioned upon continued ownership of CoVolt Holdings by the exchanging TRA Holders.
Assuming no material changes in the relevant tax laws and that we earn sufficient taxable income to realize all tax benefits that are subject to the Tax Receivable Agreement, we expect that the tax savings associated with Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions, would aggregate to approximately $ million over -years from the date of this offering based on the initial public offering price of $ per share of our Class A common stock, and assuming all redemptions or exchanges would occur immediately after the initial public offering for the remaining ownership of CoVolt Holdings not acquired by us, which is assumed to occur on , 2026 for purposes of the pro forma information presented herein and elsewhere in this prospectus. Under such scenario, assuming future payments are made on the date each relevant tax return is due, without extensions, we would be required to pay approximately % of such amount, or approximately $ million, over the -year period from the date of this offering, to the TRA Holders. The actual Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions and the actual utilization of any resulting tax benefits, as well as the amount and timing of any payments under the Tax Receivable Agreement, will vary depending upon a number of factors including: the timing of redemptions by the TRA Holders; the price of shares of our Class A common stock at the time of the exchange; the extent to which such exchanges are taxable; the amount of gain recognized by such TRA Holders; the amount and timing of the taxable income allocated to us or otherwise generated by us in the future; the portion of our payments under the Tax Receivable Agreement constituting imputed interest; and the federal and state tax rates then applicable.
Our organizational structure, including the Tax Receivable Agreement, confers certain benefits upon the Continuing Equity Owners that will not benefit holders of our Class A common stock to the same extent that it will benefit the Continuing Equity Owners.
Our organizational structure, including the Tax Receivable Agreement, confers certain benefits upon the Continuing Equity Owners that will not benefit the holders of our Class A common stock to the same extent that it will benefit the Continuing Equity Owners, including upon a change of control transaction. We will enter into the Tax Receivable Agreement with CoVolt Holdings and the TRA Holders in connection with the completion of this offering, which will provide for the payment by us to the TRA Holders of % of the amount of tax benefits, if any, that we actually realize, or in some circumstances are deemed to realize, as a result of Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions arising from payments under the Tax Receivable Agreement. See “Certain Relationships and Related Party Transactions–Tax Receivable Agreement.” Although we will retain % of the amount of such tax benefits, this and other aspects of our organizational structure may adversely impact the future trading market for our Class A common stock.
59
Table of Contents
In certain cases, payments under the Tax Receivable Agreement to the TRA Holders may be accelerated or significantly exceed any actual benefits we realize in respect of the tax attributes subject to the Tax Receivable Agreement.
The Tax Receivable Agreement will generally apply to each of our taxable years, beginning with the first taxable year ending after the consummation of this offering. There is no maximum term for the Tax Receivable Agreement. However, the Tax Receivable Agreement will provide that if (i) we materially breach any of our material obligations under the Tax Receivable Agreement, (ii) certain mergers, asset sales, other forms of business combinations or other changes of control occur after the consummation of this offering, or (iii) we elect an early termination of the Tax Receivable Agreement, then our obligations, or our successor’s obligations, under the Tax Receivable Agreement to make payments will be accelerated, and we would be required to make an immediate cash payment equal to the present value of the anticipated future tax benefits that are the subject of the Tax Receivable Agreement, based on certain assumptions, which payment may be made significantly in advance of the actual realization, if any, of such future tax benefits. Such cash payment to the TRA Holders could be greater than the specified percentage of any actual benefits we ultimately realize in respect of the tax benefits that are subject to the Tax Receivable Agreement. In these situations, our obligations under the Tax Receivable Agreement could have a substantial negative impact on our liquidity and could have the effect of delaying, deferring, or preventing certain mergers, asset sales, other forms of business combinations or other changes of control. There can be no assurance that we will be able to fund or finance our obligations under the Tax Receivable Agreement. We may need to incur debt to finance payments under the Tax Receivable Agreement to the extent our cash resources are insufficient to meet our obligations under the Tax Receivable Agreement as a result of timing discrepancies or otherwise.
We will not be reimbursed for any payments made to the TRA Holders under the Tax Receivable Agreement in the event that any tax benefits are disallowed.
Payments under the Tax Receivable Agreement will be based on the tax reporting positions that we determine, and the IRS, or another tax authority, may challenge all or part of the Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis, Interest Deductions or other tax benefits we claim, as well as other related tax positions we take, and a court could sustain such challenge. If the outcome of any such challenge would reasonably be expected to materially affect the rights and obligations of TRA Holders under the Tax Receivable Agreement, then our ability to settle such challenges may be restricted by the rights of the TRA Holders pursuant to the Tax Receivable Agreement, and such restrictions apply for as long as the Tax Receivable Agreement remains in effect. The interests of the TRA Holders in any such challenge may differ from or conflict with our interests and your interests, and the TRA Holders may exercise their consent rights relating to any such challenge in a manner adverse to our interests and your interests. We will not be reimbursed for any cash payments previously made to the TRA Holders under the Tax Receivable Agreement in the event that any tax benefits initially claimed by us and for which payment has been made to a TRA Holder are subsequently challenged by a taxing authority and are ultimately disallowed. Instead, any excess cash payments made by us to a TRA Holder will be netted against future cash payments, if any, that we might otherwise be required to make to such TRA Holder, under the terms of the Tax Receivable Agreement. However, we might not determine that we have effectively made an excess cash payment to a TRA Holder for a number of years following the initial time of such payment. Moreover, the excess cash payments we made previously under the Tax Receivable Agreement could be greater than the amount of future cash payments against which we would otherwise be permitted to net such excess. The applicable U.S. federal income tax rules for determining applicable tax benefits we may claim are complex and factual in nature, and there can be no assurance that the IRS or a court will agree with our tax reporting positions. As a result, payments could be made under the Tax Receivable Agreement significantly in excess of any actual cash tax savings that we realize in respect of the tax attributes with respect to a TRA Holder that are the subject of the Tax Receivable Agreement.
60
Table of Contents
The acceleration of payments under the Tax Receivable Agreement in the case of an early termination, certain changes of control or a material breach may negatively impact the value received by owners of our Class A common stock.
The Tax Receivable Agreement will provide that if we elect an early termination of the Tax Receivable Agreement, upon certain mergers, asset sales or other forms of business combination or certain other changes of control, or in the event of a material breach by the Company, our (or our successor’s) obligations with respect to the Tax Receivable Agreement would be accelerated, and we would be required to make an immediate cash payment, which may be substantial, equal to the present value of the anticipated future tax benefits that are the subject of the Tax Receivable Agreement based on certain assumptions, including that we (or our successor) would have sufficient taxable income to fully utilize the benefits arising from the increased tax deductions and tax basis and other benefits covered by the Tax Receivable Agreement. Consequently, it is possible, in these circumstances, that the actual cash tax savings realized by us may be significantly less than the corresponding tax benefit payments under the Tax Receivable Agreement. Our accelerated payment obligations and assumptions adopted under the Tax Receivable Agreement in the case of an early termination, change of control or a material breach may negatively impact the value received by owners of our Class A common stock in a change of control transaction.
The Continuing Equity Owners may have conflicting interests with holders of shares of our Class A common stock.
Because certain Continuing Equity Owners hold their ownership interest in our business directly in CoVolt Holdings, rather than through the Company, the Continuing Equity Owners may have conflicting interests with holders of shares of our Class A common stock. For example, if CoVolt Holdings makes distributions to the Company, the non-managing members of CoVolt Holdings will also be entitled to receive such distributions pro rata in accordance with their ownership of Common Units and their preferences as to the timing and amount of any such distributions may differ from those of our public shareholders. The Continuing Equity Owners may also have different tax positions from us that could influence their decisions regarding whether and when to dispose of assets, especially in light of the existence of the Tax Receivable Agreement that we entered into in connection with this offering with CoVolt Holdings and the TRA Holders, whether and when to incur new or refinance existing indebtedness and whether and when we should terminate the Tax Receivable Agreement and accelerate our obligations thereunder. In addition, the structuring of future transactions may take into consideration our Continuing Equity Owners’ tax or other considerations even where no similar benefit would accrue to us. See “Certain Relationships and Related Party Transactions–Tax Receivable Agreement.” Additionally, conflicts may arise between holders of Class A common stock and the Continuing Equity Owners with respect to tax distributions, payments under the Tax Receivable Agreement, the timing of exchanges of Common Units, dividend policy and cash management. Because our board of directors may include directors affiliated with the Continuing Equity Owners, such directors may influence decisions that benefit the Continuing Equity Owners at the expense of holders of Class A common stock. Furthermore, our obligation to make payments under the Tax Receivable Agreement and certain procedural provisions in the CoVolt Holdings LLC Agreement associated with certain changes of control could make us a less attractive target for an acquisition or could result in holders of our Class A common stock receiving less consideration in connection with a change of control transaction than they would otherwise receive.
Our shares of Class B common stock will not have economic rights.
Immediately following the consummation of this offering, all of our Class B common stock will be held by certain Continuing Equity Owners. Each share of Class A common stock entitles the holder to one vote per share and each share of Class B common stock entitles the holder to one vote per share on all matters on which shareholders are entitled to vote generally. For a description of our multi-class structure, see “Description of Capital Stock.”
61
Table of Contents
If CoVolt Holdings were to become a publicly traded partnership taxable as a corporation for U.S. federal income tax purposes, significant tax inefficiencies might result, and we would not be able to recover payments we previously made under the Tax Receivable Agreement even if the corresponding tax benefits were subsequently determined to have been unavailable due to such status.
We intend to operate such that CoVolt Holdings does not become a publicly traded partnership taxable as a corporation for U.S. federal income tax purposes. A “publicly traded partnership” is a partnership the interests of which are traded on an established securities market or are readily tradable on a secondary market or the substantial equivalent thereof. Under certain circumstances, redemptions of Common Units pursuant to the CoVolt Holdings LLC Agreement or other transfers of Common Units could cause CoVolt Holdings to be treated as a publicly traded partnership. Applicable U.S. Treasury regulations provide for certain safe harbors from treatment as a publicly traded partnership, and we intend to operate such that redemptions or other transfers of Common Units qualify for one or more such safe harbors. If CoVolt Holdings were to become a publicly traded partnership, significant tax inefficiencies might result for us and for CoVolt Holdings, including as a result of our inability to file a consolidated U.S. federal income tax return with CoVolt Holdings. In addition, we may not be able to realize tax benefits covered under the Tax Receivable Agreement, and we would not be able to recover any payments previously made by us under the Tax Receivable Agreement, even if the corresponding tax benefits (including any claimed increase in the tax basis of CoVolt Holdings’ assets) were subsequently determined to have been unavailable.
If we were deemed to be an investment company under the Investment Company Act of 1940, as amended (the “1940 Act”), as a result of our ownership of CoVolt Holdings, applicable restrictions could make it impractical for us to continue our business as contemplated and could have a material adverse effect on our business.
Under Sections 3(a)(1)(A) and (C) of the 1940 Act, a company generally will be deemed to be an “investment company” for purposes of the 1940 Act if (i) it is, or holds itself out as being, engaged primarily, or proposes to engage primarily, in the business of investing, reinvesting or trading in securities, or (ii) it engages, or proposes to engage, in the business of investing, reinvesting, owning, holding, or trading in securities and it owns or proposes to acquire investment securities having a value exceeding 40% of the value of its total assets (exclusive of U.S. government securities and cash items) on an unconsolidated basis. We do not believe that we are an “investment company,” as such term is defined in either of those sections of the 1940 Act.
We and CoVolt Holdings intend to conduct our operations so that we will not be deemed an investment company. As the sole managing member of CoVolt Holdings, we will control and operate CoVolt Holdings. On that basis, we believe that our interest in CoVolt Holdings is not an “investment security” as that term is used in the 1940 Act. However, if we were to cease participation in the management of CoVolt Holdings, or if CoVolt Holdings itself becomes an investment company, our interest in CoVolt Holdings could be deemed an “investment security” for purposes of the 1940 Act. If it were established that we were an unregistered investment company, there would be a risk that we would be subject to monetary penalties and injunctive relief in an action brought by the SEC, that we would be unable to enforce contracts with third parties and that third parties could seek to obtain rescission of transactions undertaken during the period it was established that we were an unregistered investment company. If we were required to register as an investment company, restrictions imposed by the 1940 Act, including limitations on our capital structure and our ability to transact with affiliates, could make it impractical for us to continue our business as contemplated and could have a material adverse effect on our business.
62
Table of Contents
Risks Related to Owning Our Class A Common Stock
The market price of our Class A common stock may be volatile, which could cause the value of an investment in our stock to decline.
The market price of our Class A common stock may experience significant fluctuations due to a variety of factors, many of which are beyond our control. These factors include announcements related to our competitors, the utility-scale solar and energy storage EPC industry or the broader economy; strategic actions taken by us or our competitors, such as mergers, acquisitions, or restructurings; media coverage and publications regarding our project awards, execution, safety/quality performance, and the utility-scale solar and storage projects we construct; new regulatory developments and changes in regulatory guidelines; fluctuations in the cost of solar modules, inverters, racking systems, transformers, switchgear and steel, and battery energy storage components; announcements concerning the availability of critical equipment and components for our EPC operations (including modules, inverters, racking, transformers, switchgear, and BESS components), as well as the availability of skilled labor, subcontractors, and surety bonding capacity; general and industry-specific economic conditions; changes in financial estimates or recommendations by securities analysts, or our failure to meet analysts’ performance expectations; sales of our Class A common stock or other actions by investors with significant shareholdings; and general market, political, and other economic conditions.
The stock markets in general have experienced substantial volatility that has often been unrelated to the operating performance of particular companies. These types of broad market fluctuations may adversely affect the trading price of our Class A common stock. In the past, shareholders have sometimes instituted securities class action litigation against companies following periods of volatility in the market price of their securities. Any similar litigation against us could result in substantial costs, divert management’s attention and resources, and harm our business or results of operations.
Prior to this offering, there has been no established public market for our Class A common stock, and we cannot guarantee that an active and liquid trading market will develop or be maintained post-offering.
While we have submitted an application to list our Class A common stock on, there is no assurance that our application will be approved, that approval will occur within our expected timeframe, or that we will satisfy all initial and ongoing listing standards. We may need to implement additional governance, committee, independence, internal control, and reporting measures to qualify, which could be time-consuming and costly. If our application is not approved, or if we are later unable to maintain compliance with continued listing requirements, our Class A common stock may trade on an over-the-counter market, which generally provides less liquidity, wider bid-ask spreads, limited analyst coverage, and greater price volatility. Over-the-counter trading can also subject transactions to additional broker-dealer suitability and disclosure requirements, including potential “penny stock” rules if our share price falls below certain thresholds, further reducing trading activity and investor participation.
Even if our listing is approved, an active and liquid trading market for our Class A common stock may not develop or be sustained. Factors such as limited public float, concentrated ownership, lock-up expirations, small-cap status, market maker participation, and variability in analyst coverage can constrain trading volume and contribute to significant price swings. The market price of our Class A common stock may be volatile and influenced by matters outside our control, including interest rate movements, macroeconomic conditions, sector sentiment toward clean energy companies, regulatory and policy developments, and news or performance of competitors and partners. Trading halts, short selling, technical factors, and index inclusion or exclusion may amplify volatility. A failure to achieve or maintain an active market could impair shareholder liquidity, limit our ability to raise additional equity capital on acceptable terms, reduce the utility of our stock as
63
Table of Contents
acquisition currency or for employee compensation, and adversely affect our valuation. As a result, shareholders may be unable to realize the value of their investment, which could have a material adverse effect on our business, results of operations, and financial condition.
Control by our Continuing Equity Owners could adversely affect our other shareholders.
Following this offering, our Continuing Equity Owners will beneficially own a significant portion of our Class A common stock. As a result, they will be able to exert substantial influence over the election and removal of directors, approval of mergers, consolidations, or sales of all or a majority of assets, issuances of equity or equity-linked securities, amendments to our charter and bylaws, and other significant corporate transactions and policies, including our dividend policy and financing strategy. This concentrated ownership may limit the ability of other shareholders to influence corporate matters and outcomes at shareholder meetings, and may enable our Continuing Equity Owners to cause or prevent corporate actions that other shareholders may view as beneficial.
Further, under the Shareholders Agreement, certain corporate actions and corporate governance matters will be subject to the approval of the Continuing Equity Owners party thereto for so long as such Continuing Equity Owners beneficially own at least % of our total common stock, including (i) amendments to our Amended Charter or Amended Bylaws, (ii) entering into or effecting a change in control, and (iii) entering into any agreement providing for the acquisition or divestiture of assets or equity securities in excess of $200 million, among others. Additionally, each of the Continuing Equity Owners, subject to certain ownership thresholds, will be entitled to propose to our nominating and corporate governance committee a number of individuals for nomination and election to our board of directors, and we shall be obligated to take certain actions within our control to cause such nominating and corporate governance committee to nominate such individuals to our board of directors and to cause them to be included in our proxy statement and recommend their election. See “Certain Relationships and Related Party Transactions—Shareholders Agreement.” It is possible that the Continuing Equity Owners have interests that are materially different from those of shareholders, and such Continuing Equity Owners may exercise their approval rights or director designation rights in a way that is adverse to shareholders or in a manner with which they disagree.
Our Continuing Equity Owners include several distinct and unaffiliated investor groups, each of which is completing separate restructuring transactions in connection with this offering, including certain blocker mergers intended to qualify for specific tax treatment. Because these investor groups are not affiliated with one another, they may have differing, and at times conflicting, interests, tax positions, and liquidity objectives following this offering. In addition, the completion of these transactions, including the Blocker Mergers and the pre-closing restructuring of certain investors’ holdings, involves multiple steps that must occur in sequence immediately before and after the closing of this offering. Any delay or failure to complete any of these steps as planned could delay the closing of this offering or require modifications to our organizational structure.
The interests and investment horizons of our Continuing Equity Owners may differ from those of our other shareholders due to factors such as fund life cycles, liquidity needs, tax positions, or strategic relationships with customers, suppliers, or financing partners. They may be inclined to approve or reject acquisitions, financings, or other transactions that prioritize their objectives, even where other shareholders might prefer a different course. Their influence could deter, delay, or prevent a change in control, reduce the likelihood of unsolicited or competing bids, or result in the rejection of a transaction that would provide a premium to our shareholders. Concentrated ownership can also reduce our public float, which may limit trading liquidity, widen bid-ask spreads, heighten volatility, and affect index inclusion or institutional investor interest. In addition, registration rights held by significant shareholders may facilitate sizable resales following applicable lock-ups, contributing to market overhang and price pressure. Sales of large blocks, or the transfer of a controlling stake without a control premium to all shareholders, could adversely affect the market price of our Class A common stock.
64
Table of Contents
Conflicts of interest may also arise in connection with related party transactions, which, although subject to our corporate governance policies and applicable law, could nonetheless create the appearance of preferential treatment. Any of these dynamics could negatively affect investor confidence, our valuation, and the opportunity for shareholders to realize returns on their investment.
We will be a “controlled company” within the meaning of the rules of the NYSE and, as a result, will qualify for, and intend to rely upon, exemptions from certain corporate governance requirements. If we rely on such exemptions, you will not have the same protections afforded to shareholders of companies that are subject to such requirements.
Upon the closing of this offering, certain of our Continuing Equity Owners will collectively hold a majority of the combined voting power of our shares eligible to vote for the election of our directors. As a result, we will to be a “controlled company” within the meaning of the NYSE corporate governance standards. Under these corporate governance standards, a company of which more than 50% of the voting power for the election of directors is held by an individual, group or another company is a “controlled company” and may elect not to comply with certain corporate governance requirements. For example, controlled companies: are not required to have a board that is composed of a majority of “independent directors,” as defined under NYSE rules; are not required to have a compensation committee that is composed entirely of independent directors; and are not required to have a nominating and corporate governance committee that is comprised entirely of independent directors. We intend to rely upon certain of these exemptions. Accordingly, you will not have the same protections afforded to shareholders of companies that are subject to all of the corporate governance requirements of the NYSE. Our status as a controlled company could make our Class A common stock less attractive to some investors or otherwise harm our stock price. In the event that we cease to be a “controlled company” and our Class A common stock continues to be listed on the NYSE, we will be required to comply with these provisions within the applicable transition periods.
Future stock issuances could result in significant dilution to our existing shareholders, affecting the value of their investment and their voting power.
As part of our growth strategy, we may need to raise additional capital through the issuance of equity securities, including common stock, preferred stock, or securities convertible into common stock. We may pursue underwritten offerings, private placements, PIPE transactions, at-the-market programs, or equity-linked instruments such as convertible notes or warrants to fund operations, provide working capital for fixed price EPC contracts, invest in project execution capabilities (including engineering, preconstruction, equipment fleet, and safety/quality systems), expand into new geographies or adjacent services (such as balance-of-plant scopes and BESS integration), support acquisitions, or bolster liquidity. Market conditions may require us to issue equity at depressed prices or on accelerated timelines, and investor demand may dictate structures that are more dilutive than traditional offerings. The issuance of additional shares would dilute existing shareholders’ ownership and voting interests, reduce earnings per share, and could adversely affect the market price of our Class A common stock. If we issue preferred stock or other securities with rights, preferences, or privileges senior to those of our Class A common stock, holders of Class A common stock could be adversely affected by dividend priority, liquidation preference, conversion or redemption features, board designation rights, or voting provisions.
Equity-linked financings can result in future dilution upon conversion or exercise, and counterparties may hedge their exposure through short sales or other transactions that increase selling pressure on our stock. Existing securities may contain anti-dilution, price protection, or reset features that amplify dilution in down-round scenarios. Registration rights, lock-up expirations, and S-8 registrations for equity compensation can add to market overhang and volatility as new shares become freely tradable. Strategic transactions, including acquisitions paid with equity, could further dilute current shareholders and shift control or influence. Stock exchange rules and corporate approvals may constrain timing and size of offerings; however, even where
65
Table of Contents
approvals are obtained, issuance terms may not be favorable. While we strive to manage our capital structure and minimize dilution, the need for additional financing may arise unexpectedly due to macroeconomic conditions, policy, permitting, or transmission/interconnection developments, supply chain constraints, counterparty financing capacity, or strategic opportunities. We cannot assure you that future issuances will not materially dilute your investment, that they will be conducted on favorable terms, or that the market will absorb new shares without adverse price impact.
We do not intend to pay dividends for the foreseeable future, and investors must rely on stock price appreciation for a return.
We currently intend to retain all available earnings, if any, to fund operations, invest in growth, and strengthen our balance sheet, and therefore do not expect to declare or pay cash dividends for the foreseeable future. Any future determination to pay dividends would be at the discretion of our Board and subject to applicable law, our financial condition and results, capital expenditure and investment requirements, anticipated cash needs, and restrictions in existing and future debt or other financing arrangements. Our capital allocation priorities include funding working capital and bonding capacity for fixed-price EPC contracts, investing in engineering, preconstruction, and field execution resources, enhancing safety and quality systems, maintaining and upgrading equipment and IT/ERP systems, expanding utility-scale solar and BESS delivery capabilities and geographic reach, and maintaining adequate liquidity to navigate permitting, supply chain, and transmission/interconnection dynamics in utility-scale solar energy and battery storage. Debt covenants and restricted payment provisions may limit our ability to return capital, and future equity or debt financings may include similar limitations. We may also elect to prioritize growth investments over capital returns, and we are not obligated to initiate share repurchases. As a result, the only way for investors to realize a return may be through appreciation in the market price of our Class A common stock, which is not assured.
The market price of our Class A common stock may be volatile and influenced by factors outside our control, including interest rate movements, macroeconomic conditions, shifts in investor sentiment toward growth or clean energy companies, changes in regulatory or policy frameworks, and developments affecting our competitors or partners. Limited public float, lock-up expirations, sales by large shareholders, short selling activity, index inclusion or exclusion, and limited analyst coverage can exacerbate price swings. Our results may fluctuate due to timing of contract awards and NTPs, weather impacts on construction schedules, permitting and interconnection timing, change order recovery, labor availability, and supply chain dynamics, and any failure to meet guidance or analyst expectations could depress the stock. Negative publicity, litigation, securities law claims, or governmental inquiries may also weigh on trading levels. In addition, we rely on equity-based compensation to attract and retain talent, and future grants or share issuances, including in connection with acquisitions or capital raises, may dilute existing shareholders and create additional selling pressure upon vesting and settlement. If our stock price declines or remains stagnant, investors may be unable to sell shares at or above their purchase price, and the absence of dividends could further reduce total returns and the attractiveness of our Class A common stock.
Texas law and our corporate governance documents contain provisions that may delay or prevent a change of control, which could adversely affect the price of our Class A common stock.
Our charter, bylaws, and applicable state corporate law contain provisions intended to protect the interests of the company and its shareholders by discouraging coercive takeover tactics and inadequate bids. These provisions may, however, deter potential acquirers from pursuing transactions that could provide shareholders a premium. Key measures include a classified board of directors with staggered three-year terms, which prevents shareholders from electing an entirely new board at a single annual meeting, and advance notice requirements for shareholder nominations and proposals that limit the ability to effect changes without sufficient lead time. Our bylaws permit only the Chairman of the Board, or our corporate secretary at the direction of the board, to call special meetings of shareholders, which restricts shareholder action between
66
Table of Contents
annual meetings. In addition, our board has authority to issue “blank check” preferred stock without shareholder approval, and to set voting, dividend, conversion, and other rights, which could be used to implement a rights plan or otherwise dilute the voting power of common shareholders.
We are also subject to provisions of Texas law, or other applicable state corporate statutes, that restrict business combinations with interested shareholders for a period of time unless specified approvals are obtained. Certain other governance features can further entrench the status quo, including limits on shareholder action by written consent, the board’s ability to fill vacancies, supermajority voting requirements to amend parts of our charter or bylaws, and any exclusive forum provisions that may make litigation or proxy contests more difficult to pursue. The underwriters or a future board could adopt or amend rights plans without shareholder approval, and authorized but unissued shares may be issued to a friendly party, making an unsolicited bid more costly or impractical. While these protections are designed to promote long-term value and orderly governance, they may limit shareholder ability to influence corporate matters, delay or discourage change-in-control transactions, reduce the likelihood of a negotiated premium, and contribute to a perception of entrenchment. As a result, the market price of our Class A common stock could be adversely affected, and shareholders may not realize the full value of their investment.
Our exclusive forum provisions could limit our shareholders’ ability to obtain a favorable judicial forum for disputes with us or our directors, officers, employees, or agents.
Under our Amended Charter, the Business Court in the Eleventh Business Court Division of the State of Texas will serve as the exclusive forum for the following categories of legal actions or proceedings governed by Texas statutory or common law:
| • | derivative suits or proceedings initiated on behalf of the Company; |
| • | claims alleging that any of our directors, officers, employees, or agents breached a fiduciary duty owed to us or our shareholders; |
| • | claims against us or any of our directors, officers, or employees that arise under the TBOC or Amended Charter; and |
| • | claims against us or any of our directors, officers, or employees relating to other entity claims as that term is defined in Section 2.115 of the TBOC. |
These forum selection provisions do not apply to actions seeking to enforce obligations or liabilities arising under the Exchange Act, the Securities Act, or any other claims within the exclusive jurisdiction of the federal courts. For such federal securities law claims, our Amended Charter will designate the United States District Court for the Southern District of Texas as the sole and exclusive forum, to the fullest extent permitted by applicable law.
These forum selection provisions may restrict a shareholder’s ability to pursue claims in a judicial forum that the shareholder considers more favorable for disputes involving us, our directors, officers, employees, agents, or other shareholders. This could discourage litigation against us and such persons and may increase the costs to shareholders of bringing such claims. Additionally, if a court determines that these provisions are inapplicable or unenforceable with respect to any of the covered actions or proceedings, we could face additional expenses in litigating such matters in other jurisdictions, which could negatively impact our results of operations, cash flows, and financial condition.
The body of case law interpreting the TBOC is less developed than the body of case law interpreting the Delaware General Corporation Law, and the Texas Business Court has less precedent to draw from adjudicating corporate and business-related matters.
As a Texas corporation, we will be subject to the TBOC. The body of case law interpreting the TBOC is less developed than the body of case law interpreting the Delaware General Corporation Law and many other state
67
Table of Contents
corporate laws. The newly created Texas Business Court is in its infancy, began hearing cases in September 2024 and will need time to build a body of case law that provides comparable levels of guidance to directors and officers as might be available in Delaware, which may result in less certainty for our officers and directors as well as our shareholders.
The TBOC has been recently amended to provide additional protections for our officers, directors and affiliates while making it more difficult for shareholders to make proposals at our annual meeting or to bring derivative claims. As a result, our shareholders may be disadvantaged as compared to shareholders of Delaware corporations.
In an effort to attract U.S. corporations to reincorporate in and move their respective headquarters to Texas, the Texas legislature has passed a number of changes to the TBOC. For example, the TBOC was recently amended to (i) permit broad exculpation of officers along with directors for breaches of duty of care pursuant to Senate Bill 2411, which took effect on September 1, 2025, (ii) put certain limitations on shareholder derivative lawsuits, including a 3% ownership requirement to bring such a claim, pursuant to Senate Bill 29, which became effective on May 14, 2025, and (iii) streamline approval of mergers and other fundamental transactions, including by eliminating class voting requirements. Senate Bill 1057, which took effect on September 1, 2025, imposes stock ownership requirements for shareholders seeking to submit shareholder proposals at an annual or special meeting. Taken together, these TBOC provisions mean our shareholders may be disadvantaged as compared to shareholders of Delaware corporations.
Substantial future sales, expirations of lock-ups, or the perception that such sales could occur, may depress our stock price.
Following this offering, a substantial number of our outstanding shares will be restricted from immediate resale under lock-up agreements or applicable securities laws, but will become eligible for sale upon expiration of the lock-up period or satisfaction of other conditions. In addition, a substantial number of our outstanding shares will be covered by registration rights, and registration of any of these outstanding shares would result in such shares becoming freely tradable without compliance with Rule 144 upon effectiveness of the registration statement. Sales of a significant number of shares into the public market after the lock-up period ends, or as shareholders exercise their registration rights or the perception that such sales may occur, could cause the market price of our Class A common stock to decline, particularly if demand for our shares does not increase to absorb the additional supply or if trading liquidity is limited. J.P. Morgan Securities LLC and Jefferies LLC may, in their discretion, release shareholders from lock up restrictions before the scheduled expiration, which could accelerate the timing of sales and intensify downward pressure.
Significant shareholders, including our directors, executive officers, and principal investors, will own a substantial portion of our outstanding shares after the offering. Sales by these holders, programmed trading under Rule 10b5-1 plans, tax withholding related to RSU settlements, or option exercise related sales, or the perception that such sales may occur, could materially depress our stock price even if our underlying business fundamentals remain unchanged. Rule 144 and other exemptions may permit additional resales once holding periods and other conditions are met. Market conditions can amplify these effects, including broader volatility, short selling activity, index inclusion or exclusion, analyst coverage changes, and limited float. We may also issue additional shares of Class A common stock or securities convertible into or exchangeable for Class A common stock in the future to raise capital, pursue strategic transactions, or provide equity compensation. Any such issuance could be dilutive to existing shareholders and, depending on size, timing, and structure, could materially affect the trading price of our Class A common stock and reduce earnings per share. Further, at our request, the underwriters have reserved for sale, at the initial public offering price, up to % of the Class A common stock being offered for sale, to our directors, officers, and certain employees and other related parties. Except for any shares acquired by our directors and officers, shares purchased pursuant to the directed share program will not be subject to lock-up
68
Table of Contents
agreements with the underwriters. See “Underwriting–Directed Share Program.” If our stock price is volatile or declines, or if our results do not meet investor expectations, shareholders may be more likely to sell when restrictions lapse, further pressuring the stock. These dynamics could impair our ability to raise equity capital on favorable terms, limit strategic flexibility, and adversely affect the value of an investment in our Class A common stock.
If securities or industry analysts do not initiate or maintain coverage of us, or publish unfavorable research, our stock price and trading volume could decline.
The trading market for our Class A common stock will depend in part on research and reports that securities or industry analysts publish about us, our sector, and our competitors. If one or more analysts initiate coverage and subsequently downgrade our stock, issue unfavorable commentary, or reduce price targets, the market price of our Class A common stock could decline. If our operating results, key metrics, or qualitative disclosures fall short of analysts’ expectations, or if we do not provide guidance or our guidance is withdrawn, reduced, or perceived as uncertain, our stock price and trading volume could be adversely affected. If analysts cease coverage of us, fail to publish reports on us regularly, or do not initiate coverage after our offering, we could lose visibility in the financial markets, which may reduce demand for our shares, widen bid ask spreads, discourage institutional participation, and increase price volatility. Limited float, index inclusion or exclusion, and sector ETF flows can magnify the impact of analyst ratings and target changes on trading dynamics.
Analyst perceptions may be influenced by a broad range of inputs, including execution against growth plans, policy, permitting, and transmission/interconnection developments affecting utility-scale project delivery, competitive intensity among EPC contractors, access to bonding and working capital, bid pipeline, backlog, margin profile, change order and claims outcomes, labor availability, and supply chain conditions, and the performance and disclosures of peer companies. Coverage models for utility-scale solar energy and battery storage and EPC contractors vary, and differences in assumptions around module and equipment pricing, input costs (including steel and electrical gear), labor rates and productivity, weather and schedule risk, interconnection timing, and permitting can produce disparate estimates and conflicting signals. Because our model involves rapidly evolving regulatory, permitting, transmission/interconnection, and supply chain dynamics, analyst views may shift quickly in response to external events beyond our control. Social media, news cycles, and market speculation can amplify the impact of a single research note or earnings report, resulting in outsized price reactions relative to underlying fundamentals. Quiet periods, Regulation FD constraints, and blackout windows may limit our ability to respond promptly to rumors or clarify misinterpretations, which can prolong negative sentiment. If our stock experiences volatility or declines in connection with analyst reports or market conditions, we may face increased risk of securities litigation, which could be costly and distracting regardless of merit. A sustained lack of favorable analyst coverage, or the publication of negative or inconsistent research, could materially affect investor sentiment, reduce trading liquidity, increase our cost of capital, and adversely impact the market price of our Class A common stock.
As an “emerging growth company,” we will rely on reduced disclosure and governance requirements, which may make our stock less attractive to some investors.
We expect to qualify as an “emerging growth company” (“EGC”) and to rely on certain exemptions from reporting and governance requirements that apply to other public companies. These accommodations include, among other things, not being required to have our independent registered public accounting firm attest to the effectiveness of our internal control over financial reporting under Section 404(b) of the Sarbanes-Oxley Act, reduced disclosure obligations regarding executive compensation in proxy statements and annual reports on Form 10-K, and exemptions from holding certain nonbinding advisory votes on executive compensation matters. While these accommodations can reduce compliance costs and allow us to focus resources on growth, some investors may view the reduced transparency and governance requirements unfavorably and demand a
69
Table of Contents
higher risk premium, which could adversely affect the market price and liquidity of our Class A common stock. In addition, our eligibility to rely on EGC accommodations will cease upon the earliest of specific statutory triggers, including exceeding certain revenue or public float thresholds, or the passage of time, at which point we will incur increased costs and management efforts toward ensuring compliance with additional requirements.
Even with EGC accommodations, we must implement and maintain internal control over financial reporting and disclosure controls appropriate for a public company operating across multiple states and project sites under large, fixed-price construction contracts. If we identify material weaknesses, fail to remediate control deficiencies in a timely manner, or otherwise fail to maintain effective controls, we could experience inaccuracies in our financial reporting, delayed or amended filings, regulatory scrutiny, litigation, and reputational harm. Transitioning out of EGC status will further increase compliance costs, including higher audit expenses and augmented governance requirements, and may require additional personnel, systems, and processes. Investors may perceive heightened risk during transition periods, particularly if disclosure, control, or governance enhancements are not executed smoothly. If our reliance on EGC accommodations results in reduced investor interest, or if the loss of EGC status increases our cost structure more than anticipated, our stock could be less attractive to certain investors, trading liquidity could suffer, and our market valuation could be adversely affected.
The requirements of being a public company may strain our resources, divert management’s attention, and affect our ability to attract and retain qualified board members and executive officers.
As a public company, we are subject to extensive regulatory and compliance obligations, including the Sarbanes-Oxley Act, the Dodd-Frank Wall Street Reform and Consumer Protection Act, and rules of the SEC and our listing exchange. Compliance requires significant legal, accounting, IT, and administrative investment, as well as the design, implementation, and ongoing testing of internal control over financial reporting and disclosure controls. Section 404 compliance, including management assessments and, if applicable, auditor attestation, is complex and time-consuming, often necessitating ERP upgrades, Governance, Risk Compliance tooling, internal audit build-out, remediation plans, and third-party advisors, and robust contract accounting processes (e.g., percentage-of-completion revenue recognition, change order and claims management). Failures in controls or disclosure processes can lead to material weaknesses, restatements, missed filing deadlines, SEC comment letters, potential penalties, and loss of investor confidence. We must also comply with evolving reporting standards, including enhanced cybersecurity disclosures, executive compensation clawback rules, universal proxy requirements, and changes to insider trading and 10b5-1 practices, all of which increase governance burdens and risk of error. Exchange listing standards regarding board independence, committee charters, audit committee expertise, related party transaction oversight, and code of ethics enforcement further add complexity and resource demands.
Public company status increases scrutiny from investors, regulators, auditors, proxy advisors, and the media, and may complicate recruiting and retention for directors and senior executives. The demands of governance, potential personal liability, and heightened time commitments can deter candidates, while D&O insurance premiums, retentions, and coverage limitations have risen and may continue to rise. We must maintain robust policies for Regulation FD, insider trading, Section 16 reporting, whistleblower hotlines, litigation holds, and records retention, and any lapses can trigger investigations, litigation, or reputational harm. Volatility in our stock price, limited float, and sector sentiment can increase the likelihood of securities class actions or derivative claims following earnings releases, guidance changes, or adverse events, regardless of merit. While we are committed to meeting our public company obligations and maintaining transparency, these ongoing requirements and costs can affect operational efficiency, divert management attention from strategic initiatives, and increase our cost of capital. Any inability to effectively manage these obligations, remediate identified control issues, or keep pace with evolving rules could have a material adverse effect on our business, results of operations, financial condition, and market reputation.
70
Table of Contents
If we experience any material weaknesses in the future or otherwise fail to develop or maintain an effective system of internal controls in the future, we may not be able to accurately report our financial condition or results of operations, which may adversely affect investor confidence in us and, as a result, the value of our Class A common stock.
Effective internal controls are necessary for us to provide reliable financial reports, prevent fraud and operate successfully as a public company. If we cannot provide reliable financial reports or prevent fraud, our reputation and operating results would be harmed. As a result of being a public company, we will be required, under Section 404 of the Sarbanes-Oxley Act, to furnish a report by management on, among other things, the effectiveness of our internal control over financial reporting beginning in the year following our first annual report required to be filed with the SEC. This assessment will need to include disclosure of any material weaknesses identified by our management in our internal control over financial reporting. We will take steps to improve control processes as appropriate, validate through testing that controls are functioning as documented, and implement a continuous reporting and improvement process for our internal control over financial reporting. If we identify one or more material weaknesses in our internal control over financial reporting during the evaluation and testing process, we may be unable to conclude that our internal controls are effective.
Additionally, when we cease to be an “emerging growth company” under the federal securities laws, our independent registered public accounting firm may be required to express an opinion on the effectiveness of our internal controls. If we are unable to confirm that our internal control over financial reporting is effective, or if our independent registered public accounting firm is unable to express an unqualified opinion on the effectiveness of our internal controls, we could lose investor confidence in the accuracy and completeness of our financial reports, which could cause the price of our Class A common stock to decline.
71
Table of Contents
CAUTIONARY NOTE REGARDING FORWARD-LOOKING STATEMENTS
This prospectus contains forward-looking statements about us and our industry that involve substantial risks and uncertainties. All statements other than statements of historical facts contained in this prospectus, including statements regarding our future results of operations or financial condition, business strategy, and plans and objectives of management for future operations may be forward-looking statements. In some cases, you can identify forward-looking statements by terms such as “may,” “will,” “should,” “expects,” “plans,” “anticipates,” “could,” “intends,” “targets,” “projects,” “contemplates,” “believes,” “estimates,” “predicts,” “potential” or “continue” or the negative of these terms or other similar expressions. Forward-looking statements contained in this prospectus include, but are not limited to statements about:
| • | our expectations regarding the demand for utility-scale solar and battery storage projects and our ability to win new EPC contracts; |
| • | the impact of macroeconomic conditions, including inflation, rising interest rates, and tighter credit markets, on our business and our customers’ projects; |
| • | our ability to complete projects on time, within budget, and in accordance with performance standards; |
| • | our ability to accurately estimate project costs under lump sum contracts and realize anticipated profit margins; |
| • | the availability, cost, and timely delivery of solar modules, inverters, racking systems, transformers, battery storage equipment, and other critical materials and equipment; |
| • | the impact of tariffs, duties, trade barriers, and supply chain disruptions on our costs and project schedules; |
| • | our ability to attract, train, and retain qualified electricians, project managers, engineers, and other skilled construction personnel; |
| • | risks related to our collective bargaining agreements and multiemployer pension plan obligations; |
| • | our dependence on a limited number of significant customers for a substantial portion of our revenues; |
| • | the risk that our contracts may be canceled, suspended, or not renewed on short notice; |
| • | our ability to recover on contract modifications, change orders, and claims against customers; |
| • | our exposure to warranty, engineering, design defect, construction quality, and performance guarantee claims; |
| • | health and safety risks inherent in our construction operations, including the risk of worksite injuries and fatalities; |
| • | the adequacy of our cybersecurity measures to protect our information technology systems and data; |
| • | physical risks to our construction schedules and project economics from severe weather events, natural disasters, and climate change; |
| • | our ability to realize our backlog and convert it to revenue at anticipated rates and profit margins; |
| • | our ability to obtain surety bonds, letters of credit, and bank guarantees required for our projects; |
| • | the impact of seasonality, project timing, and other factors on our quarterly results of operations; |
| • | our dependence on key personnel, including our senior management team and skilled project managers; |
72
Table of Contents
| • | the adequacy of our insurance coverage to cover losses and liabilities we may incur; |
| • | changes in environmental, health, safety, and permitting regulations affecting our business; |
| • | our ability to comply with complex federal, state, and local environmental, health, and safety laws and regulations; |
| • | the impact of changes in tax laws or our tax estimates or positions on our business; |
| • | our ability to comply with anti-corruption, anti-bribery, export control, and economic sanctions laws; |
| • | our exposure to litigation, claims, and legal proceedings in the ordinary course of our business; |
| • | our ability to comply with NERC reliability standards and other grid-related regulations; |
| • | the volatility of the market price of our Class A common stock; |
| • | our ability to develop and maintain an active and liquid trading market for our Class A common stock; |
| • | the influence of our principal shareholders on corporate matters; |
| • | the potential dilution from future stock issuances; |
| • | our intention not to pay dividends for the foreseeable future; |
| • | the impact of anti-takeover provisions in our corporate governance documents; |
| • | our status as an emerging growth company and reliance on reduced disclosure and governance requirements; |
| • | the costs of operating as a public company and our management team’s ability to meet public company obligations; |
| • | the potential for substantial future sales of our Class A common stock to depress our stock price; |
| • | our limited operating history as a public company and the difficulty in evaluating our business and future prospects; and |
| • | other risks and uncertainties described in this prospectus, including those set forth under “Risk Factors.” |
We caution you that the foregoing list may not contain all of the forward-looking statements made in this prospectus. The forward-looking statements in this prospectus are only predictions. We have based these forward-looking statements largely on our current expectations and projections about future events and financial trends that we believe may affect our business, financial condition and results of operations. Forward-looking statements involve known and unknown risks, uncertainties and other important factors that may cause our actual results, performance or achievements to be materially different from any future results, performance or achievements expressed or implied by the forward-looking statements. We believe that these factors include, but are not limited to the factors set forth under “Risk Factors.” Because forward-looking statements are inherently subject to risks and uncertainties, some of which cannot be predicted or quantified, you should not rely on these forward-looking statements as predictions of future events. Moreover, we operate in a very competitive and rapidly changing environment. New risks and uncertainties emerge from time to time, and it is not possible for us to predict all risks and uncertainties that could have an impact on the forward-looking statements contained in this prospectus. The events and circumstances reflected in our forward-looking statements may not be achieved or occur and actual results could differ materially from those projected in the forward-looking statements.
73
Table of Contents
In addition, statements that “we believe” and similar statements reflect our beliefs and opinions on the relevant subject. These statements are based upon information available to us as of the date of this prospectus, and while we believe such information forms a reasonable basis for such statements, such information may be limited or incomplete, and our statements should not be read to indicate that we have conducted an exhaustive inquiry into, or review of, all potentially available relevant information. These statements are inherently uncertain and investors are cautioned not to unduly rely upon these statements.
The forward-looking statements made in this prospectus relate only to events as of the date on which the statements are made. We undertake no obligation to update any forward-looking statements made in this prospectus to reflect events or circumstances after the date of this prospectus or to reflect new information or the occurrence of unanticipated events, except as required by law. We may not actually achieve the plans, intentions or expectations disclosed in our forward-looking statements, and you should not place undue reliance on our forward-looking statements. Our forward-looking statements do not reflect the potential impact of any future acquisitions, mergers, dispositions, joint ventures or investments we may make.
You should read this prospectus and the documents that we reference in this prospectus and have filed as exhibits to the registration statement of which this prospectus forms a part with the understanding that our actual future results, levels of activity, performance and achievements may be materially different from what we expect. We qualify all of our forward-looking statements by these cautionary statements.
74
Table of Contents
We estimate that we will receive net proceeds from this offering of approximately $ million, based upon an assumed initial public offering price of $ per share (which is the midpoint of the price range set forth on the cover page of this prospectus) and after deducting estimated underwriting discounts and commissions and estimated offering expenses payable by us.
We will not receive any proceeds from the sale of shares of our Class A common stock by the selling shareholders.
The principal purposes of this offering are to create a public market for our Class A common stock and enable access to the public equity markets for our shareholders. We intend to use the net proceeds from this offering to purchase Common Units from certain of the Continuing Equity Owners and to contribute the remaining net proceeds to CoVolt Holdings in exchange for newly issued Common Units. CoVolt Holdings intends to use the net proceeds from this offering for general corporate purposes, including working capital, operating expenses and capital expenditures. We will have broad discretion in the way that we use the net proceeds of this offering. See “Risk Factors–Risks Related to Owning Our Class A Common Stock–We will have broad discretion over the use of the net proceeds from this offering and may not use them in ways that prove to be effective.” for additional information.
Each $1.00 increase (decrease) in the assumed initial public offering price of $ per share (which is the midpoint of the price range set forth on the cover page of this prospectus) would increase (decrease) the net proceeds to us from this offering by approximately $ million, assuming the number of shares offered, as set forth on the cover page of this prospectus, remains the same, and after deducting estimated underwriting discounts and commissions and estimated offering expenses payable by us.
Each 1,000,000 share increase (decrease) in the number of shares offered in this offering would increase (decrease) the net proceeds to us from this offering by approximately $ million, assuming that the price per share for the offering remains at $ (which is the midpoint of the price range set forth on the cover page of this prospectus), and after deducting the estimated underwriting discounts and commissions and estimated offering expenses payable by us.
75
Table of Contents
We have never declared or paid any cash dividends on our capital stock. We currently intend to retain all available funds and any future earnings, if any, for the operation and expansion of our business. Accordingly, following this offering, we do not expect to declare or pay any cash dividends in the foreseeable future. Any future determination to declare cash dividends will be made at the discretion of our board of directors, subject to applicable laws, and will depend on a number of factors, including our financial condition, results of operations, capital requirements, contractual restrictions, general business conditions, and other factors that our board of directors may deem relevant.
Additionally, we are a holding company that transacts our business through operating subsidiaries. Consequently, our ability to pay dividends to shareholders is largely dependent on receipt of dividends and other distributions from our subsidiaries.
If CoVolt Holdings makes such distributions, the holders of Common Units will be entitled to receive equivalent distributions from CoVolt Holdings. However, because we must pay taxes, make payments under the Tax Receivable Agreement and pay our expenses, amounts ultimately distributed as dividends to holders of our Class A common stock would be expected to be less on a per share basis than the amounts distributed by CoVolt Holdings to the other holders of Common Units on a per unit basis, even if we were to pay cash dividends on our Class A common stock. See “Certain Relationships and Related Party Transactions.”
Under the CoVolt Holdings LLC Agreement, we intend to cause CoVolt Holdings, from time to time, to make distributions in cash to the holders of Common Units (including us) in amounts sufficient to cover the taxes imposed on their allocable share of taxable income of CoVolt Holdings. These tax distributions may be in amounts that exceed our tax liabilities. Our board of directors will determine the appropriate uses for any excess cash so accumulated, which may include, among other uses, the payment of obligations under the Tax Receivable Agreement and the payment of other expenses. We will have no obligation to distribute such cash (or other available cash) to our shareholders. See “Risk Factors–Risks Related to Our Capital Structure–Our sole material principal asset after the completion of this offering will be our interest in CoVolt Holdings, and, as a result, we will depend on distributions from CoVolt Holdings to pay our taxes and expenses (including payments under the Tax Receivable Agreement) and pay dividends. CoVolt Holdings’ ability to make such distributions may be subject to various limitations and restrictions.”
In addition, our Revolving Credit Facility contains restrictions on our ability to pay cash dividends on our capital stock. Our ability to pay dividends may also be restricted by the terms of any future credit agreement or any future debt or preferred equity securities of us or our subsidiaries. See “Risk Factors–Risks Related to Owning Our Class A Common Stock–We do not intend to pay dividends on our Class A common stock for the foreseeable future.” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations–Liquidity and Capital Resources” for additional information.
76
Table of Contents
The following table sets forth the cash and cash equivalents and our capitalization as of June 30, 2026:
| • | of CoVolt Holdings, on an actual basis; |
| • | of CoVolt Power and its subsidiaries on a pro forma basis to give effect to the Reorganization Transactions and the entry into the Tax Receivable Agreement as if such events had occurred on June 30, 2026, excluding this offering; and |
| • | of CoVolt Power and its subsidiaries on a pro forma as adjusted basis to give further effect to the matters described in the preceding clause and to reflect the issuance and sale by us of shares of our Class A common stock in this offering at an assumed initial public offering price of $ per share (which is the midpoint of the price range set forth on the cover page of this prospectus), after deducting the estimated underwriting discounts and commissions and estimated offering expenses payable by us, and the application of the net proceeds therefrom as described under “Use of Proceeds.” |
Our capitalization following the closing of this offering will be adjusted based on the actual initial public offering price and other terms of this offering determined at pricing. You should read this information in conjunction with our consolidated financial statements and the related notes included elsewhere in this prospectus and the “Management’s Discussion and Analysis of Financial Condition and Results of Operations” section and other financial information contained in this prospectus.
The pro forma and pro forma as adjusted information below gives effect to (i) the Reorganization Transactions, including CoVolt Power’s acquisition of Common Units from CoVolt Holdings in exchange for shares of Class A common stock and cash from the net proceeds of this offering, (ii) this offering and the application of the estimated net proceeds of this offering as described under “Use of Proceeds,” (iii) the impacts associated with the Tax Receivable Agreement, including the estimated liability related to future payments thereunder, and (iv) the non-controlling interest in CoVolt Holdings held by the Continuing Pre-IPO Members. See “Organizational Structure” and “Certain Relationships and Related Party Transactions–Tax Receivable Agreement.”
| As of June 30, 2026 | ||||||||||||
| CoVolt Holdings Actual |
CoVolt Power Pro forma |
CoVolt Power Pro forma as adjusted(1) |
||||||||||
| (in thousands, except share and per share data) | ||||||||||||
| Payable to related parties pursuant to the Tax Receivable Agreement |
||||||||||||
| Cash and cash equivalents |
$ | $ | $ | |||||||||
| Indebtedness: |
||||||||||||
| Total equity: |
||||||||||||
| Shareholders’ equity: |
||||||||||||
| Class A common stock, par value $ per share; shares authorized, actual; shares issued and outstanding, actual; shares authorized, pro forma; shares issued and outstanding, pro forma; shares authorized, pro forma as adjusted; shares issued and outstanding, pro forma as adjusted |
||||||||||||
77
Table of Contents
| As of June 30, 2026 | ||||||||||||
| CoVolt Holdings Actual |
CoVolt Power Pro forma |
CoVolt Power Pro forma as adjusted(1) |
||||||||||
| (in thousands, except share and per share data) | ||||||||||||
| Class B common stock, par value $ per share; shares authorized, actual; no shares issued and outstanding, actual; shares authorized, pro forma; shares issued and outstanding, pro forma; shares authorized, pro forma as adjusted; shares issued and outstanding, pro forma as adjusted (Class B common stock has no economic rights) |
||||||||||||
| Total shareholders’ equity attributable to CoVolt Power |
||||||||||||
| Preferred stock, par value $ per share; shares authorized, shares issued and outstanding, actual; shares authorized pro forma, no shares issued and outstanding, pro forma; shares authorized, no shares issued and outstanding, pro forma as adjusted |
||||||||||||
| Additional paid-in capital |
||||||||||||
| Accumulated other comprehensive loss |
||||||||||||
| Accumulated deficit |
||||||||||||
| Non-controlling interest in CoVolt Holdings |
||||||||||||
| Total members’/shareholders’ equity (including non-controlling interest) |
||||||||||||
| Total capitalization |
$ | $ | $ | |||||||||
| (1) | Each $1.00 increase or decrease in the assumed initial public offering price of $ per share (which is the midpoint of the price range set forth on the cover page of this prospectus) would increase or decrease each of cash and cash equivalents, additional paid-in capital, total shareholders’ equity and total capitalization on a pro forma as adjusted basis by approximately $ million, assuming the number of shares offered, as set forth on the cover page of this prospectus, remains the same, and after deducting the estimated underwriting discounts and commissions and estimated offering expenses payable by us. An increase or decrease of $1.00 in the assumed initial public offering price would also increase or decrease the amount of the estimated liability payable under the Tax Receivable Agreement by approximately $ million. |
| Each 1,000,000 share increase or decrease in the number of shares offered in this offering would increase or decrease each of cash and cash equivalents, additional paid-in capital, total shareholders’ equity and total capitalization on a pro forma as adjusted basis by approximately $ million, assuming that the price per share for the offering remains at $ (which is the midpoint of the price range set forth on the cover page of this prospectus), and after deducting the estimated underwriting discounts and commissions and estimated offering expenses payable by us. An increase or decrease of 1,000,000 shares in the number of shares offered would also increase or decrease the amount of the estimated liability payable under the Tax Receivable Agreement by approximately $ million. |
78
Table of Contents
If you invest in our Class A common stock in this offering, your ownership interest will be immediately diluted to the extent of the difference between the initial public offering price per share of our Class A common stock and the pro forma as adjusted net tangible book value per share of our Class A common stock immediately after this offering. Dilution in pro forma as adjusted net tangible book value per share to new investors represents the difference between the amount per share paid by purchasers of shares of our Class A common stock in this offering and the pro forma as adjusted net tangible book value per share of our Class A common stock immediately after completion of this offering.
The Continuing Equity Owners will hold Common Units after the completion of the Reorganization Transactions. A holder of Common Units (other than CoVolt Power, Inc. and its subsidiaries) may, subject to the terms of the CoVolt Holdings LLC Agreement, exchange its Common Units (together with an equal number of shares of Class B common stock, which will be cancelled for no consideration upon any such exchange) for shares of Class A common stock on a one-for-one basis or, at our election, for cash. We have presented dilution in pro forma as adjusted net tangible book value per share assuming that all of the holders of Common Units (other than CoVolt Power, Inc. and its subsidiaries) had their Common Units exchanged for newly issued shares of Class A common stock on a one-for-one basis (and the cancellation for no consideration of all of their shares of Class B common stock, which are not entitled to receive distributions or dividends, whether cash or stock, from the Company) in order to more meaningfully present the dilutive impact on the investors in this offering.
Our pro forma net tangible book value per share is determined by dividing our total tangible assets less our total liabilities by the number of shares of our Class A common stock outstanding, assuming the exchange of all outstanding Common Units for shares of our Class A common stock on a one-for-one basis before this offering. Our pro forma net tangible book value as of June 30, 2026 was approximately $ million, or $ per share, based on the total number of shares of our Class A common stock that would be outstanding as of , 2026, assuming the exchange of all outstanding Common Units held by the Continuing Equity Owners for shares of our Class A common stock on a one-for-one basis before this offering.
After giving effect to the sale by us of shares of our Class A common stock in this offering at the assumed initial public offering price of $ per share, which is the midpoint of the estimated offering price range set forth on the cover page of this prospectus, and after deducting estimated underwriting discounts and commissions and estimated offering expenses payable by us and assuming the exchange of all outstanding Common Units held by the Continuing Equity Owners for shares of our Class A common stock on a one-for-one basis after this offering, our pro forma as adjusted net tangible book value as of June 30, 2026, would have been approximately $ million, or $ per share. This represents an immediate increase in pro forma as adjusted net tangible book value of $ per share to our existing shareholders and an immediate dilution in pro forma as adjusted net tangible book value of $ per share to investors purchasing shares of our Class A common stock in this offering. The following table illustrates this dilution:
| Assumed initial public offering price per share of Class A common stock |
$ | |||||||
| Pro forma net tangible book value per share as of , 2026 |
||||||||
| Increase per share attributable to new investors purchasing shares of Class A common stock in this offering |
||||||||
| Pro forma as adjusted net tangible book value per share immediately after this offering |
$ | |||||||
| Dilution in pro forma as adjusted net tangible book value per share to new Class A common stock investors in this offering |
$ | |||||||
Each $1.00 increase (decrease) in the assumed initial public offering price of $ per share, which is the midpoint of the price range set forth on the cover page of this prospectus, would increase (decrease) our
79
Table of Contents
pro forma as adjusted net tangible book value after this offering by approximately $ million, or approximately $ per share, and would increase (decrease) the dilution per share to new investors purchasing our Class A common stock in this offering by approximately $ per share, assuming that the number of shares offered by us, as set forth on the cover page of this prospectus, remains the same, and after deducting estimated underwriting discounts and commissions and estimated offering expenses payable by us. Each increase (decrease) of 1,000,000 shares in the number of shares sold in this offering, as set forth on the cover page of this prospectus, would increase (decrease) our pro forma as adjusted net tangible book value after this offering by approximately $ million, or approximately $ per share, and would increase (decrease) the dilution per share to new investors by approximately $ per share, assuming that the assumed initial public offering price of $ per share, which is the midpoint of the price range set forth on the cover page of this prospectus, remains the same, and after deducting estimated underwriting discounts and commissions and estimated offering expenses payable by us.
The following table presents, on a pro forma basis as of June 30, 2026, after giving effect to the sale by us of shares of our Class A common stock in this offering at the assumed initial public offering price of $ per share, which is the midpoint of the estimated offering price range set forth on the cover page of this prospectus, the difference between the existing shareholders and the investors purchasing shares of our Class A common stock in this offering with respect to the number of shares of our Class A common stock purchased from us, the total consideration paid or to be paid to us, and the average price per share paid or to be paid to us, before deducting estimated underwriting discounts and commissions and estimated offering expenses payable by us:
| Shares Purchased | Total Consideration | |||||||||||||||||||
| Number | Percent | Amount | Percent | |||||||||||||||||
| Existing shareholders |
% | $ | % | $ | ||||||||||||||||
| New investors |
||||||||||||||||||||
| Total |
100% | $ | 100% | $ | ||||||||||||||||
Each $1.00 increase (decrease) in the assumed initial public offering price of $ per share, which is the midpoint of the price range set forth on the cover page of this prospectus, would increase (decrease) the total consideration paid by new investors, total consideration paid by all shareholders and the average price per share paid by all shareholders by $ , $ and $ per share, respectively, assuming that the number of shares offered by us, as set forth on the cover page of this prospectus, remains the same, and after deducting estimated underwriting discounts and commissions and estimated offering expenses payable by us. Each increase (decrease) of 1,000,000 shares in the number of shares sold in this offering, as set forth on the cover page of this prospectus, would increase (decrease) the total consideration paid by new investors, total consideration paid by all shareholders and the average price per share paid by all shareholders by $ , $ and $ per share, respectively, assuming that the assumed initial public offering price of $ per share, which is the midpoint of the price range set forth on the cover page of this prospectus, remains the same, and after deducting estimated underwriting discounts and commissions and estimated offering expenses payable by us.
Except as otherwise indicated, the above discussion and tables assume no exercise of the underwriters’ option to purchase additional shares of Class A common stock from the selling shareholders. Sales of shares of our Class A common stock by the selling shareholders in this offering will reduce the number of shares of Class A common stock held by existing shareholders to , or approximately % of the total shares of Class A common stock outstanding after this offering, and will increase the number of shares held by new investors to , or approximately % of the total shares of Class A common stock outstanding after this offering.
The number of shares of our Class A common stock that will be outstanding after this offering as shown in the tables above is based on shares of our Class A common stock outstanding as of June 30, 2026
80
Table of Contents
(assuming the exchange of all outstanding Common Units held by the Continuing Equity Owners for shares of our Class A common stock on a one-for-one basis), and excludes the following:
| • | shares of our Class A common stock reserved for issuance upon redemption or exchange of all outstanding Common Units on a one-for-one basis; |
| • | shares of common stock issuable upon the exercise of warrants outstanding as of June 30, 2026, with a weighted average exercise price of $ per share; and |
| • | shares of our Class A common stock reserved for future issuance under the 2026 Plan, which will become effective in connection with this offering, which number includes shares of our Class A common stock subject to restricted stock unit awards that will be granted to certain of our employees pursuant to our 2026 Plan substantially concurrently with the consummation of this offering. |
In addition, our 2026 Plan provides for annual automatic increases in the number of shares reserved thereunder.
The dilution information discussed above is illustrative only and may change based on the actual initial public offering price and other terms of this offering determined at pricing.
In addition, we may choose to raise additional capital due to market conditions or strategic considerations, even if we believe we have sufficient funds for our current or future operating plans. To the extent that we raise additional capital through the sale of equity or convertible debt securities, the issuance of these securities could result in further dilution to our shareholders.
81
Table of Contents
UNAUDITED PRO FORMA CONDENSED CONSOLIDATED FINANCIAL INFORMATION
Defined terms included below will have the same meaning as terms defined and included elsewhere in this prospectus.
The unaudited pro forma condensed consolidated financial information has been prepared in accordance with Article 11 of Regulation S-X under the Securities Act, as amended. The unaudited pro forma condensed consolidated financial information is presented to provide relevant information necessary for an understanding of CoVolt Holdings upon consummation of the Company’s initial public offering after giving pro forma effect to the following (collectively, the “pro forma events”):
| • | the Reorganization Transactions; |
| • | the impacts associated with the Tax Receivable Agreement, as described under “Certain Relationships and Related Party Transactions–Tax Receivable Agreement;” and |
| • | this offering and the application of the estimated net proceeds from this offering as described under “Use of Proceeds.” |
The unaudited pro forma condensed consolidated balance sheet as of June 30, 2026 gives effect to the pro forma events as if they had been consummated on June 30, 2026.
The unaudited pro forma condensed consolidated statements of operations for the six months ended June 30, 2026 and for the year ended December 31, 2025 give effect to the pro forma events as if they had been consummated on January 1, 2025.
We have derived the unaudited pro forma condensed consolidated balance sheet and the unaudited pro forma condensed consolidated statements of operations from our unaudited condensed consolidated financial statements as of and for the six months ended June 30, 2026 and from our audited consolidated financial statements for the year ended December 31, 2025, which are included elsewhere in this prospectus. The foregoing historical financial statements have been prepared in accordance with GAAP.
Because CoVolt Power was formed on April 22, 2026 and will have no material assets or results of operations until the completion of the offering, its historical financial information is not included in the unaudited pro forma condensed consolidated financial information as of and for the six months ended June 30, 2026 and for the year ended December 31, 2025.
Except as otherwise indicated, the unaudited pro forma condensed consolidated financial information presented assumes no exercise by the underwriters of their over-allotment option to purchase additional shares.
As a public company, we will be implementing additional procedures and processes for the purpose of addressing the standards and requirements applicable to public companies. We expect to incur additional annual expenses related to these additional procedures and processes and, among other things, additional directors’ and officers’ liability insurance, director fees, additional expenses associated with complying with the reporting requirements of the SEC, transfer agent fees, costs relating to additional accounting, legal, and administrative personnel, increased auditing, tax, and legal fees, stock exchange listing fees, and other public company expenses. We have not included any pro forma adjustments relating to these costs in the information below.
The pro forma adjustments are based on available information and upon assumptions that management believes are reasonable in order to reflect, on a pro forma basis, the effect of the pro forma events on our
82
Table of Contents
historical financial information. The adjustments are described in the notes to the unaudited pro forma condensed consolidated balance sheet and the unaudited pro forma condensed consolidated statement of operations. The unaudited pro forma condensed consolidated financial information is presented for illustrative purposes only and do not purport to represent the results of operations or the financial position that would have occurred had the pro forma events been consummated on the dates assumed or to project the Company’s results of operations or financial position for any future date or period.
The unaudited pro forma condensed consolidated financial information should also be read together with “Basis of Presentation–Organizational Structure,” “Capitalization,” “Management’s Discussion and Analysis of Financial Condition and Results of Operations” and our financial statements and accompanying notes included elsewhere in this prospectus.
Offering
The Company is offering million shares of common stock in this offering at an assumed initial public offering price of $ per share, which is the midpoint of the estimated offering price range set forth on the cover page of this prospectus.
Reorganization Transactions
In connection with the consummation of this offering, we will complete a series of reorganization transactions (the “Reorganization Transactions”), including:
| • | the amendment and restatement of the CoVolt Holdings limited liability company agreement (the “CoVolt OpCo LLC Agreement”), effective prior to the consummation of this offering, to, among other things, (i) recapitalize all existing ownership interests in CoVolt Holdings into a single new class of units (“Common Units”), (ii) appoint CoVolt Power, Inc. as the sole managing member of CoVolt Holdings upon its acquisition of Common Units in connection with this offering and (iii) provide certain redemption rights to the Continuing Equity Owners; |
| • | the merger of SEC Intermediate, LLC with and into SEC Parent II, LLC, with SEC Parent II, LLC surviving such merger, followed by the liquidation of SEC Parent II, LLC; |
| • | the amendment and restatement of the LLC agreement of SEC Member II, LLC (a Continuing Equity Owner) to, among other things, effect a recapitalization in which all existing membership interests of SEC Member II, LLC are converted into one class of common units and provide certain redemption rights to the members of SEC Member II, LLC; |
| • | the amendment and restatement of CoVolt Power, Inc.’s certificate of formation to, among other things, authorize the issuance of Class A common stock and Class B common stock and provide that each share of Class A common stock and Class B common stock will entitle its holder to one vote per share on all matters presented to our shareholders generally, provided that shares of Class B common stock will not be entitled to receive dividends or to receive a distribution upon CoVolt Power, Inc.’s dissolution or liquidation; |
| • | the issuance of shares of our Class B common stock to the Continuing Equity Owners (as defined herein), which will be equal to the number of Common Units held by such Continuing Equity Owners, for nominal consideration; |
| • | the contribution by an affiliate of Avenue Capital Group of its Common Units to CoVolt Power, Inc. in exchange for shares of Class A common stock; |
83
Table of Contents
| • | the entrance into the Tax Receivable Agreement with CoVolt Holdings and the TRA Holders (as defined herein) that will provide for the payment by CoVolt Power, Inc. to the TRA Holders of % of the amount of tax benefits, if any, that CoVolt Power, Inc. actually realizes, or in some circumstances is deemed to realize, as a result of Basis Adjustments Blocker Transferred Basis and Interest Deductions. See “Certain Relationships and Related Party Transactions–Tax Receivable Agreement” for a description of the Tax Receivable Agreement; |
| • | the issuance of shares of our Class A common stock to the purchasers in this offering in exchange for net proceeds of approximately $ million (or approximately $ million if the underwriters exercise in full their option to purchase additional shares of Class A common stock) based upon an assumed initial public offering price of $ per share (which is the midpoint of the estimated price range set forth on the cover page of this prospectus), less the estimated underwriting discounts and commissions and estimated offering expenses payable by us; |
| • | the use of the net proceeds from this offering to purchase newly issued Common Units for approximately $ million directly from CoVolt Holdings at the initial public offering price less the underwriting discounts and commissions, and to purchase Common Units from certain of the Continuing Equity Owners for cash; and |
| • | the use by CoVolt Holdings of the proceeds from the sale of its Common Units to CoVolt Power, Inc. for general corporate purposes, as described under “Use of Proceeds.” |
Pre-IPO Investor Restructurings
Prior to the Blocker Mergers, certain of our existing investors will complete separate restructuring transactions. DK Swan Equity Holder LLC will distribute its interests in CoVolt Holdings to the DK Blocker in full redemption of its equity interests in DK Swan Equity Holder LLC. Avenue MIC Power Opportunities Master Fund, LP will distribute equity interests in CoVolt Holdings to the Ave Blocker in full redemption of its equity interests in Avenue MIC Power Opportunities Master Fund, LP, and will also distribute interests in CoVolt Holdings to Avenue MIC Power Opportunities Fund Genpar, LLC.
On the day prior to the closing of this offering, DK Blocker, the Bardin Blocker and Ave Blocker will each merge with and into CoVolt Power, Inc., with CoVolt Power, Inc. surviving each merger, and the respective Blocker Shareholders will receive shares of our Class A common stock as merger consideration. Immediately following the closing of this offering, Avenue MIC Power Opportunities Fund Genpar, LLC and the Ave Blocker will contribute their shares of Class A common stock received in the Blocker Mergers to Avenue MIC Power Opportunities Master Fund, LP in exchange for equity interests in that fund.
Our agreements will include a provision for the Continuing Equity Owners, subject to certain exceptions, from time to time at each of their option, to require CoVolt Holdings to redeem all or a portion of their Common Units (along with the cancellation of the corresponding shares of Class B common stock) in exchange for, at our election, newly-issued shares of our Class A common stock on a one-for-one basis or a cash payment equal to a volume weighted average market price of one share of our Class A common stock for each Common Unit so redeemed, in each case, in accordance with the terms of the CoVolt OpCo LLC Agreement.
Tax Receivable Agreement
In connection with the completion of this offering, we will enter into the Tax Receivable Agreement with CoVolt Holdings and the TRA Holders. Under the Tax Receivable Agreement, we generally will be required to pay to the TRA Holders % of the amount of tax benefits, if any, we actually realize (or in some circumstances are deemed to realize) as a result of Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions. We will retain the benefit of the remaining % of these tax benefits.
84
Table of Contents
The Tax Receivable Agreement payments are not conditioned upon a TRA Party maintaining a continued ownership interest in CoVolt Holdings. The Tax Receivable Agreement will provide that if (i) CoVolt Power, Inc. materially breaches any of its material obligations under the Tax Receivable Agreement, (ii) certain mergers, asset sales, other forms of business combinations or other changes of control occur, or (iii) CoVolt Power, Inc. elects an early termination of the Tax Receivable Agreement, then the obligations under the Tax Receivable Agreement to make payments will be accelerated and become due and payable, based on certain assumptions, including an assumption that CoVolt Power, Inc. will have sufficient taxable income to fully utilize all potential future tax benefits that are subject to the Tax Receivable Agreement. See “Certain Relationships and Related Party Transactions–Tax Receivable Agreement” for additional information regarding the Tax Receivable Agreement.
85
Table of Contents
Unaudited Pro Forma Condensed Consolidated Balance Sheet As of June 30, 2026
(in thousands)
| (in $ thousands) | CoVolt Holdings | Reorganization Transaction Adjustments |
Transaction Accounting Adjustments |
Pro Forma CoVolt Power, Inc. |
||||||||||||
| Assets |
||||||||||||||||
| Current assets |
||||||||||||||||
| Cash and cash equivalents |
$ | 119,218 | ||||||||||||||
| Restricted cash |
4,736 | |||||||||||||||
| Accounts receivable, net |
50,245 | |||||||||||||||
| Contract assets |
5,636 | |||||||||||||||
| Other current assets |
26,728 | |||||||||||||||
| Total current assets |
206,563 | |||||||||||||||
| Property and equipment, net |
3,602 | |||||||||||||||
| Finance lease right-of-use assets, net |
4,302 | |||||||||||||||
| Operating lease right-of-use assets |
3,192 | |||||||||||||||
| Goodwill |
62,852 | |||||||||||||||
| Other intangible assets, net |
2,811 | |||||||||||||||
| Other non-current assets |
425 | |||||||||||||||
| Total assets |
$ | 283,747 | ||||||||||||||
| Liabilities and members’ equity / shareholders’ equity |
||||||||||||||||
| Current liabilities |
||||||||||||||||
| Accounts payable |
$ | 73,626 | ||||||||||||||
| Contract liabilities |
77,417 | |||||||||||||||
| Accrued expenses and other |
19,076 | |||||||||||||||
| Finance lease liabilities, current portion |
1,546 | |||||||||||||||
| Operating lease liabilities, current portion |
247 | |||||||||||||||
| Total current liabilities |
171,912 | |||||||||||||||
| Finance lease liabilities, net of current portion |
715 | |||||||||||||||
| Operating lease liabilities, net of current portion |
3,281 | |||||||||||||||
| Other non-current liabilities |
2,174 | |||||||||||||||
| Total liabilities |
178,082 | |||||||||||||||
| Commitments and contingencies |
||||||||||||||||
| Members’ equity / Shareholders’ equity |
||||||||||||||||
| Members’ equity / Shareholders’ equity |
107,709 | |||||||||||||||
| Accumulated other comprehensive loss |
(2,055 | ) | ||||||||||||||
| Total members’ equity |
105,654 | |||||||||||||||
| Non-controlling interests |
11 | |||||||||||||||
| Total members’ equity |
105,665 | |||||||||||||||
| Total liabilities and members’ equity |
$ | 283,747 | ||||||||||||||
Please refer to the notes to the unaudited pro forma condensed consolidated financial information.
86
Table of Contents
Unaudited Pro Forma Consolidated Statement of Operations For the Year Ended December 31, 2025
(in thousands, except share and per share amounts)
| (in $ thousands) | CoVolt Holdings |
Reorganization Transaction Adjustments |
Transaction Accounting Adjustments |
Pro Forma CoVolt Power, Inc. |
||||||||||||
| Revenue |
$ | 739,405 | ||||||||||||||
| Cost of revenue |
637,137 | |||||||||||||||
| Gross profit |
102,268 | |||||||||||||||
| General and administrative |
34,413 | |||||||||||||||
| Depreciation and amortization |
8,040 | |||||||||||||||
| Loss on disposal of assets |
69 | |||||||||||||||
| Operating income |
59,746 | |||||||||||||||
| Other income (expense) |
||||||||||||||||
| Interest income |
1,297 | |||||||||||||||
| Interest expense |
(654 | ) | ||||||||||||||
| Other Income, net |
192 | |||||||||||||||
| Total other income (expense) |
835 | |||||||||||||||
| Net income (loss) |
60,581 | |||||||||||||||
| Net income (loss) attributable to non-controlling interest |
— | |||||||||||||||
| Net income (loss) attributable to common shareholders |
$ | 60,581 | ||||||||||||||
| Weighted average shares outstanding—basic and diluted |
||||||||||||||||
| Earning per share—basic and diluted |
||||||||||||||||
Please refer to the notes to the unaudited pro forma condensed consolidated financial information.
87
Table of Contents
Unaudited Pro Forma Consolidated Statement of Operations For the Six Months Ended June 30, 2026
(in thousands, except share and per share amounts)
| (in $ thousands) | CoVolt Holdings |
Reorganization Transaction Adjustments |
Transaction Accounting Adjustments |
CoVolt Power, Inc. |
||||||||||||
| Revenue |
$ | 308,278 | ||||||||||||||
| Cost of revenue |
254,158 | |||||||||||||||
| Gross margin |
54,120 | |||||||||||||||
| General and administrative |
18,537 | |||||||||||||||
| Depreciation and amortization |
914 | |||||||||||||||
| Gain on disposal of assets |
(193 | ) | ||||||||||||||
| Operating income (loss) |
34,862 | |||||||||||||||
| Other income (expense) |
||||||||||||||||
| Interest income |
1,614 | |||||||||||||||
| Interest expense |
(279 | ) | ||||||||||||||
| Other income (expense), net |
(837 | ) | ||||||||||||||
| Total other income (expense) |
498 | |||||||||||||||
| Net income (loss) |
35,360 | |||||||||||||||
| Net income (loss) attributable to non-controlling interest |
— | |||||||||||||||
| Net income (loss) attributable to common shareholders |
$ | 35,360 | ||||||||||||||
| Weighted average shares outstanding—basic and diluted |
||||||||||||||||
| Earning per share—basic and diluted |
||||||||||||||||
Please refer to the notes to the unaudited pro forma condensed consolidated financial information.
88
Table of Contents
Notes to Unaudited Pro Forma Condensed Consolidated Financial Information
Note 1 Basis of Presentation
The unaudited pro forma condensed consolidated financial information has been prepared in accordance with Article 11 of Regulation S-X and presents the pro forma financial condition and results of operations of the Company based upon the historical financial information after giving effect to the pro forma events and related adjustments set forth in the notes to the unaudited pro forma condensed consolidated financial information.
The unaudited pro forma condensed consolidated financial information does not reflect any management adjustments for expected effects of the pro forma events.
The unaudited pro forma condensed consolidated balance sheet as of June 30, 2026, gives effect to the pro forma events as if they had occurred on June 30, 2026. The unaudited pro forma condensed consolidated statements of operations for the six months ended June 30, 2026 and for the year ended December 31, 2025, give effect to the pro forma events as if they had occurred on January 1, 2025.
Note 2 Adjustments to the Unaudited Pro Forma Condensed Consolidated Balance Sheet
The following adjustments were made related to the unaudited pro forma condensed consolidated balance sheet as of June 30, 2026:
| A. | Immediately preceding the closing, as part of the Reorganization Transactions, CoVolt Holdings legacy units were converted into Common Units. |
| B. | Reflects the net effect on cash of the receipt of offering proceeds to us of $ million, based on the sale by the Company of million shares of Class A common stock at an assumed initial public offering price of $per share of common stock (the midpoint of the price range set forth on the cover of this prospectus), after deducting the estimated underwriting discounts and commissions. |
| C. | Reflects estimated transaction costs of $ million, which are primarily related to legal, accounting, and other related costs. Upon completion of the offering, these transaction costs will be charged against the proceeds from the offering with a corresponding reduction to additional paid-in capital. |
| D. | Immediately following closing, the economic interests held by the noncontrolling interest (comprising Common Units issued at closing to Original Equity Owners) will be approximately %. The following table shows the economic interest of CoVolt Holdings immediately following the offering: |
| Units | % | |||||||
| CoVolt Power, Inc. |
||||||||
| Other Common Units |
||||||||
| Total Common Units |
||||||||
89
Table of Contents
Note 3 Adjustments to the Unaudited Pro Forma Condensed Consolidated Statement of Operations
The following adjustments were made related to the unaudited pro forma condensed consolidated statements of operations for the six months ended June 30, 2026 for the year ended December 31, 2025 and for the six months ended June 30, 2026:
| AA. | Represents net income/(loss) attributable to the noncontrolling interest based on the ownership structure at closing, as noted at adjustment (D). |
| BB. | Represents the pro forma adjustments to taxes resulting from all other adjustments to the statement of operations, which were calculated using the statutory income tax rate of 21%. |
Note 4 Pro Forma Income/Loss Per Share
Represents the pro forma income/(loss) per share calculated using the weighted average shares outstanding as a result of the pro forma events, assuming the shares were outstanding since January 1, 2025. As the pro forma events are being reflected as if they had occurred at the beginning of the periods presented, the calculation of weighted average shares outstanding for basic and diluted pro forma income/(loss) per share assumes that the shares issuable relating to the pro forma events have been outstanding for the entire periods presented.
| Six Months Ended June 30, 2026 |
Year Ended December 31, 2025 |
|||||||
| Pro forma basic and diluted income/(loss) per share |
||||||||
| Numerator: |
||||||||
| Pro forma net income/(loss) |
$ | $ | ||||||
| Less: Pro forma net income/(loss) attributable to non-controlling interests |
||||||||
| Pro forma net income/(loss) attributable to common shareholders–basic and diluted |
$ | $ | ||||||
| Denominator: |
||||||||
| Pro forma weighted average shares outstanding of Class A common stock–basic and diluted |
||||||||
| Pro forma basic and diluted income/(loss) per share, Class A common stock |
$ | $ | ||||||
90
Table of Contents
Table of Contents
MANAGEMENT’S DISCUSSION AND ANALYSIS OF FINANCIAL CONDITION AND RESULTS OF OPERATIONS
The following is a discussion and analysis of our financial condition and results of operations as of, and for, the periods presented and should be read in conjunction with our unaudited condensed consolidated financial statements and notes thereto included elsewhere in this prospectus. This discussion and analysis contains forward-looking statements, including statements regarding industry outlook, our expectations for the future of our business and our liquidity and capital resources as well as other non-historical statements. These statements are based on current expectations and are subject to numerous risks and uncertainties, including but not limited to the risks and uncertainties described in this prospectus under “Cautionary Note Regarding Forward–Looking Statements” and “Risk Factors”. Our actual results may differ materially from those contained in or implied by these forward-looking statements. We disclaim any obligation to update any forward-looking statements to reflect events or circumstances after the date of such statements.
Overview
We are a leading provider of engineering, procurement, and construction services to the power and data center industries. We specialize in building utility-scale solar projects, battery energy storage systems and high-voltage transmission and distribution infrastructure. Since our founding in 2005, we have built more than 7.3 GWac of generation, nearly 1.7 GWh of battery storage and T&D infrastructure that connected over 26.4 GW of capacity and load to the grid. We are recognized as a top 10 utility scale solar builder based on installations from 2015 to 2025 according to Solar Power World.
Demand for our services is growing rapidly as independent power producers add new generation to satisfy rising electricity demand, utilities upgrade and expand transmission and distribution infrastructure to support rapid load growth, and data center operators build more energy-intensive facilities. As of June 30, 2026, we had $3.6 billion of Backlog representing an increase of 410% compared to the same date in the prior year. As of June 30, 2026, 85%, 13%, and 2% of our Backlog was related to generation, T&D, and standalone battery storage project scopes, respectively. Our revenue in future periods may differ from the amounts in our backlog due to contract changes or terminations and other factors. See “Management’s Discussion and Analysis of Financial Condition and Results of Operations–Backlog” for a discussion of our backlog.
Key Factors Affecting Our Business, Results of Operations
Our revenues, profit, margins and other results of operations can be influenced by a variety of factors in any given period, including those described in the Risk Factors and Business sections in our Registration Statement on Form S-1, and those factors have caused fluctuations in our results in the past and are expected to cause fluctuations in our results in the future. Additional information with respect to certain of those factors is provided below.
We regularly review a number of metrics, including the following key operating and financial metrics, to evaluate our business, measure our performance, identify trends in our business, prepare financial projections and make strategic decisions. We believe these non-GAAP and operational measures are useful in evaluating our performance, in addition to our financial results prepared in accordance with GAAP.
Our ability to secure new project awards, expand customer relationships
Our revenue is concentrated among a limited number of large customers, including independent power producers, utilities, project developers, and data center operators. For the year ended December 31, 2025, our
92
Table of Contents
largest customer represented approximately 20% of our total revenues, and our top ten customers collectively represented approximately 96% of our total revenues. For the six months ended June 30, 2026, our largest customer represented approximately 45% of our total revenues and our three largest customers collectively represented approximately 70% of our total revenues. Our EPC contracts are typically awarded on a project-by-project basis through competitive bidding processes, and we do not have long-term volume commitments from our customers. Accordingly, our ability to generate future revenue depends on our continued success in securing new project awards from both existing and new counterparties. We compete primarily on the basis of safety, execution track record, technical capability, financial strength, price, and the ability to deliver large, complex projects on schedule and within budget. Our ability to deliver certainty in project outcomes and maintain strong safety and execution performance is a key factor in winning repeat business from existing customers. Approximately 92% of our 2025 revenue was derived from customers with whom we did business in the prior year, up from 77% in 2024, and the average tenure of our relationships with our top ten customers for the year ended December 31, 2025 was approximately 6.2 years as of June 30, 2026. In addition, our consultative sales approach, in which we engage early in the development cycle to provide guidance on technical and cost assumptions, provides visibility into upcoming opportunities and positions us to secure project awards in advance of formal competitive bidding processes. However, the competition for EPC services remains intense, and failure to meet customer expectations on cost, schedule, or safety could reduce our success rate in securing new awards and adversely impact backlog replenishment.
Customer demand for our services is closely tied to broader market conditions affecting the development of utility-scale solar projects, battery energy storage systems, and transmission and distribution infrastructure. Recently, demand has been driven by the rapid increase in AI data center development and accelerating electrification across transportation, buildings, and industry, which has contributed to record power consumption and substantial new market opportunities. These conditions are influenced by factors such as power prices, the availability of tax incentives, regulatory policies, and the cost and availability of financing. However, actual demand is subject to material uncertainty due to factors outside of our control, such as technology advances, energy efficiency gains, and cyclical changes in potential customer investment patterns. The industry is capital-intensive, and our customers’ ability to initiate and complete projects depends on their access to tax equity, debt financing, and equity capital. Adverse changes in capital markets, including rising interest rates, reduced liquidity, or changes in tax credit regimes, may delay or reduce project development activity and, in turn, demand for our services. Sustained growth will depend on our ability to adapt to evolving demand and maintain disciplined capital allocation in the face of both opportunity and risk.
As we continue to expand our capabilities across solar, storage, and high-voltage transmission and distribution infrastructure, we expect to enhance our ability to cross-sell services to existing customers and diversify our customer base across a broader set of counterparties and end markets. We also expect to benefit from long-term structural demand drivers in solar energy and battery storage and infrastructure development, which may support sustained project activity over time.
Our ability to execute projects consistent with our budgeted cost
Our financial performance depends on our ability to execute projects safely, on time, and within budget under lump sum EPC contracts, where we bear the risk that actual costs of labor, materials, equipment, and other project inputs may exceed our initial estimates. The accuracy of our cost estimates and the efficiency of our project execution are the primary drivers of our profitability. Variability in project start dates, permitting timelines, customer readiness, and interconnection approvals can materially impact the timing and amount of revenue we recognize in any given period, and delays in large utility-scale projects may shift revenue and margin realization across reporting periods.
93
Table of Contents
We have invested significantly in enhancing our project execution capabilities, including strengthening project controls, improving reporting and data analytics, formalizing delivery protocols, and reinforcing governance and oversight at all stages of the project lifecycle. We conduct rigorous internal reviews of project assumptions, pricing, and contractual terms, and require senior management approval prior to executing significant contracts. Our LNTP contracting process is a key risk mitigation tool, allowing us to perform site evaluations, advance engineering work, and better assess project-specific conditions before committing to a final contract price. Our self-perform model, supported by our trained workforce of more than 5,000 qualified craftworkers and technicians, standardized processes, and dedicated equipment fleet, provides us with direct control over safety, quality, scheduling, and labor productivity, which are key drivers of margin performance. In addition, our front-end engineering capabilities allow us to identify and mitigate design, permitting, procurement, and constructability risks prior to construction, supporting more predictable execution and reducing the likelihood of cost overruns.
As we continue to scale our operations, we expect to improve the predictability and efficiency of our project execution through enhanced project planning, more standardized execution processes, and increased coordination across procurement, labor, and project management functions. As our project volume and diversity grows, we expect the financial impact of any single project delay or cost overrun to become less pronounced relative to our overall results. We are increasingly leveraging historical project data and enhanced estimating tools to better assess site conditions, cost inputs, and execution risks prior to entering into contracts. Over time, we expect these efforts to further improve our margin consistency and reduce variability in project outcomes.
Our ability to convert backlog into revenue and profits on the timeline we expect
Our backlog represents the estimated $3.6 billion revenue from signed contracts and awarded projects that we expect to recognize in future periods and is a key indicator of our near-to medium-term revenues. We anticipate recognizing substantially all of our backlog into revenue within the next 18 to 30 months. However, backlog is not necessarily indicative of future revenue in a specific period, as projects may be delayed, modified, or cancelled due to factors outside of our control, including changes in customer financing, permitting timelines, grid interconnection, or shifts in customer priorities. While our contracts generally provide for payment for work performed and, in certain cases, termination fees, the timing and amount of revenue recognized from backlog may vary from our expectations.
We recognize revenue using the percentage-of-completion method based on costs incurred relative to total estimated costs, which requires judgment in estimating total project costs over the life of each contract.
Changes in these estimates may result in adjustments to previously recognized revenue. In addition, the timing of project milestones, equipment deliveries, and customer-directed scope changes can introduce variability in our quarterly results and have a meaningful impact on revenue and profit recognition in any given period.
Our model is designed to support efficient and predictable conversion of backlog into revenue and profit through a combination of disciplined project selection, phased contracting structures, and tight execution controls. Our use of LNTP agreements allows us to validate engineering, procurement, and site-specific assumptions prior to finalizing EPC contract pricing, which enhances cost visibility and reduces execution risk. Once projects move into construction, our self-perform capabilities and established supplier relationships provide greater control over critical path activities, supporting predictable execution and profit recognition.
Our ability to attract and retain skilled labor at predictable costs
Our projects are labor-intensive, and our profitability depends, in part, on securing sufficient skilled labor at predictable costs across multiple geographies and project timelines. Tight labor markets, regional wage
94
Table of Contents
inflation, and competition from other infrastructure, energy, and construction sectors can put significant upward pressure on wage rates, per diem costs, and other labor-related expenses. These pressures are often amplified in remote project locations where workforce availability is limited and mobilization costs are higher.
In addition to wage rates, our financial performance is sensitive to labor productivity at job sites. Variability in crew experience, site conditions, weather disruptions, and project complexity can result in productivity levels that differ from our initial estimates. Lower-than-expected productivity or inefficiencies in labor deployment, such as underutilization, overtime requirements, or rework, can increase total project costs and extend project schedules. These risks are particularly pronounced under lump sum EPC contracts, where we bear the financial impact of cost overruns and are generally unable to pass through incremental labor costs to customers. We maintain an extensive and actively curated database of more than 5,000 qualified craftworkers and technicians and operate a Department of Labor-approved Registered Apprenticeship Program to expand our pipeline of qualified workers. While these initiatives support our ability to staff projects, they require ongoing investment and may not fully offset broader labor shortages. Additionally, when we use subcontracted labor, we introduce further variability in labor cost, availability, and performance, as subcontractors are subject to the same market pressures.
As we continue to scale our operations, we expect to improve the efficiency of our workforce management and reduce per-employee administrative and overhead costs through increased standardization, centralized workforce planning, and investments in workforce management systems. However, our ability to realize these efficiencies will depend on maintaining sufficient project volume and effectively managing the complexity associated with a larger and more geographically dispersed workforce. Our ability to effectively forecast labor needs, negotiate competitive wage structures, and maintain high levels of workforce productivity is critical to achieving expected project margins. Failure to do so could result in margin compression, project delays, and reduced overall profitability.
Our ability to manage equipment vendors and potential supply chain constraints
Our projects require significant quantities of equipment and materials, including trackers, inverters, transformers, circuit breakers, and other balance-of-system components. Equipment that we procure typically represents approximately 40% of the total value of our EPC contracts, making effective supply chain management critical to project execution and financial performance. Supply chain conditions are influenced by global manufacturing capacity, transportation constraints, tariffs, and geopolitical factors, which can affect pricing and lead times. The timely availability of equipment is essential to maintaining project schedules and revenue recognition, particularly for constrained components such as high-voltage transformers and circuit breakers with extended lead times, while key solar components such as modules, trackers, and inverters are generally available in under six months, supporting more predictable procurement cycles.
Our contracting structure and procurement approach are designed to mitigate a significant portion of supply chain risk. Solar modules and batteries, which represent a substantial portion of total project cost, are typically purchased directly by our customers, limiting our exposure to price volatility and delivery risk on these components. In addition, our contracts generally allow us to pass through import tariffs and certain cost changes through change order mechanisms, shifting a portion of pricing risk to our customers. We further mitigate risk through supplier diversification, early procurement, and master supply agreements with key vendors that provide us with preferred pricing, secured capacity, and improved access to long-lead equipment.
As we scale our operations and increase procurement volumes, we expect to improve our purchasing leverage and supply chain planning capabilities, which may allow us to secure more favorable pricing, priority access to constrained components, and greater visibility into delivery timelines. We also expect to benefit from increased standardization of equipment specifications and more centralized procurement processes. Our ability to
95
Table of Contents
effectively manage equipment sourcing, pricing, and logistics is critical to maintaining project timelines, controlling costs, and achieving expected job margins.
Our ability to manage risk under lump sum contracts
A substantial portion of our revenues is generated from EPC contracts structured on a lump sum basis, under which we agree to deliver a defined scope of work for a lump sum. This contract structure enables us to capture value through disciplined estimating and efficient execution, as margins are driven by our ability to accurately price projects and deliver them at or below expected costs. As a result, our financial performance is closely tied to the strength of our estimating processes and our ability to execute projects in line with our estimates.
We have developed a comprehensive and increasingly disciplined approach to managing risk across the project lifecycle. Our LNTP contracting process allows us to perform site evaluations, advance engineering work, and validate key assumptions prior to committing to a final EPC contract price, improving cost visibility and reducing execution uncertainty. We complement this approach with standardized contract terms, change order protections, and rigorous internal review processes. Since 2022, we have enhanced our risk management framework through the implementation of a formal bid/no-bid committee, required site-level diligence prior to bid submission, board oversight for larger projects, and detailed risk registers reviewed by subject matter experts. In addition, we conduct regular, finance-led project reviews focused on cost performance, schedule adherence, and risk identification, supported by project controls personnel who report directly to our Chief Financial Officer. Together, these processes are designed to drive accountability, improve cost discipline, and support consistent project outcomes.
As we continue to refine our contracting and project evaluation processes, we expect to improve our ability to identify, price, and manage risks inherent in lump sum contracts. We are increasingly leveraging historical project data, enhanced estimating tools, and more rigorous pre-construction diligence to better assess site conditions, cost inputs, and execution risks prior to entering into contracts. We also expect to maintain a disciplined approach to project selection and contract structuring, including pursuing opportunities with more balanced risk allocation and stronger contractual protections where appropriate. Over time, we expect that these efforts will improve margin consistency and reduce the likelihood of significant cost overruns, although lump sum contracts will continue to expose us to variability in project outcomes.
Our ability to maintain safety and operational excellence
Safety is the foundation of our operations and a core value embedded throughout our organization. Construction projects involve inherent risks, and our ability to maintain a strong safety record directly impacts our operational performance, insurance costs, and reputation with customers. Incidents at project sites can result in injuries, work stoppages, regulatory scrutiny, and increased costs, all of which may adversely affect project timelines, productivity, and our overall profitability.
We utilize a data-driven approach to safety management, integrating leading indicators, near-miss reporting, and real-time field observations to identify emerging risks and proactively mitigate potential incidents. Our safety programs are designed to promote a culture of accountability and continuous improvement across all levels of the organization, including employees and subcontractors. Effective implementation of these programs is critical to maintaining consistent performance across a geographically dispersed project portfolio with varying site conditions and workforce composition.
Our safety performance also influences our ability to secure new project awards, as many customers require contractors to meet specified safety thresholds or maintain certain experience modification rates (EMR) to qualify for bidding on projects. A strong safety track record can enhance our competitiveness, while any
96
Table of Contents
deterioration in safety performance could limit access to certain projects or increase the cost of insurance and bonding. In addition, workplace incidents can disrupt construction schedules, reduce labor productivity, and result in reputational harm.
As we continue to advance our safety programs, we expect to further integrate technology, analytics, and standardized processes to enhance visibility into field conditions and improve risk identification and mitigation. We also expect ongoing investment in training, workforce engagement, and safety leadership to reinforce our safety culture and drive consistent execution across projects. Over time, we expect these efforts will support improved operational performance, reduced incident rates, and greater predictability in project execution.
We report our financial results in accordance with GAAP. We also present Adjusted EBITDA, Adjusted EBITDA Margin, and Free Cash Flow, which are non-GAAP financial measures that we believe provide useful information to investors regarding our operating performance and cash generation. Our management uses these non-GAAP measures, together with our GAAP financial results, to evaluate our business, measure our performance, identify trends, prepare financial projections, and make strategic decisions. These non-GAAP measures should not be considered in isolation or as a substitute for analysis of our results as reported under GAAP. You are encouraged to evaluate each adjustment and the reasons we consider it appropriate for supplemental analysis. In addition, in evaluating these non-GAAP measures, you should be aware that in the future we may incur expenses similar to the adjustments in these presentations. Our presentation of non-GAAP financial measures should not be construed as an inference that our future results will be unaffected by these or other unusual or non-recurring items. Additionally, our non-GAAP measures may not be comparable to similarly titled measures used by other companies in our industry or across different industries. For a reconciliation of these non-GAAP financial measures to the most directly comparable GAAP measures, see “–Non-GAAP Financial Measure Reconciliations” below.
The following table sets forth a summary of our financial highlights for the periods indicated (dollar amounts in millions):
| Six Months Ended June 30, |
Year Ended December 31, |
|||||||||||||||
| 2026 | 2025 | 2025 | 2024 | |||||||||||||
| Revenue |
$ | 308.3 | $ | 451.4 | $ | 739.4 | $ | 442.7 | ||||||||
| Gross profit |
54.1 | 61.5 | 102.3 | 31.6 | ||||||||||||
| Net income |
35.4 | 43.2 | 60.6 | (9.0 | ) | |||||||||||
| Adjusted EBITDA(1) |
$ | 42.3 | $ | 53.2 | $ | 80.5 | $ | 17.0 | ||||||||
| Adjusted EBITDA Margin(1) |
13.7 | % | 11.8 | % | 10.9 | % | 3.8 | % | ||||||||
| Free Cash Flow(1) |
$ | 5.5 | $ | (7.6 | ) | $ | 77.8 | $ | 72.0 | |||||||
| Backlog(2) |
$ | 3,614 | $ | 709 | $ | 1,684 | $ | 1,198 | ||||||||
| (1) | Adjusted EBITDA, Adjusted EBITDA Margin, and Free Cash Flow are non-GAAP financial measures. See “–Non-GAAP Financial Measures” below for our definition of, and additional information about, Adjusted EBITDA, Adjusted EBITDA Margin and Free Cash Flow, and for a reconciliation to net income and net cash provided by (used in) operating activities, respectively, the most directly comparable U.S. GAAP financial measures. |
| (2) | We define Backlog as the estimated revenue we expect to realize from the remaining transaction price on projects that have been awarded to us or for which we have signed contracts. Backlog is comprised of Signed Backlog and Awarded Backlog and is not a measure defined by U.S. GAAP; accordingly, our methodology for determining Backlog may not be comparable to methodologies used by other companies in determining their backlog amounts. |
Key Operating and Financial Metrics
Adjusted EBITDA and Adjusted EBITDA Margin
We define “Adjusted EBITDA” as net income (loss) attributable to CoVolt Holdings Group, LLC before (i) interest expense (income), net, (ii) provision for income taxes, (iii) depreciation and amortization, (iv) non-cash
97
Table of Contents
compensation expense, (v) retention and recruiting costs associated with our management transition, (vi) costs associated with our organizational transformation and strategic review, (vii) costs associated with the wind-down of our non-core operations, (viii) legal settlements and (ix) costs incurred in connection with this offering. See “–Non-GAAP Financial Measures” below for additional information about Adjusted EBITDA and for a reconciliation from net income attributable to CoVolt Holdings Group, LLC, the most directly comparable U.S. GAAP financial measure.
We define Adjusted EBITDA Margin as Adjusted EBITDA divided by revenue. We use Adjusted EBITDA Margin to evaluate the efficiency with which we convert revenue into Adjusted EBITDA, and we believe this metric is useful to investors and analysts in assessing our operating performance and comparing it against that of other companies in our industry.
Free Cash Flow
We define Free Cash Flow as net cash provided by operating activities less purchases of property and equipment (capital expenditures). Free Cash Flow is a non-GAAP financial measure. See “Management’s Discussion and Analysis of Financial Condition and Results of Operations–Non-GAAP Financial Measures” for additional information about Free Cash Flow and for a reconciliation to net cash provided by (used in) operating activities, the most directly comparable U.S. GAAP financial measure.
Backlog
We define Backlog as the estimated revenue we expect to realize from the remaining transaction price on projects that have been awarded to us or for which we have signed contracts. Backlog is comprised of Signed Backlog and Awarded Backlog. As of June 30, 2026, we had $3.6 billion of Backlog representing an increase of 410% compared to the same date in the prior year of which approximately 85%, 13%, and 2% was attributable to generation, T&D, and standalone battery storage, project scopes respectively.
Our largest active EPC contracts, which collectively represent approximately 13% of our total backlog, are predominantly lump sum contracts for utility-scale solar generation facilities located primarily in Texas and Kentucky, with contract values generally ranging from approximately $100 million to $250 million and anticipated substantial completion dates between 2026 and 2027.
Signed Backlog
We define Signed Backlog as the anticipated revenue from the uncompleted portions of existing contracts where scope is adequately defined and we have enforceable rights to consideration. Signed Backlog includes: (i) the remaining unrecognized value of fully executed EPC contracts and (ii) the authorized value of executed LNTP agreements on projects for which the full EPC contract has not yet been executed, limited to the scope and consideration specifically authorized under the LNTP. The remaining value of EPC contracts can increase or decrease based on change orders mutually agreed between us and the customer during the construction process. As of June 30, 2026 and December 31, 2025, Signed Backlog was $565 million and $590 million, respectively.
Awarded Backlog
We define Awarded Backlog as the anticipated revenue from: (i) projects for which we have received a formal written award notification from the customer identifying the Company as the selected EPC contractor, where
project scope is adequately defined and EPC contract execution is in process; and (ii) the remaining expected EPC contract value, above and beyond the LNTP scope already reflected in Signed Backlog, of projects currently
98
Table of Contents
operating under an executed LNTP agreement for which the full EPC contract has not yet been executed. Several of our other prospective projects have received written awards but have not yet been converted to executed EPC agreements; customers are not obligated to execute definitive EPC contracts following receipt of an award letter. The anticipated contract value for each project included in Awarded Backlog is based on the agreed or anticipated contract price as communicated in connection with the award or LNTP process. Each project in Awarded Backlog is supported by a customer written document specifying the project and selected contractor. As of June 30, 2026 and December 31, 2025, Awarded Backlog was $3 billion and $1 billion, respectively.
Reconciliation of Non-GAAP Metrics
The following table presents a reconciliation of net income (loss) attributable to CoVolt Holdings Group, LLC, the most directly comparable GAAP financial measure, to Adjusted EBITDA for each of the periods presented (dollar amounts in thousands).
| Six Months Ended June 30, |
Year Ended December 31, |
|||||||||||||||
| 2026 | 2025 | 2025 | 2024 | |||||||||||||
| Net income |
$ | 35,360 | $ | 43,237 | $ | 60,581 | $ | (9,009 | ) | |||||||
| Interest expense |
279 | 256 | 654 | 1,945 | ||||||||||||
| Interest income |
(1,614 | ) | (445 | ) | (1,297 | ) | (29 | ) | ||||||||
| Taxes |
464 | 9 | 92 | 146 | ||||||||||||
| Depreciation and amortization |
2,184 | 5,741 | 10,710 | 10,713 | ||||||||||||
| Unit-based compensation(1) |
210 | 300 | 601 | 2,761 | ||||||||||||
| Severance, retention and recruiting costs associated with management transition(2) |
663 | 2,055 | 2,677 | 2,154 | ||||||||||||
| Costs associated with our organizational transformation and strategic review(3) |
1,417 | 2,430 | 6,440 | 5,409 | ||||||||||||
| Wind-down of non-core operations(4) |
1,910 | (394 | ) | 43 | 1,693 | |||||||||||
| Legal Settlements(5) |
— | — | — | 1,188 | ||||||||||||
| Costs incurred in connection with this initial public |
1,457 | — | — | — | ||||||||||||
| Adjusted EBITDA |
$ | 42,330 | $ | 53,189 | $ | 80,501 | $ | 16,971 | ||||||||
| (1) | Represents non-cash charges associated with unit-based compensation awards granted to employees and directors. We exclude unit-based compensation expense from Adjusted EBITDA because it is a non-cash charge that varies based on factors including grant date fair value, vesting schedules, and forfeitures, and we believe excluding this item facilitates comparisons of operating performance across periods and with peer companies. |
| (2) | Represents severance costs, retention and signing bonuses, and recruiting fees incurred in connection with our management transition following the change of control in 2023. These costs relate to severance and separation benefits provided to certain former executives and employees, retention bonuses to key employees, signing bonuses and other one-time compensation paid to newly hired senior managers, and fees paid to third-party executive search and recruiting firms. These costs are not reflective of our ongoing operating cost structure and are not expected to reoccur once fully settled. The Company expects the remaining restructuring and implementation activities to be completed by the end of 2026, and does not expect these costs to recur as part of its normal operating cost structure thereafter. |
| (3) | Represents third-party consulting and advisory fees and other costs incurred in connection with organizational transformation activities we undertook following the Company’s change of control in 2023, evaluation and pursuit of potential strategic and capital markets transactions. These costs include discrete engagements for accounting and finance advisory, strategic planning, organizational assessment, office relocation, initial compliance infrastructure buildout, identified strategic and capital markets transactions. Each consulting or advisory engagement had a defined scope of work and an identified start and end date. These costs are not reflective of our ongoing operating cost structure and are not expected to reoccur once completed. The Company expects the remaining restructuring and implementation activities to be completed by the end of 2026, and does not expect these costs to recur as part of its normal operating cost structure thereafter. |
| (4) | Represents costs incurred solely to resolve and settle close-out activities of the Company’s legacy Australia and wind operations, which are not part of the Company’s go-forward business strategy or continuing revenue-generating activities. These costs primarily relate to resolving open commercial matters and settling outstanding claims, disputes, or other project close-out matters associated with these legacy operations. |
99
Table of Contents
| During the six months ended June 30, 2026, the Company recorded approximately $1.9 million of such costs related to the write-off of receivables associated with a legacy project in Australia. Management determined that the receivable was no longer probable of collection based on the potentially unfavorable status of the related commercial dispute. The Company ceased pursuing new work in these operations in 2021 and, since that time, has had no new backlog, project awards, bidding activity or ongoing revenue-generating activities associated with these operations. The legacy Australia and wind operations are not part of the Company’s go-forward business strategy and represented less than 1% of the Company’s consolidated revenue, net income and assets during the periods presented. Accordingly, management does not believe these costs are representative of the Company’s current operating cost structure or ongoing operating performance. The Company expects the remaining matters to be resolved by the end of 2026, subject to the timing of third-party claim and dispute-resolution processes. |
| (5) | Represents legal fees and settlement costs incurred in connection with a dispute with a subcontractor. The matter has been settled. These costs are incremental to and distinguishable from our routine litigation expenses and are not expected to reoccur. We have not adjusted for legal costs incurred in the ordinary course of our construction and project operations, including routine contract disputes, employment matters, and regulatory compliance. |
| (6) | Represents costs incurred related to professional services fees or other costs directly attributable to the Company’s transition to a public company. These items are not indicative of our ongoing operating performance and are not expected to reoccur. |
The following table presents a reconciliation of Adjusted EBITDA Margin for each of the periods presented (dollar amounts in thousands):
| Six Months Ended June 30, |
Year Ended December 31, |
|||||||||||||||
| 2026 | 2025 | 2025 | 2024 | |||||||||||||
| Adjusted EBITDA |
$ | 42,330 | $ | 53,189 | $ | 80,501 | $ | 16,971 | ||||||||
| Revenue |
308,278 | 451,379 | $ | 739,405 | $ | 442,724 | ||||||||||
| Adjusted EBITDA Margin |
13.7% | 11.8% | 10.9% | 3.8% | ||||||||||||
The following table presents a reconciliation of net cash provided by operating activities to Free Cash Flow for the periods presented (dollar amounts in thousands).
| Six Months Ended June 30, |
Year Ended December 31, |
|||||||||||||||
| 2026 | 2025 | 2025 | 2024 | |||||||||||||
| Net cash provided by (used in) operating activities |
$ | 6,269 | $ | (7,417 | ) | $ | 78,136 | $ | 72,297 | |||||||
| Purchases of property and equipment |
(763 | ) | (193 | ) | (365 | ) | (266 | ) | ||||||||
| Free Cash Flow |
$ | 5,506 | $ | (7,610 | ) | $ | 77,771 | $ | 72,031 | |||||||
Components of our Results of Operations
The following discussion describes certain line items in our consolidated statements of income.
Revenue
We provide EPC services to our customers primarily under lump sum contracts pursuant to long-term contracts. We recognize revenue from EPC services using the percentage-of-completion method, which is generally measured as the percentage of costs incurred to date to total estimated costs. The percentage-of-completion is then multiplied by estimated total contract values to determine revenue in the period.
Our actual revenue from EPC services can vary, sometimes substantially, from previous estimates due to changes in a variety of factors, including unforeseen or changed circumstances not included in management’s cost estimates or covered by the contracts. Changes in cost estimates on certain contracts may result in the issuance of change orders, which can be approved or unapproved by the customer, or the assertion of contract claims. Management determines the probability that costs associated with change orders and claims will be recovered based on, among other things, contractual entitlement, past practices with the customer and specific discussions or preliminary negotiations with the customer.
100
Table of Contents
Change orders are a type of variable consideration that are generally not distinct from the existing contract due to the significant integration service provided in the context of the contract. Estimates of variable consideration and the determination of whether to include estimated amounts in the transaction price are based on an assessment of the anticipated performance and all information that is reasonably available. We recognize revenue for variable consideration when it is probable that a significant reversal in the amount of cumulative revenue recognized will not occur or when the uncertainty associated with the variable consideration is resolved.
Cost of revenue
Cost of revenue consists primarily of construction related labor, materials, and equipment rentals, which are expensed as incurred. Estimated losses on contracts, or the excess of the total estimated costs to complete a contract over the contract’s total estimated contract price, are recognized in the period in which such losses are determined. Factors impacting our cost of revenue and gross profit are described in the “–Results of Operations” section below.
General and administrative
General and administrative expenses consist of corporate operating expenses including office rent expense, information technology, accounting, legal, and human resources, which are expensed as incurred. We anticipate that our general and administrative expenses will increase as a result of becoming a public company.
Interest expense
Interest expense consists of interest expense on debt issuance costs and original issuance discounts, finance leases and amortization of deferred financing costs.
Interest income
Interest income consists of interest earned on cash, and other investments.
Other (expense) income, net
Other (expense) income, net consists of interest income earned on customer late payments and provision and/or write-off of certain non-trade receivables.
Income tax expense
Our business was historically operated through CoVolt Holdings Group, LLC (formerly known as SEC Holdings Group, LLC), a limited liability company. For U.S. federal income tax purposes, CoVolt Holdings Group, LLC was historically treated as an entity disregarded as separate from SEC Parent II, LLC (“the Ultimate Parent”), which is a partnership for U.S. federal income tax purposes. As a disregarded entity, CoVolt Holdings Group, LLC was not subject to U.S. federal income tax; however, historical income tax expense reflects certain state and local taxes.
In connection with the Transactions, CoVolt Holdings Group, LLC will become a partnership for U.S. federal income tax purposes and CoVolt Power, Inc will acquire Common Units in CoVolt Holdings Group, LLC. As a partnership for U.S. federal income tax purposes, CoVolt Holdings Group, LLC will generally not be subject to U.S. federal income tax. As a result of its ownership of Common Units, CoVolt Power, Inc, which is a corporation for U.S. federal income tax purposes, will be subject to U.S. federal, state and local income taxes with respect to its allocable share of any taxable income of CoVolt Holdings Group, LLC and will be taxed at the prevailing corporate tax rates.
101
Table of Contents
Results of Operations
A discussion of our results of operations for the six months ended June 30, 2026 and 2025, are set forth below.
Six Months Ended June 30, 2026 Compared to Six Months Ended June 30, 2025
The following table summarizes our year to date condensed consolidated results of operations, including the dollar and percentage change from the prior year (dollar amounts in thousands):
| Six Months Ended June 30, |
Change | |||||||||||||||
| 2026 | 2025 | $ | $ | |||||||||||||
| Revenue |
$ | 308,278 | $ | 451,379 | $ | (143,101 | ) | (32% | ) | |||||||
| Cost of revenue |
254,158 | 389,895 | (135,737 | ) | (35% | ) | ||||||||||
| Gross profit |
54,120 | 61,484 | (7,364 | ) | (12% | ) | ||||||||||
| General and administrative |
18,537 | 14,370 | 4,167 | 29% | ||||||||||||
| Depreciation and amortization |
914 | 4,429 | (3,515 | ) | (79% | ) | ||||||||||
| Gain on disposal of assets |
(193 | ) | — | (193 | ) | 100% | ||||||||||
| Total operating expenses |
19,258 | 18,799 | 459 | 2% | ||||||||||||
| Operating income |
34,862 | 42,685 | (7,823 | ) | (18% | ) | ||||||||||
| Interest income |
1,614 | 445 | 1,169 | 263% | ||||||||||||
| Interest expense |
(279 | ) | (256 | ) | (23 | ) | 9% | |||||||||
| Other (expense) income, net |
(837 | ) | 363 | (1,200 | ) | (331% | ) | |||||||||
| Net income |
35,360 | 43,237 | (7,877 | ) | (18% | ) | ||||||||||
| Net income attributable to non-controlling interest |
— | — | — | 0% | ||||||||||||
| Net income attributable to CoVolt Holdings Group, LLC |
$ | 35,360 | $ | 43,237 | $ | (7,877 | ) | (18% | ) | |||||||
Revenue
Revenue decreased by $143.1 million to $308.3 million for the six months ended June 30, 2026, compared to $451.4 million for the six months ended June 30, 2025. This was primarily due to timing of project mobilizations as a greater number of projects mobilized in the prior-year period. Uncertainty surrounding changes related to certain tax incentives related to the negotiations and ultimate passage of the One Big Beautiful Bill Act (“OBBBA”) and tariffs uncertainty caused some of our customers to delay project starts to gain greater clarity around project economics. This resulted in a decrease in revenue from existing projects of $155.3 million, partially offset by revenue generated from new construction projects of $13.7 million and completed projects of $4.1 million. The decrease in revenue was driven by the timing of project mobilizations and is not indicative of an expected decline in our full-year results.
Cost of Revenue
Cost of revenue decreased by $135.7 million to $254.2 million for the six months ended June 30, 2026, compared to $389.9 million for the six months ended June 30, 2025, which generally correlates to the decrease in revenue.
Gross Profit
Gross profit decreased by $7.4 million to $54.1 million for the six months ended June 30, 2026, compared to $61.5 million for the six months ended June 30, 2025, primarily attributable to lower contract revenues in the period. Gross margin increased by 400 basis points to 17.6% for the six months ended June 30, 2026, compared to 13.6% for the six months ended June 30, 2025, primarily driven by favorable execution on projects nearing completion.
102
Table of Contents
General and administrative expenses
General and administrative expenses increased by $4.2 million to $18.5 million for the six months ended June 30, 2026, compared to $14.4 million for the six months ended June 30, 2025, which was primarily driven by $1.5 million in costs incurred in connection with an initial public offering, $1.8 million in increased people and technology related costs, and $0.4 million in connection with the rebrand from legacy brands to CoVolt Power.
Depreciation and amortization expense
Depreciation and amortization expense decreased by $3.5 million to $0.9 million for the six months ended June 30, 2026, compared to $4.4 million for the six months ended June 30, 2025, which was primarily the result of a decrease in amortization of intangibles due to customer relationships and non-compete intangible assets becoming fully amortized during 2025.
Interest Income
Interest income increased by $1.2 million to $1.6 million for the six months ended June 30, 2026, from $0.4 million for the six months ended June 30, 2025, due to increased investment balances during 2026 as compared to the same period in 2025.
Other (expense) income, net
Other (expense) income, net decreased by $1.2 million from other income of $0.4 million for the six months ended June 30, 2025, to other expense of $0.8 million for the six months ended June 30, 2026, primarily attributable to the provision of certain non-trade receivables.
Year Ended December 31, 2025 Compared to Year Ended December 31, 2024
The following table summarizes our annual consolidated results of operations, including as a percentage of revenue, as well as the dollar and percentage change from the prior year:
| Year Ended December 31, | Change | |||||||||||||||||||||||
| (dollars in thousands) | 2025 | 2024 | $ | % | ||||||||||||||||||||
| Revenue |
$ | 739,405 | 100.0% | $ | 442,724 | 100.0% | $ | 296,681 | 67.0% | |||||||||||||||
| Cost of revenue |
637,137 | 86.2% | 411,146 | 92.9% | 225,991 | 55.0% | ||||||||||||||||||
| Gross profit |
102,268 | 13.8% | 31,578 | 7.1% | 70,690 | 223.9% | ||||||||||||||||||
| General and administrative |
34,413 | 4.6% | 29,838 | 6.7% | 4,575 | 15.3% | ||||||||||||||||||
| Depreciation and amortization |
8,040 | 1.1% | 8,852 | 2.0% | (812 | ) | -9.2% | |||||||||||||||||
| Loss (gain) on disposal of assets |
69 | NM | (165 | ) | NM | 234 | NM | |||||||||||||||||
| Total operating expenses |
42,522 | 5.7% | 38,525 | 8.7% | 3,997 | 10.4% | ||||||||||||||||||
| Operating income (loss) |
59,746 | 8.1% | (6,947 | ) | -1.6% | 66,693 | 960.0% | |||||||||||||||||
| Interest expense |
(654 | ) | NM | (1,945 | ) | -0.4% | 1,291 | -66.4% | ||||||||||||||||
| Interest income |
1,297 | 0.2% | 29 | NM | 1,268 | 4,372.4% | ||||||||||||||||||
| Other income (expense), net |
192 | NM | (146 | ) | NM | 338 | NM | |||||||||||||||||
| Net income (loss) |
60,581 | 8.2% | (9,009 | ) | -2.0% | 69,590 | 772.4% | |||||||||||||||||
| Less: net income attributable to non-controlling interest |
— | 0.0% | — | 0.0% | — | 0.0% | ||||||||||||||||||
| Net income (loss) attributable to controlling interests |
$ | 60,581 | 8.2% | (9,009 | ) | —2.0% | 69,590 | 772.4% | ||||||||||||||||
103
Table of Contents
NM – Percentage is not meaningful
Revenue
Revenue increased by $296.7 million to $739.4 million for the year ended December 31, 2025, compared to $442.7 million for the year ended December 31, 2024, which was primarily a result of increased activity on existing projects of $211.3 million and contributions from new construction projects of $85.5 million due to increased demand of the Company’s services.
Cost of revenue
Cost of revenue increased by $226.0 million to $637.1 million for the year ended December 31, 2025, compared to $411.1 million for the year ended December 31, 2024, which generally correlates to the increase in revenue.
Gross Profit
The increase in gross margin was primarily driven by improved field productivity and enhanced project execution across our projects.
General and administrative expenses
General and administrative expenses increased by $4.6 million to $34.4 million for the year ended December 31, 2025, compared to $29.8 million for the year ended December 31, 2024, which was primarily a result of a $2.5 million increase in labor related compensation cost primarily due to higher bonus expense, $3.4 million increase in overheads which generally scaled with revenue growth, offset by $1.3 million decrease in professional consulting expenses primarily due to reduced third-party advisory services.
Depreciation and amortization expense
Depreciation and amortization expense decreased by $0.8 million to $8.0 million for the year ended December 31, 2025, compared to $8.8 million for the year ended December 31, 2024, which was primarily the result of a decrease in amortization of intangibles, due to the useful lives for customer relationships and non-competes ending during 2025.
Interest expense
Interest expense decreased by $1.2 million to $0.7 million for the year ended December 31, 2025, compared to $1.9 millon for the year ended December 31, 2024, which was primarily as a result of lower average outstanding balances of our debt and associated debt issuance cost, which resulted in a reduction of interest expense.
Liquidity and Capital Resources
Sources and Uses of Liquidity
We have historically funded our operations and business activities primarily from cash flows from operating activities as well as borrowings under our Credit Facilities (as defined herein). As of June 30, 2026, we had no revolving borrowings outstanding, $4.7 million of letters of credit outstanding, and $55.3 million of available capacity under the Revolving Credit Agreement (as defined herein).
104
Table of Contents
Historically, our primary funding needs were to fund operations, make distributions to the Parent, make payments pursuant to the terms of our Credit Facilities, and fund business development activity. To address these short-term liquidity requirements, we anticipate relying on our existing cash, the net cash flows generated by our operations, and availability under our Revolving Facility.
Upon completion of our initial public offering, we expect that our primary funding needs will be to fund operations, make tax distributions, make payments pursuant to the terms of our Credit Facilities, pay income taxes and fund business development activities, including acquisitions.
CoVolt Power, Inc. was formed for the purpose of facilitating our initial public offering and has engaged to date only in activities in contemplation of this offering. CoVolt Power, Inc. is a holding company, which will have no material assets other than its ownership of Common Units. As a consequence, our ability to declare and pay dividends to the holders of our Class A common stock will be subject to the ability of CoVolt Holdings to provide distributions to us. Deterioration in the financial condition, earnings or cash flow of CoVolt Holdings for any reason could limit or impair CoVolt Holdings’ ability to pay such distributions to us. Additionally, to the extent that we need funds and CoVolt Holdings is restricted from making such distributions under applicable law or regulation or under the terms of any financing arrangements, or CoVolt Holdings is otherwise unable to provide such funds, it could materially adversely affect our liquidity and financial condition.
We anticipate that the distributions we will receive from CoVolt Holdings may, in certain periods, exceed our actual tax liabilities, and other expenses. Our board of directors will determine the appropriate uses for any excess cash so accumulated, which may include, among other uses, the payment of obligations under the Tax Receivable Agreement and the payment of other expenses. We will have no obligation to distribute such cash (or other available cash) to our shareholders. As a result, the holders of Common Units (other than us) may benefit from value, if any, attributable to such cash balances if they acquire shares of Class A common stock in exchange for their Common Units, notwithstanding that such holders may have participated previously as holders of Common Units in distributions that resulted in such excess cash balances to us.
We believe that our existing cash balances, cash flows from our operations, and borrowings under our Revolving Facility and our new Revolving Facility (defined below) entered into in relation to the IPO will be sufficient to fund our operations for at least the next twelve months. However, future cash flows are subject to a number of variables, including significant expenditures that may be required to conduct our operations. There can be no assurance that operations and other capital resources will provide cash in sufficient amounts to maintain planned or future levels of expenditures or to make future acquisitions. In the event that the amount of capital required is greater than the amount we have available, we could be required to reduce the expected level of expenditures and/or seek additional capital. We anticipate that to the extent that we require additional liquidity, it will be funded through the proceeds from this offering, the incurrence of additional indebtedness, the issuance of additional equity, or a combination thereof. If we seek additional capital, we may do so through additional borrowings under our Credit Facilities, offerings of debt or equity securities, other financing transactions, joint ventures, asset sales, or other means. We cannot guarantee that such additional capital will be available to us on acceptable terms or at all. Additionally, our liquidity and our ability to meet our obligations and fund our capital requirements are also dependent on our future financial performance, which is subject to general economic, financial and other factors that are beyond our control. Refer to the Risk Factors section which appears elsewhere in this Registration Statement. If we are unable to generate sufficient cash flow from operations or otherwise obtain the additional capital we need, we may not be able to finance the expenditures necessary to conduct our operations or to make acquisitions. If we decide to incur additional debt or to sell or issue additional equity to finance our operations or acquisitions, any such decision could result in additional expenses, the entry into debt agreements with covenants that limit our operational or financial flexibility or additional dilution to our shareholders. Furthermore, we believe that our existing cash balances, cash flows from our operations, and borrowings under our new Revolving Facility will be sufficient to fund our
105
Table of Contents
operations beyond the next twelve months. Any shortfalls in capital will be funded through the proceeds from this offering, or through the incurrence of additional debt.
Revolving Facility
In 2020, the Company and certain of its subsidiaries entered into a revolving credit agreement with Pinnacle Bank (the “Revolving Credit Agreement”), as amended from time to time. The Revolving Credit Agreement is secured by a first-priority lien on substantially all assets of the Company and its subsidiaries. Borrowings under the Revolving Credit Agreement bear interest at a floating rate based on the Prime Rate, subject to a floor. The agreement contains customary affirmative and negative covenants, including restrictions on indebtedness, liens, investments, affiliate transactions, mergers and asset sales, and restricted payments, as well as financial reporting requirements. The agreement also includes financial covenants requiring compliance with a maximum total net leverage ratio and a minimum liquidity threshold, each as defined in the agreement.
In March 2026, the Company entered into an amendment to the Revolving Credit Facility that extended the maturity date from June 30, 2026, to June 30, 2027, and increased the total commitments to $60.0 million. The amendment also revised the interest rate from a Prime Rate-based structure to a Term SOFR-based structure, plus an applicable margin. The amended agreement continues to be secured by substantially all assets of the Company and includes customary financial and non-financial covenants, including a maximum net leverage ratio and minimum liquidity requirement.
As of June 30, 2026, the Company had no revolving borrowings outstanding under the Revolving Credit Agreement, $4.7 million of letters of credit outstanding, and $55.3 million of remaining availability thereunder. As of December 31, 2025, the Company had no revolving borrowings outstanding, $10.2 million of letters of credit outstanding, and $19.8 million of remaining availability. The outstanding letters of credit expire at various dates during 2026.
The Company was in compliance with all financial and non-financial covenants as of June 30, 2026. The Company expects to enter into a new senior secured revolving credit facility (the “New Credit Facility”), which is expected to replace the existing Revolving Credit Agreement. The terms of the New Credit Facility are currently being negotiated and are expected to provide for increased commitments and contain customary covenants and other terms appropriate for the Company as a publicly traded entity. We expect to finalize the New Credit Facility prior to or concurrently with the closing of this offering.
Contractual Obligations
Significant contractual obligations were primarily comprised of lease commitments. As of June 30, 2026, we had $4.0 million and $1.8 million of long-term and short-term lease obligations, respectively, outstanding. As of December 31, 2025, we had $3.5 million and $1.8 million of long-term and short-term lease obligations, respectively, outstanding.
Cash Flows
The following tables present a summary of our consolidated statements of cash flows for the six months ended June 2026, and 2025, and for the years ended December 31, 2025 and 2024 (dollar amounts in thousands):
| Six Months Ended June 30, |
||||||||
| 2026 | 2025 | |||||||
| Net cash provided by (used in) operating activities |
$ | 6,269 | $ | (7,417 | ) | |||
| Net cash used in investing activities |
(463 | ) | (193 | ) | ||||
| Net cash used in financing activities |
(32,954 | ) | (2,153 | ) | ||||
106
Table of Contents
Operating activities
Net cash flow provided by operating activities for the six months ended June 30, 2026, was a net cash inflow of $6.3 million, an increase of $13.7 million as compared to a net cash outflow of $7.4 million for the six months ended June 30, 2025. This increase was primarily driven by reduced cash outflows due to the timing of billings and payments to vendors partially offset by reduced cash inflows relating to increased outstanding receivables due to timing of collections on receivables from customers.
Investing activities
Net cash flow used in investing activities for the six months ended June 30, 2026, was a net cash outflow of $0.5 million, an increase of $0.3 million as compared to a net cash outflow of $0.2 million for the six months ended June 30, 2025. This increase was primarily driven by an increase in purchases of property and equipment.
Financing activities
Net cash flow used in financing activities for the six months ended June 30, 2026, was a net cash outflow of $33 million, an increase of $30.8 million as compared to a net cash outflow of $2.2 million for the six months ended June 30, 2025. This increase was primarily driven by distributions of $32.0 million to the Parent, with no similar activity for the six months ended June 30, 2025.
Year Ended December 31, 2025 Compared to Year Ended December 31, 2024
| Year Ended December 31, |
||||||||
| 2025 | 2024 | |||||||
| Net cash provided by operating activities |
$ | 78,136 | $ | 72,297 | ||||
| Net cash used in investing activities |
(346 | ) | (62 | ) | ||||
| Net cash used in financing activities |
(11,464 | ) | (43,270 | ) | ||||
Operating activities
Net cash flow provided by operating activities for the year ended December 31, 2025, was a net cash inflow of $78.1 million, an increase of $5.8 million as compared to a net cash inflow of $72.3 million for the year ended December 31, 2024. This increase was primarily driven by an increase in activity on new and existing construction projects with customers.
Investing activities
Net cash flow used in investing activities for the year ended December 31, 2025, was a net cash outflow of $0.3 million, an increase of $0.2 million as compared to a net cash outflow of $0.1 million for the year ended December 31, 2024. This increase was primarily driven by a reduction in proceeds from sale of property and equipment as compared to the prior year, partially offset by an increase in purchases of property and equipment.
Financing activities
Net cash flow used in financing activities for the year ended December 31, 2025, was a net cash outflow of $11.5 million, a decrease of $31.8 million as compared to a net cash outflow of $43.3 million for the year ended
107
Table of Contents
December 31, 2024. This decrease was primarily driven by a $40.1 million decrease of net repayment on the revolving credit facility, as the Company had no borrowings outstanding during the year ended December 31, 2025. Partially offsetting this decrease in financing outflow was a $6.0 million increase in member distributions, $2.1 million increase of class B unit repurchases, and a $0.6 million increase in payments on finance lease liabilities.
Key Performance Indicators and Non-GAAP Financial Measures
In managing our business and assessing financial performance, we supplement the information provided by the consolidated financial statements with other financial and operating metrics. These operating metrics are utilized by our management to evaluate our business performance, identify trends affecting our business and facilitate long-term strategic planning.
Backlog
We use backlog to forecast our future capital needs and to identify future operating trends that may not otherwise be apparent. Backlog is a measure commonly used in our industry but not recognized under GAAP. We believe this measure enables management to more effectively forecast our future revenue and identify future operating trends that may not otherwise be apparent. We believe this measure is also useful for investors in forecasting our future results and comparing us to our competitors. Our methodology for determining backlog may not be comparable to the methodologies used by other companies.
EBITDA and Adjusted EBITDA
In addition to financial measures determined in accordance with GAAP, we consider a variety of financial measures in assessing the performance of our business. The key non-GAAP measures we use are EBITDA and Adjusted EBITDA.
EBITDA represents net income (loss) attributable to controlling interest before interest, income taxes, depreciation and amortization. Adjusted EBITDA is defined as EBITDA adjusted to exclude: (i) Non-cash compensation; (ii) severance, retention and recruiting costs, (iii) costs associated with our organizational transformation, (iv) legal settlements and (v) costs to prepare for this offering.
We adjust for these items in our Adjusted EBITDA as our management believes these items would distort from their ability to efficiently view and assess core operating trends.
In December 2023, the current Sponsor Group acquired a controlling interest in the Company (the “2023 Transaction”). Following the 2023 Transaction, the Company undertook a defined leadership transition, organizational review, and related transformation initiatives. The prior Chief Executive Officer, President and Chairman of the Board were separated from the Company in September 2024, and new Chief Executive Officer and Chief Financial Officer leadership were appointed in October 2024, after which the Company completed a targeted senior leadership rebuild and transition plan. The management transition and organizational transformation resulted in discrete, non-recurring costs that are not reflective of the Company’s ongoing operating cost structure. In 2024, these costs primarily consisted of $3.0 million for executive and operational advisory services retained during the change-of-control transition period, $2.4 million for transitional accounting advisory support. In 2025, these costs primarily consisted of $2.9 million for discrete strategic and operational advisory engagements completed under the new leadership team, $2.6 million for transformation initiatives related to future-state organizational assessment and design, initial compliance infrastructure buildout, and enterprise digital transformation, and $0.9 million relating to the conclusion of the transitional accounting advisory engagement. In the six months ended June 30, 2026, these costs primarily consisted of
108
Table of Contents
$0.7 million for discrete strategic advisory engagements and $0.8 million for transformation initiatives related to the continued implementation of future-state organizational design, compliance infrastructure and enterprise digital transformation initiatives. The Company expects these activities to be completed by the end of 2026, and does not expect these costs to recur as part of its normal operating cost structure thereafter.
Our presentation of EBITDA and Adjusted EBITDA should not be construed to imply that our future results will be unaffected by these items. We present EBITDA and Adjusted EBITDA because we believe they provide a more complete understanding of the factors and trends affecting our business than GAAP measures alone. Our board of directors, management and investors use EBITDA and Adjusted EBITDA to assess our financial performance because such measures allow them to compare our operating performance on a consistent basis across periods by removing the effects of our capital structure (such as varying levels of interest expense), asset base (such as depreciation and amortization) and items outside the control of our management team (such as income taxes).
EBITDA and Adjusted EBITDA are not defined under GAAP. Our use of the terms EBITDA and Adjusted EBITDA may not be comparable to similarly titled measures of other companies in our industry and are not measures of performance calculated in accordance with GAAP. Our presentation of EBITDA and Adjusted EBITDA are intended as supplemental measures of our performance that are not required by, or presented in accordance with, GAAP. EBITDA and Adjusted EBITDA should not be considered as alternatives to operating income (loss), net income (loss), earnings per share, revenue, net income margin or any other performance measures derived in accordance with GAAP, or as measures of operating cash flows or liquidity.
EBITDA and Adjusted EBITDA have important limitations as analytical tools, and such measures should not be considered either in isolation or as a substitute for analyzing our results as reported under GAAP. Some of these limitations include:
| • | EBITDA and Adjusted EBITDA do not reflect our interest expense or the cash requirements necessary to service interest or principal payments on our debt; |
| • | EBITDA and Adjusted EBITDA do not reflect our tax expenses or the cash requirements to pay our taxes; |
| • | Although depreciation and amortization are non-cash charges, the assets being depreciated and amortized will often have to be replaced in the future, and EBITDA and Adjusted EBITDA do not reflect any cash requirements for such replacements; and |
| • | Other companies in our industry may calculate EBITDA and Adjusted EBITDA differently, limiting their usefulness as comparative measures. |
In evaluating EBITDA and Adjusted EBITDA, you should be aware that in the future we may incur expenses similar to those eliminated in this prospectus.
Critical Accounting Estimates
We prepare our consolidated financial statements in accordance with GAAP. There are certain accounting principles that require management to make judgments and estimates regarding matters that are uncertain and susceptible to change. Critical accounting estimates are defined as those that are reflective of significant judgments and uncertainties, which could potentially result in materially different results under different assumptions and conditions. Management regularly reviews the estimates and assumptions used in the preparation of the financial statements for reasonableness and adequacy. Our estimates are based on historical experience, current conditions and various other assumptions that we believe to be reasonable under the circumstances. Actual results may differ from these estimates and assumptions. To the extent that there are differences between estimates and actual results, our future financial statement presentation, financial condition, results of operations and cash flows may be affected.
109
Table of Contents
The following discussion pertains to accounting estimates we believe are most critical to the portrayal of our financial condition and results of operations and that require significant, difficult, subjective or complex judgments or estimates. Other companies in similar businesses may use different estimation policies and methodologies, which may affect the comparability of our financial statements, financial condition, results of operations and cash flows to those of other companies.
Revenue Recognition
We recognize revenue from contracts with customers when, or as, control of the promised services and goods is transferred to the customers. The amount of revenue recognized reflects the consideration to which we expect to be entitled in exchange for the services and goods transferred.
Refer to Revenue Recognition in Note 2 of the Notes to the Consolidated Financial Statements for further description of the factors that can cause changes in estimates and how changes in estimates on certain contracts may result in the issuance of change orders or claims under contracts for our projects.
We derive revenue primarily from contracts for specific projects requiring the construction and installation of an entire infrastructure system, or specified units within an infrastructure system. We primarily recognize revenue over time utilizing the percentage-of-completion measure of progress, which best depicts the continuous transfer of control of services to the customer, and accordingly, when performance obligations are satisfied for the related contracts.
Goodwill
We have goodwill that has been recorded in connection with our acquisitions of businesses. Goodwill represents the excess of amounts paid over the fair value of net assets acquired. Goodwill is not amortized but instead is tested for impairment at least annually as of December 31, or more frequently if triggering events occur. Goodwill is required to be tested at the reporting unit level.
We assess goodwill using either a qualitative or quantitative approach to determine whether it is more likely than not that the fair value of a reporting unit is less than its carrying value. The qualitative assessment considers enterprise value, macroeconomic conditions, cost factors, and other industry and market conditions. If it is determined, based upon a qualitative assessment, that it is more likely than not that the reporting unit’s fair value is less than its carrying amount, then a quantitative impairment test is performed. The quantitative assessment estimates the fair value of the reporting unit using income and market approaches and compares that amount to the carrying value of that reporting unit. In the event the fair value of the reporting unit is determined to be less than the carrying value, an impairment charge is recognized equal to the excess, limited to the total amount of goodwill allocated to the reporting unit.
We completed our 2025 annual goodwill impairment test as of December 31, 2025 and determined, based on a qualitative assessment, that no goodwill impairment charge was required. No qualitative factors were present that indicated impairment of the reporting unit. Changes in facts and circumstances, judgments and assumptions used to determine these fair values, including with respect to market conditions and the economy, could result in impairment charges in the future that could be material to our financial statements.
Unit-Based Compensation
The Company accounts for equity grants to employees as unit-based compensation under ASC 718, Compensation-Stock Compensation. These awards are issued by the Company’s ultimate parent and represent equity interests in the ultimate parent. Unit-based compensation cost is measured at the grant date fair value
110
Table of Contents
and is recognized on a straight-line basis over the requisite service period, including those units with graded vesting, with a corresponding credit to additional paid-in capital as a capital contribution from Ultimate Parent. However, the amount of unit-based compensation at any date is equal to the portion of the grant date value of the award that is vested.
Equity grants issued to employees are measured at fair value on the grant date using an option pricing model. The Company utilizes the estimated weighted average of the Company’s expected life dependent on various exit scenarios to estimate the expected term of the awards. Expected volatility is based on the average of historical and implied volatility of a set of comparable companies, adjusted for size and leverage. The risk-free rates are based on the yields of U.S. Treasury instruments with comparable terms. Actual results may vary depending on the assumptions applied within the model.
Recent Accounting Pronouncements
See Note 3—New Accounting Pronouncements to CoVolt Holdings Group, LLC and subsidiaries’ unaudited condensed consolidated financial statements for the period ending June 30, 2026, included elsewhere in this Registration Statement for information regarding new accounting pronouncements.
Quantitative and Qualitative Disclosures About Market Risk
We are exposed to market risk in the ordinary course of business. Market risk represents the risk of loss that may impact our financial position due to adverse changes in financial market prices and rates. Our market risk exposure is primarily a result of exposure to potential changes in interest rates or inflation and the resulting impact on investment income and interest expense. We do not hold financial instruments for trading purposes.
Interest Rate Risk
Our results of operations are subject to risk from interest rate fluctuations on borrowings under our Credit Facilities, which carry variable interest rates. Because our borrowings bear interest at a variable rate, we are exposed to market risks relating to changes in interest rates. As of December 31, 2025, we had no borrowings outstanding and thus are not exposed to risks associated with variable interest debt. We are also exposed to interest rate risk associated with our balances of cash and cash equivalents.
Inflation Risk
Inflation can have an impact on our contract costs and our operating costs. A prolonged period of inflation could cause interest rates, fuel, wages, and other costs to increase, which would adversely affect our results of operations unless our corresponding contract revenues correspondingly increase. However, we do not believe that inflation has had a material effect on our business, financial condition or results of operations. If our costs were to become subject to significant inflationary pressures, we may not be able to fully offset such higher costs through price increases. Our inability or failure to do so could have a material adverse effect on our business, financial condition and results of operations.
111
Table of Contents
Table of Contents
Our Company
We are a leading provider of engineering, procurement, and construction services to the power and data center industries. We specialize in building utility-scale solar projects, battery energy storage systems and high-voltage transmission and distribution infrastructure. Since our founding in 2005, we have built more than 7.3 GWac of generation, nearly 1.7 GWh of battery storage and T&D infrastructure that connected over 26.4 GW of capacity and load to the grid. We are recognized as a top 10 utility-scale solar builder based on installations from 2015 to 2025 according to Solar Power World.
Demand for our services is growing rapidly as independent power producers add new generation to satisfy rising electricity demand, utilities upgrade and expand transmission and distribution infrastructure to support rapid load growth, and data center operators build more energy-intensive facilities. For the year ended December 31, 2025, our revenues grew 67% to $739.4 million compared to the year ended December 31, 2024 and, as of June 30, 2026, we had $3.6 billion of backlog representing an increase of 410% compared to the same date in the prior year. 85%, 13% and 2% was related to generation, T&D projects and energy storage, respectively. Our revenue in future periods may differ from the amounts in our backlog due to contract changes or terminations and other factors. See “Management’s Discussion and Analysis of Financial Condition and Results of Operations–Backlog” for a discussion of our backlog.
Our customers include IPPs, project developers, utilities, industrial facilities and data center operators. Since 2021, we have completed projects for 14 of the top 20 solar IPPs in the U.S. We seek to partner closely with our customers by engaging with them during the planning phases of their projects. By engaging early in project design, we help identify value engineering opportunities that benefit both our customers and us, as well as make it more difficult for competitors that are less familiar with the projects to displace us.
Our projects are typically executed over 12 to 18 months pursuant to one or more LNTP agreements followed by a lump sum EPC contract. Under LNTP agreements, our customers pay us to perform initial engineering and site investigation work, procure long lead time equipment and begin initial mobilization of our workforce and equipment, the results of which we use to refine our price to construct the project. This structure reduces our risk by allowing us to learn more about the site conditions, reduce estimating assumptions and more accurately forecast our costs prior to entering into an EPC contract, and it benefits our customers by reducing change orders and schedule disruptions during construction.
We are headquartered in Houston, Texas. As of June 30, 2026, we employed approximately 345 professionals and 757 trade and craft employees.
Our Market Opportunity
Demand for our services is driven primarily by investment in utility-scale solar projects, battery energy storage projects and transmission and distribution infrastructure, particularly substations. Annual investment in utility-scale solar and battery energy storage projects over 200 MWdc is forecast to grow from $28.5 billion in 2026 to $41.9 billion in 2031, representing a compound annual growth rate of 8.0%, according to Wood Mackenzie. Annual investment in T&D infrastructure is forecast to grow from $149.7 billion in 2026 to $218.5 billion in 2031, representing a compound annual growth rate of 7.9%, according to Wood Mackenzie. We believe key drivers of growing investment in these areas include:
| • | Step-change load growth—driven by data centers and U.S. reshoring—that is creating an urgent need for new generation. According to Wood Mackenzie and the EIA, U.S. electricity consumption is expected to grow |
113
Table of Contents
| 36.9% from 2026 to 2036 which compares with only 17.0% over the prior ten-year period from 2016 to 2026. The acceleration reflects growing investment in new, larger data centers, the reshoring of energy-intensive manufacturing, higher HVAC demand amid more extreme temperatures, and broader electrification of commercial and industrial processes. The urgent need for new generation is underscored by declining operating reserve margins—the buffer of available generation capacity above expected peak demand. NERC currently classifies the ERCOT, MISO, PJM and portions of WECC interconnections, which represent over 50% of electricity demand in the U.S., as having “high risk” of energy shortfalls that exceed resource adequacy targets during the period from 2026 to 2030. Wood Mackenzie forecasts that an average of 49 GWac of new solar and storage projects will be built annually during the period from 2027 to 2036, an increase of 2.2x compared to the average over the prior ten year period, and representing nearly 64% of all new generation capacity expected to be built over the period. |
| • | Outsized growth in generation and large-load interconnections that is fueling demand for more substations. New power plants, battery energy storage systems, data centers and industrial facilities require an interconnection to the grid. Each interconnection typically requires new or upgraded substations, protection and controls, and, in many cases, incremental transmission and distribution capacity. Outsized growth in both new generation and large-load projects is driving a sharp increase in the number of grid interconnections. Utilities and system operators are being asked to connect record volumes of utility-scale solar, battery storage, and other generation resources while data centers and reshored industrial facilities are adding large, concentrated loads. According to Wood Mackenzie, the total capacity of interconnection requests has increased more than three-fold over the past 10 years from 2015 to 2025. |
| • | Proliferation of on-site generation and battery storage for large users. Data centers and large industrial facilities are increasingly adding on-site generation and battery storage to secure capacity, improve resiliency, and reduce exposure to utility interconnection delays and grid constraints. These behind-the-meter systems provide firm power for peak demand, contingency events, and planned maintenance, while battery storage can also smooth load, manage demand charges, and support rapid ramping requirements. As power availability becomes a gating factor for new capacity, on-site generation and battery energy storage are becoming core components of many new data centers and industrial facilities—driving incremental demand for EPC services to engineer and integrate complex, site-specific systems, execute civil and electrical construction, and provide commissioning and compliance services. |
| • | Solar energy’s faster time-to-power and shorter equipment lead times compared to other forms of generation. Utility-scale solar projects can be delivered in 18 months or less, compared to approximately three to four years for new natural gas plants and ten years for new nuclear plants, according to Wood Mackenzie. Lead times for gas-fired generation may also extend further given reported multi-year OEM order backlogs—for example, new gas turbine lead times can exceed six years, while key solar components such as modules, trackers, and inverters are typically available in under ten months, according to Wood Mackenzie. Solar’s faster time-to-power makes solar an attractive solution for adding capacity quickly in regions experiencing rapid load growth. |
| • | Solar’s lower levelized cost of energy compared to other forms of generation both with and without ITCs. Wood Mackenzie estimates that the levelized cost of energy for utility-scale solar with trackers including the investment tax credit (“ITC”); utility-scale solar with trackers excluding the ITC; and hybrids including the ITC for the battery storage system is $54.62, $70.70 and $74.70 per MWh, respectively, which compares with $120.65 per MWh for gas combined cycle gas turbines. Solar energy’s lower levelized cost of energy combined with its lack of greenhouse gas emissions make it an attractive source of new generation capacity to utilities, corporations and the public when compared to new gas-fired generation. The falling cost of battery storage and the rising cost of new natural gas-fired power plants is also making it possible for solar to compete with natural gas as economical base load generation in certain areas of the United States. |
114
Table of Contents
| • | Corporate offtakers’ continued preference for carbon-free power. According to Wood Mackenzie, 64% of power purchase agreements in the United States for projects that came online in 2025 were signed with corporate offtakers and 89% of those PPAs were with wind and solar projects. Data center offtakers who are expected to account for approximately 67% of the increase in electricity consumption from 2026 to 2036, prefer carbon-free power which is underscored by the commitments of top 10 data center owners to use 100% carbon-free power, according to Wood Mackenzie. |
| • | Rapid deployment of battery storage driven by expanding use cases. Energy storage deployments are being driven by the need for grid stability, backup power for data centers, peak demand management and the ability to create baseload power from solar energy and battery storage. Rising power prices and falling system costs have enabled broader adoption of battery storage systems. According to Wood Mackenzie, annual utility-scale battery storage installations will nearly double from 60.0 GWh in 2026 to 119.0 GWh in 2036. |
| • | Confluence of load growth and aging infrastructure boosting T&D investment. U.S. grid infrastructure is under increasing strain as electrification, data centers, and solar energy and battery storage drive rapid load growth and a surge in interconnection activity. At the same time, the installed base of T&D equipment is aging rapidly—T&D equipment used in the grid typically have a useful life of 25 to 40 years. According to NREL and ASCE, the majority of in-service T&D equipment used in the grid is more than 30 years old. The combination of rising demand, growing interconnection volumes, and aging infrastructure is driving increasing investment by utilities in transmission and distribution infrastructure. According to the Edison Electric Institute, utility spending on T&D infrastructure has increased every year since 2010. |
Our Strengths
We believe the following strengths of our business position us to grow faster than the markets we operate in and distinguish us from our peers:
| • | Proven operator with a longstanding market presence. We have been continuously constructing utility-scale solar projects, battery energy storage systems and high-voltage substations for more than two decades. Since our founding in 2005, we have built more than 7.3 GWac of generation, nearly 1.7 GWh of battery storage and T&D infrastructure that connected over 26.4 GW of capacity and load to the grid. We are recognized as a top 10 utility-scale solar builder based on installations from 2015 to 2025 according to Solar Power World. We believe our long operating history, scale and market leadership provide meaningful advantages versus smaller, less-established competitors, including: |
| • | Increased customer confidence in our financial capacity and operational capability to execute large, complex projects; |
| • | “Bankable” standing with customers’ lenders, supporting more favorable financing outcomes for our customers; |
| • | Deeper experience and project data to price-in risk accurately and bid with discipline; |
| • | Greater purchasing power and preferential terms with suppliers; |
| • | Preferred access to long lead, critical-path equipment such as transformers and circuit breakers; |
| • | Enhanced ability to recruit and retain top field and management talent; and |
| • | Exclusive means and methods developed over millions of hours of project execution experience. |
115
Table of Contents
| • | Direct beneficiary of accelerating load growth and the retirement of fossil generation. The consumption of power in the United States is forecast to grow 36.9% from 2026 through 2036 which compares with only 17.0% over the prior 10-year period from 2016 to 2026 according to Wood Mackenzie and the EIA. At the same time, more than 13% of the existing generation fleet in the United States as of year-end 2025 is slated to be retired from 2026 through 2035 according to Wood Mackenzie. The combination of growing demand for power coupled with the large number of fossil generation retirements has created increasing demand for new generation capacity. According to Wood Mackenzie, a total of 486 GWac of solar and storage capacity will be constructed in the U.S. from 2027 to 2036, representing nearly 64% of all new generation constructed over the period. We believe these structural tailwinds—higher demand, supply attrition, and a build mix increasingly weighted toward solar and storage—will translate into sustained, growing demand for our services. |
| • | Self-perform model supported by extensive engineering, mechanical and electrical capabilities. We have the capability to self-perform all of the electrical and mechanical scopes of work and certain civil scopes of work for our customers’ projects. We self-performed over 90% of projects that commenced construction in 2025 with fully self-performed scopes. The level of self-performance varies by project based on project-specific requirements and our execution strategy. By relying on our own trained crews, standardized processes, and a dedicated equipment fleet, we can better control safety, scheduling, quality, and productivity in the field. We believe our self-perform approach enables us to capture more margin while reducing execution risk and schedule variability that can arise from dependence on third-party subcontractors, particularly in tight labor markets or remote project locations. We also leverage our front-end engineering capability to help us identify and mitigate design, permitting, procurement, and constructability risks before mobilization, supporting more predictable schedules and tighter cost control. |
| • | Scale and capabilities to execute large, complex projects. Utility-scale solar and storage projects continue to increase in size and complexity, with Wood Mackenzie forecasting that 73% and 47% of utility-scale solar projects built between 2026 and 2036 will exceed 200 MWdc and include battery storage, respectively. We believe only a limited number of contractors have a proven track record delivering projects at this scale. The average capacity of utility-scale solar and solar-plus-storage hybrid projects that we completed in 2025 was approximately 232 MWdc, positioning us as one of a small handful of contractors with consistent experience executing large, complex builds. |
| • | Dedicated in-house high-voltage platform whose capabilities are needed by a wide range of industries, including data centers, power generation, energy-intensive manufacturing and utilities. We maintain a dedicated, in-house high-voltage team focused on substation, switchyard and interconnection work for both generation projects and large-load customers. High-voltage work is highly technical, tightly regulated, and safety-intensive, and there are a limited number of qualified personnel. By self-performing this work, we enhance schedule and quality control, reduce reliance on third-party subcontractors at a key project interface, and improve overall project certainty for customers. Importantly, our high-voltage platform supports greater cost certainty and higher margins on our own projects as well as enables us to pursue third-party substation and interconnection awards, expanding our addressable market. |
| • | In-house engineering capabilities that accelerate time-to-power for customers and increase our margins. We have in-house engineering capabilities, including certified professional engineers. Unlike some of our competitors, we are able to act as the engineer of record and provide our customers with stamped issued for construction (“IFC”) drawings. We believe this in-house engineer of record (“EOR”) capability enables faster execution by reducing our reliance on third-party engineering approvals and improving design-to-field coordination, while also allowing us to capture additional margin through integrated design and delivery. |
116
Table of Contents
| • | Repeat customer relationships that provide revenue predictability. We have built long-term relationships with leading independent power producers, utilities and data center operators. We generated 93% of our 2025 revenues from customers we had served in the prior three years, and our average relationship tenure with our top 25 customers is approximately seven years. These longstanding relationships give us greater visibility into future work, reduce sales and marketing costs, and make it challenging for our competitors to displace us. Our high rate of repeat business also demonstrates customer satisfaction with our execution capabilities. |
| • | Differentiated labor engagement model that supports rapid scaling. Like most contractors, we flex field labor by region based on project activity. We utilize a direct-hire model for our craftworkers which we believe drives higher quality workmanship, improved retention and more consistent project execution. A key differentiator in our approach to craft labor is the ability to mobilize skilled crews rapidly, across multiple states and on short notice, which is essential for schedule-driven projects in tight labor markets. We support that capability through an extensive and actively curated database of more than 5,000 qualified craftworkers and technicians that is continuously expanded by our dedicated craft recruiting team. We use workforce management tools to track labor availability and project requirements, enabling faster mobilization, more predictable staffing and the ability to execute multiple concurrent projects across geographies without reliance on any single local labor pool. |
| • | Dedicated apprenticeship program that strengthens our ability to attract, train, and retain labor while helping customers qualify for tax credits. We operate a Department of Labor–approved Registered Apprenticeship Program under the National Apprenticeship Act. The program helps us to attract new workers by offering participants trade-school-equivalent training, delivered by our personnel, at no cost while they earn an hourly wage. Additionally, our registered status enables our customers to satisfy federal investment tax credit labor requirements, which typically require that a specified portion of construction hours (at least 15%) be performed by registered apprentices. We believe we are among a limited number of EPCs with this capability, allowing customers to meet apprenticeship thresholds more reliably and reducing the administrative burden of sourcing apprentices and managing related compliance tracking that would otherwise fall on their teams. We also have established processes and controls to support compliance with prevailing wage requirements, which we believe enhances execution reliability and is a critical consideration for customers seeking to maximize available tax incentives. |
| • | Comprehensive, data-driven risk management that supports superior project performance. In 2022, we began implementing a coordinated set of risk management policies and procedures designed to improve job margins and reduce earnings volatility. Core elements include a bid/no-bid committee that evaluates all prospective projects for viability and attractiveness; a requirement that no firm bids are submitted unless a senior leader has physically walked the site; board approval for projects above a defined size threshold; and bi-weekly CFO-led project reviews that assess detailed project-level KPIs, including cost performance, schedule adherence and identified risks with associated mitigation plans. We also prepare a detailed risk register for every bid as part of the estimating process, no bid is submitted until subject matter experts have reviewed the risk register and developed a mitigation plan, which can include specific contract revisions, pricing additional resources and assessing additional contingency. All of the projects that reached substantial completion in 2025 exceeded initial bid margins by at least 250 bps. This demonstrates the effectiveness of our risk management practices and a more rigorous project oversight and management framework, resulting in margin predictability and consistency. |
| • | Project controls personnel report to the Chief Financial Officer not project management. In our industry, project controls personnel are typically responsible for tracking, validating, and reporting project schedules, forecasts and costs, including commitments, invoices, labor, and change orders. While many contractors structure this function to report directly to project managers, we deliberately have our project controls personnel report to our Chief Financial Officer. This reporting line reinforces independence and |
117
Table of Contents
| accountability, ensures consistent application of cost-control standards across all projects, and strengthens oversight of budget-to-actual performance. We believe with direct CFO visibility, variances are identified and escalated more quickly, enabling earlier corrective action, whether through tighter cost controls, updated forecasts, change-order recovery, or resource adjustments, before issues compound and more significantly impact overall project profitability. |
| • | Business model designed to support strong free cash flow generation. Our contract structure is designed to align customer payments with our procurement and construction activities, including customer deposits on long-lead equipment, materials funded by customers prior to procurement, and monthly progress payments throughout the construction period. This structure minimizes our working capital requirements and reduces credit risk. Combined with modest capital expenditure requirements as a percentage of revenue, we believe our model enables us to convert the majority of our Adjusted EBITDA to Free Cash Flow, which we define as operating cash flow less capital expenditures. For the 12 months ended June 30, 2026, net cash provided by operating activities was $91.8 million and capital expenditures were $0.9 million; accordingly, Free Cash Flow was $90.9 million, representing 130% of our Adjusted EBITDA. We believe our ability to generate significant Free Cash Flow coupled with our low leverage gives us the financial flexibility to invest in growth opportunities, fund equipment purchases, and manage through industry cycles without needing to rely on significant external capital. For additional discussion of our Adjusted EBITDA and Free Cash Flow, which are not measures calculated in accordance with GAAP, and for a reconciliation of these measures for the six months ended June 30, 2026, see “Management’s Discussion and Analysis of Financial Condition and Results of Operations–Non-GAAP Financial Measures” elsewhere in this prospectus. |
| • | Safety-first culture with industry-leading results. Safety is the foundation of our operations and a core value embedded throughout our organization. We use data-driven safety management, integrating leading indicators, near-miss reporting, and real-time field observations, to identify emerging patterns early and proactively mitigate risks before they become incidents. In 2025, our Total Recordable Incident Rate (“TRIR”) was 0.66 and our Lost Time Incident Rate (“LTIR”) was 0.07, versus Bureau of Labor Statistics industry averages of 1.5 and 0.4 for the power and communication line and related structures construction industry, respectively, placing our TRIR at approximately 56% better than the industry benchmark. We believe our safety track record is a competitive differentiator: it qualifies us for safety-gated projects, supports lower insurance and claims costs, and reduces the risk of schedule disruption and productivity losses associated with workplace incidents. We received the National Safety Council Occupational Excellence Achievement Award in each of 2023, 2024 and 2025 and achieved over five million work hours without a lost-time injury. |
| • | Seasoned leadership team with tight financial-operational integration. Our leadership team averages more than 20 years of experience in the construction and power industries, including oversight of multi-billion-dollar EPC and power generation project portfolios. We also position our finance team as a strategic partner to the field, providing rigorous cost visibility, disciplined forecasting, and timely decision support, so each project is executed with fiscal discipline and high operational accountability for financial results. We believe this combination of seasoned leadership and tight financial-operational integration drives consistent delivery and equips us to successfully execute increasingly large and complex projects at attractive margins. |
Our Growth Strategy
We intend to continue growing our business by:
| • | Capitalizing on the shrinking pool of EPCs capable of executing large-scale projects to grow our market share. Utility-scale projects are becoming larger and more complex as electricity demand rises and interconnection capacity becomes increasingly constrained, pushing developers and IPPs toward larger, more capital-intensive builds. According to the EIA, the average size of a utility-scale solar project has more |
118
Table of Contents
| than tripled from 2021 to 2026 with a corresponding increase in construction budgets. Wood Mackenzie expects projects above 200 MWdc to grow at a 6.5% CAGR from 2026–2031, compared with negative 6.3% for projects below 200 MWdc. Against this backdrop, we believe we are among a limited set of EPCs with the scale, systems, and financial capacity to reliably deliver projects greater than 200 MWdc. As project sizes continue to grow, we expect customers to consolidate awards with proven contractors that can manage complexity, supply chain and logistics, schedule risk, and balance-sheet requirements, creating a structural advantage for established EPCs and an opportunity for us to capture incremental share. |
| • | Capturing a larger share of fast-growing data center construction spending. As of June 30, 2026, we had approximately $225 million of backlog with data center customers, all related to high-voltage substation work. Our strategy is to continue growing our core high-voltage offering while selectively expanding into adjacent scopes, such as transmission lines, medium voltage distribution systems, and integration of on-site generation, where we can leverage existing capabilities to become a more comprehensive delivery partner for data center developers while maintaining disciplined risk selection. We believe the data center market is supported by favorable demand trends. Wood Mackenzie projects U.S. data center construction spending, excluding compute, will more than double from $93 billion in 2026 to $222 billion in 2031. |
| • | Expanding our civil self-perform capabilities to increase margins and reduce execution risk. Today, we typically self-perform certain civil work, including pile foundation and structural posts as well as trenching for medium-voltage cable, and based on the size, layout, and geological attributes of the specific site, we sometimes self-perform the earthwork and grading, including building and installing access roads, and retention ponds. We use subcontractors for other specialty civil work, such as clearing and grubbing or directional drilling and boring. We intend to selectively expand our civil self-perform capabilities where we can capture meaningful additional margin by reducing our use of subcontractors. Civil work is also frequently the primary source of project delays and execution risk, and we believe further expanding our in-house capability will allow us to better manage construction schedules, coordination and cost. |
| • | Growing our high voltage T&D business with utilities. Utilities are large buyers of high voltage services to expand, harden, and modernize their transmission and distribution systems. According to Wood Mackenzie, utilities invested $135 billion in transmission and distribution in 2025. Historically, we generated less than 2% of our high voltage revenues from utility customers. We intend to increase our high voltage revenues by intensifying our sales efforts on utilities that have infrastructure in the geographies where we operate. |
| • | Further expanding our in-house engineering capabilities. We intend to further grow our in-house engineering resources across the areas of civil, structural and electrical design. Expanding our in-house engineering capabilities enables earlier engagement with customers, shorter design cycles, and improved constructability through tighter design-to-construction coordination. Over time, we expect this to drive higher win rates, capture incremental margin by reducing reliance on third parties, and strengthen project execution through fewer design changes, clearer scope definition, and improved schedule and cost certainty. |
| • | Leveraging technology and innovation to improve construction efficiency and reduce costs. We are evaluating and piloting technology solutions to improve margins, construction quality and project safety. Our innovation efforts focus on digital technologies, drones, robotics and artificial intelligence applications across the design and construction lifecycle. Areas we are currently exploring include deploying robotic systems to install heavy components, automating manual steps in the construction workflow, reducing safety risk; creating automated processes, improving the amount of output we can create; and using drones for quantity verification, quality assurance and geographic scoping. We believe our focus on construction innovation positions us to deliver greater profitability than our peers as projects increase in size and complexity. |
| • | Pursuing strategic acquisitions that increase our scale, broaden our customer base and expand our addressable market. We intend to selectively pursue acquisitions of complementary businesses that |
119
Table of Contents
| accelerate our strategic objectives, including regional contractors in geographies where we have limited presence; specialized T&D contractors with high-voltage capabilities and utility relationships; companies with expertise in distributed gas generation; providers of O&M services for solar and battery energy storage projects; and construction firms who specialize in building data centers. We believe the infrastructure services market is fragmented with numerous small-to-midsize contractors, creating a robust pipeline of potential targets. We believe our scale, unlevered balance sheet, access to public equity capital following our IPO and proven ability to integrate businesses position us to be a consolidator in our industry. |
Our Services
We provide a comprehensive suite of services for utility-scale solar projects, battery energy storage systems and high-voltage transmission and distribution infrastructure. Our service offering is designed to de-risk project delivery for customers by integrating front-end engineering and design with procurement, construction and commissioning. We operate as an integrated EPC platform that combines self-perform construction with in-house engineering and high-voltage capabilities to deliver projects with greater confidence in execution outcomes. Generation, including hybrid solar-plus-storage projects, generated $643 million and $406 million of revenue for the years ended December 31, 2025 and 2024, respectively, and T&D projects generated $96 million and $37 million for the years ended December 31, 2025 and 2024, respectively.
Engineering. We provide design and engineering services for solar and battery storage projects and high-voltage transmission and distribution infrastructure, including site layout, drainage plans, site road design, foundation sizing analysis, site and system optimization, sub-surface geotechnical evaluation, energy modeling and electrical engineering. We apply a data-driven approach to value engineering to optimize a project’s design for size, cost, technology selection and long-term energy output. Our in-house engineering capabilities allow us to identify and address design risks early in project planning to reduce execution risk during construction. We have licensed engineers on staff and act as the EOR for certain projects, including high-voltage scopes, providing our customers with stamped IFC drawings. By maintaining ownership of the project’s design, we align engineering decisions with constructability requirements identified by our field crews and reduce execution risk as the project moves from engineering to construction. Our construction experience also ensures our designs account for real-world conditions, helping to limit unplanned costs and schedule delays. We typically charge for engineering services under LNTP agreements and as part of a broader lump sum EPC contract.
Procurement. We typically procure most of the equipment and materials used in the projects we build, except for solar modules and batteries that are typically purchased directly by our customers. Major equipment and materials categories we purchase to use in our customers’ projects include steel foundations, inverters, trackers and fixed racking systems, cabling, transformers and circuit breakers which typically represents approximately 40% of the total value of our EPC contracts. We offer procurement services, including advising our customers on the merits of various equipment suppliers, specifying the appropriate equipment for the site and desired capabilities, negotiating purchase terms and purchasing the equipment. We have established master supply agreements with key equipment suppliers across all our scopes with pre-negotiated terms that provide preferred pricing, sourced capacity and reduced lead times to meet the timelines needed by each project. These agreements, in combination with our well-established supplier relationships, provide greater predictability around pricing, delivery schedules, and availability. This predictability is particularly important for high-voltage equipment, such as transformers and circuit breakers, which are subject to supply constraints and extended manufacturing lead times. We actively manage supplier performance and maintain a diversified vendor base to mitigate concentration risk and support continuous project execution. We typically charge for procurement services as part of a lump sum EPC contract.
Construction. We provide comprehensive construction services for utility-scale solar projects, battery energy storage systems and high-voltage T&D infrastructure that cover the civil, mechanical, and electrical scopes of
120
Table of Contents
work to deliver fully integrated power plants. The civil scope of work typically includes site preparation activities such as clearing and grading the site, construction of access roads, installation of retention ponds and development of drainage systems. The mechanical scope of work typically includes installing pile foundations and structural posts, erecting the racking systems and mounting solar modules. For solar and battery storage projects, the electrical scope of work typically includes installing electrical balance of system components, inverters, and batteries, as well as interconnecting project equipment. For high-voltage transmission and distribution projects, our electrical scopes typically include installing major substation and switching station equipment, conductors, main power transformers, circuit breakers, switches, sensors, protective relays, control systems and SCADA systems. We provide both aerial and underground high-voltage transmission and distribution lines which typically includes installing aerial structures and conductors or underground conductors as well as associated communications systems used for transmission protection, control and monitoring.
Our execution model includes self-performing most scopes of work on our projects through in-house workforce and operational capabilities. By utilizing our trained workforce, standardized processes and dedicated equipment fleet, we maintain greater control over the safety, schedule, quality, and productivity of our jobs. Safety and quality standards are embedded into our field operations through structured training programs, active jobsite supervision, and disciplined work practices. We typically charge for construction services as part of a lump sum EPC contract.
Commissioning and Testing. We perform a series of tests on equipment to verify that our customers’ equipment and systems operate in accordance with original equipment manufacturer’s specifications and warranties, and we conduct utility testing to confirm that power output requirements are met. We also perform performance tests to validate that contractual performance standards are achieved. We coordinate closely with utilities, system operators, and third-party inspectors to ensure testing protocols align with applicable interconnection and grid requirements. High-voltage system commissioning and testing typically includes insulation tests of all equipment as well as simulation tests to functionally test all protection, control and SCADA systems. Post-energization tests are performed to assure proper operating conditions. We typically charge for commissioning and testing services as part of a lump sum EPC contract.
Customers
Our customers include project developers, independent power producers, utilities, industrial facilities, and data center operators. For the year ended December 31, 2025, our largest customer represented approximately 20% of our total revenues, and our top ten customers collectively represented approximately 96% of our total revenues. For the six months ended June 30, 2026, our largest customer represented approximately 45% of our total revenues and our two largest customers collectively represented approximately 59% of our total revenues. As of June 30, 2026, the average tenure of our relationship with our top ten customers was 6.2 years. We do not have long-term volume commitments from our customers, and our contracts are typically awarded on a project-by-project basis. The loss of, or significant reduction in business from, any of our significant customers could have a material adverse effect on our business, financial condition, and results of operations. For additional information regarding customer concentration risks, see “Risk Factors–Risks Related to Our Business–The loss of, or reduction in business from, significant customers could have a material adverse effect on our business, financial condition, and results of operations.”
Customer Contracts
We initially engage with customers by providing a proposal which includes pricing for an EPC contract, based on site layout, key equipment parameters, sub-surface geotechnical evaluation, and other project-specific information. If a customer accepts our proposal and awards the project to us, we typically enter into an LNTP
121
Table of Contents
agreement pursuant to which the customer pays us for initial engineering and site investigation work that allows us to advance projects while we finalize contract terms, project design and the scope of work. We typically execute additional LNTPs that include procurement of long-lead equipment and materials and initial mobilization of our workforce, before we enter into a lump sum EPC contract with our customer. LNTP agreements reduce our risk by allowing us to learn more about the site conditions, reduce estimating assumptions and more accurately forecast our costs prior to entering into an EPC contract, and it benefits our customers by reducing change orders and schedule disruptions during construction. Customer payments from LNTP agreements also fund engineering services early in project execution which reduces our working capital needs and strengthens our liquidity.
Following completion of the LNTP agreements, we typically engage with customers for EPC services under lump sum contracts that are executed over 12 to 18 months. Our lump sum contracts allocate responsibility for specific aspects of the work between the parties, such as permitting and procurement tasks, and establish project timelines, terms of the payment process, and risk allocation between us and the customer for a lump sum. Our standard lump sum contracts establish our right to receive a change order from the customer should the actual conditions under which a project is built differ from the anticipated conditions on which the contract was based, such as unexpected site conditions, adverse weather impacts, or delays caused by the customer. When a project requires changes to the scope of services in a lump sum contract, we charge amounts over and above the lump sum to compensate us for the change on either a lump sum or time and materials basis. We typically receive a mobilization payment from the customer when we begin work that is usually 5-10% of total contract value, and we bill customers monthly for our services on a percentage-of-completion basis for the remainder of the contract. Our LNTP agreements typically include similar terms but generally apply to stages of work occurring early in the project timeline.
Our EPC contracts typically contain termination for convenience provisions that permit the customer to terminate the contract upon short notice, generally within 3 to 10 business days. Upon a termination for convenience, the customer is generally required to pay us for: (a) work performed through the termination date; (b) materials procured or committed; (c) reasonable, documented demobilization costs; and (d) subcontractor and supplier cancellation charges. Our contracts generally do not provide for recovery of lost profits on unperformed work in the event of a termination for convenience. Our LNTP agreements are similarly terminable by the customer, and customers are not obligated to proceed from the LNTP phase to a full EPC contract; if terminated prior to full notice to proceed, our recovery is generally limited to costs incurred during the LNTP phase. Our contracts generally permit partial terminations or scope reductions, subject to equitable adjustment of the contract price for work removed from the scope. For additional information regarding contract cancellation risks, see “Risk Factors–Risks Related to Our Business–Many of our contracts may be canceled, suspended, or not renewed on short notice, and we may be unsuccessful in replacing such contracts.”
Our lump sum contracts include mutual insurance and indemnity obligations and generally contain liquidated damages provisions tied to a timeline for completion of the project. Although claims of liquidated damages may occasionally be asserted in the normal course of business, they are infrequently agreed to and paid by us. Our LNTP agreements generally do not include liquidated damages provisions. We typically provide parent guarantees for our EPC contracts. In addition, some of our lump sum contracts require us to maintain surety bonds for the benefit of the customers during the construction. We maintain relationships with multiple surety bonding providers and, historically, we have not experienced material difficulties obtaining bonding for our projects.
Termination and Cancellation Provisions
Our EPC contracts typically contain termination for convenience provisions that permit the customer to terminate the contract at any time, in whole or in part, upon short written notice, generally within 3 to
122
Table of Contents
10 business days. There are no contractual limitations on a customer’s right to exercise a termination for convenience and no conditions precedent to such exercise other than providing the requisite written notice. Upon a termination for convenience, the customer is generally required to pay us for: (a) all work performed through the effective date of termination, valued at the rates and prices set forth in the contract; (b) the cost of materials and equipment procured, in production, or committed for the project; (c) reasonable, documented demobilization costs; and (d) cancellation charges and fees payable to our subcontractors and suppliers. Certain of our EPC contracts also provide for a markup (typically 10%) on direct costs and documented termination expenses payable upon a termination for convenience, which effectively functions as a termination fee. However, the majority of our contracts do not include a standalone termination fee or markup beyond reimbursement of costs incurred and documented demobilization expenses. Our contracts generally do not provide for recovery of lost profits or overhead on unperformed work in the event of a termination for convenience; rather, amounts recoverable are expressly limited to the value of work actually performed and costs actually incurred prior to the effective date of termination, and in no event may such amounts exceed the total contract price. Where our contracts do not include a termination fee or markup, we bear the risk that the amounts recoverable upon a termination for convenience may not fully compensate us for the loss of anticipated project revenue and profit margin.
Our LNTP agreements are similarly terminable by the customer, and customers are not obligated to proceed from the LNTP phase to a full EPC contract. If an LNTP agreement is terminated prior to full notice to proceed, our recovery is generally limited to costs incurred during the LNTP phase, and the customer’s sole obligation with respect to the unprocured portion of the work is to pay for work performed and commitments made through the date of termination.
Other than the termination by a customer for convenience of a single LNTP agreement with a total value of less than $3 million in 2024, the Company has not experienced any contract cancellations or terminations for convenience during 2024 or 2025.
Scope Revisions
Our contracts generally permit customers to direct changes to the scope of work through the change order process. Scope additions are subject to equitable adjustment of the contract price and, where applicable, the project schedule, through negotiated change orders. Our contracts do not impose contractual limitations on the customer’s right to direct scope additions or reductions, provided that any scope change is processed through the contractual change order mechanism. Scope reductions are permitted at the customer’s direction, subject to equitable adjustment of the contract price for work removed; however, the customer is generally not required to pay a penalty or additional fee on account of a scope reduction beyond compensating us for work already performed and commitments already made. Our contracts do not typically include minimum scope commitments or thresholds below which a scope reduction would trigger automatic renegotiation of unit pricing or other contract terms; accordingly, customers have the ability to reduce scope without limitation, provided that we are compensated for work performed and commitments made prior to the scope reduction. In practice, material scope reductions are infrequent, as they typically require corresponding modifications to project design, permitting, and interconnection arrangements that make significant reductions impractical once construction has commenced.
For additional information regarding contract cancellation risks, see “Risk Factors–Risks Related to Our Business–Many of our contracts may be canceled, suspended, or not renewed on short notice, and we may be unsuccessful in replacing such contracts.”
123
Table of Contents
Sales & Marketing
We have a dedicated business development team that focuses on building long-term relationships with IPPs, project developers, utilities, data centers and industrial facilities. We maintain ongoing dialogues regarding future project requirements and development plans with our customers, which provides significant visibility into upcoming project opportunities. We employ a consultative approach, engaging early in the planning and design phases of a project to provide our customers with guidance on technical and cost assumptions, often well before a traditional EPC would be involved. As a result, we believe we have more visibility on and access to potential opportunities.
Our business development professionals are specialized across utility-scale solar, battery storage and high-voltage transmission and distribution infrastructure and provide technical support throughout the sales process. We incentivize our business development team to actively identify and pursue cross-selling opportunities across our offerings, positioning us as a comprehensive infrastructure services provider with the ability to support customers across multiple project scopes. Our high voltage capabilities also enable us to engage with customers before our competitors who do not have in-house high voltage teams as grid interconnection and high-voltage engineering are typically addressed prior to beginning construction planning on generation facilities.
We also work to increase awareness of our company and capabilities through membership in prominent industry trade associations, including the Solar Energy Industries Association and through participation in key industry events including RE+, Infocast, Intersolar North America and Asset Management North America. We complement these efforts with targeted public relations campaigns aimed at driving brand awareness and educating clients and prospects on the breadth of our service offerings
Competition
We compete primarily on the basis of safety, execution track record, technical capability, financial strength, price, and the ability to deliver large, complex projects on schedule and within budget. We compete with both large, national companies, that have significant financial and technical resources, as well as with small, regional companies. As projects increase in size and complexity, we believe the market increasingly favors contractors with scale, financial capacity, and proven execution capability. Our principal competitors in the generation and storage markets include Kiewit, MasTec, McCarthy, Mortenson, Moss, Primoris Services, Quanta Services, Rosendin and SOLV Energy. Our principal national competitors in high voltage transmission and distribution include Burns & McDonnell, GW, Black & Veatch, MasTec, MYR Group and Quanta Services.
Suppliers
We maintain strong relationships with leading equipment manufacturers and have entered into master supply agreements with certain suppliers across key procurement categories, which provide us with meaningful optionality and access to favorable commercial terms and pricing. The principal categories of equipment we procure for our customers include steel foundations, inverters, trackers and fixed racking systems, cabling, transformers and circuit breakers. Through our strong supplier relationships, we are able to source materials and components from both domestic and international companies to optimize total delivered costs and, where applicable, satisfy IRA domestic content requirements.
We work with multiple qualified suppliers for each key equipment category and do not have material dependence on any single vendor or supplier of technologies or products. In addition, we collaborate with suppliers on product and design improvements intended to enhance construction efficiency and optimize the performance of completed power plants.
124
Table of Contents
We have developed a domestic procurement strategy supported by established supplier relationships that enable us to offer fully domestically sourced projects when required or preferred by our customers. Where materials and components are sourced internationally, import tariffs are generally passed through to our customers pursuant to change of law provisions in our contracts, which provide for an adjustment to the contract price based on the tariffs in effect at the time of import. This approach substantially mitigates tariff risk for us while providing a fair and transparent process for our customers.
Human Capital
Employees. As of June 30, 2026, we employed approximately 345 professionals and 757 trade and craft employees. Our workforce size fluctuates based on backlog, customer needs and project schedules. Our professional staff includes experienced project managers, engineers, estimators and other personnel who oversee the execution of our EPC projects. Our trade and craft workforce includes skilled electricians, equipment operators, laborers and other craft workers who perform construction activities on our project sites.
We execute projects using both union and non-union labor depending on customer and geographic requirements and preferences. When required, we typically partner with local unions under project-specific labor agreements, including the National Tri-Trade Solar Agreement (“NTTSA”), which we may amend to address project-specific requirements. We believe the NTTSA helps reduce inter-trade conflicts and mitigate potential delays through coordinated staffing among participating unions. We have established strong relationships with the International Brotherhood of Electrical Workers (“IBEW”), the Laborers’ International Union of North America (“LiUNA”), and the International Union of Operating Engineers (“IUOE”), and have not experienced any labor-related work stoppages.
Training and Retention. We believe that each of our employees must be committed to our core values of safety, quality and customer service. Our ability to execute our backlog and deliver complex projects depends on attracting, developing and retaining a highly skilled workforce, including craft labor, project management, engineers and technical professionals. As demand for skilled labor across the energy infrastructure sector continues to increase, we focus on proactively building and maintaining a scalable talent pipeline to support our growth. We invest in workforce development through a combination of technical training programs, on-the-job experience and targeted skill development designed to support the safe and efficient execution of solar, BESS and high-voltage T&D projects. These programs are focused on developing specialized capabilities across our self-perform disciplines and enhancing field productivity. We also emphasize leadership development to support our operating model and ensure continuity across our project teams. Our approach to training and retention is designed to reinforce our culture, improve employee engagement and position us to meet the increasing complexity and scale of our projects.
Safety
Our safety program is designed to take a proactive, data-driven approach to safety focused on risk anticipation and prevention. Engagement by our executive team supports our safety culture, with regular reviews of performance indicators and high-risk controls reinforcing accountability and safety as a core organizational value. We foster a proactive culture through workforce engagement, continuous training, and leading indicators—safety observations, audits, good catches and stop-work authority—to identify and mitigate risks before incidents occur. Employees are empowered and expected to anticipate risks, speak up and take action when conditions are unsafe. By embedding these behaviors into how work is planned and executed, safety is built into our operations, not inspected after the fact.
Our safety performance has compared favorably to industry benchmarks, even as we have scaled our operations. Our total recordable incident rate (“TRIR”) per one hundred employees per year was 0.66 during
125
Table of Contents
2025. Our days away, restricted or transferred (“DART”) rate was 0.15 during 2025. Our TRIR was 56% and our DART rate was 84% lower than the most recently published U.S. Bureau of Labor Statistics’ overall rates for the power and communication line and related structures construction industry, respectively. We received the National Safety Council Occupational Excellence Achievement Award in each of 2023, 2024 and 2025 and achieved over five million work hours without a lost-time injury.
We believe that our exceptional safety record is driven, in part, by our self-perform delivery model, which allows us to maintain direct control over the training, supervision, and performance of our workforce. Unlike competitors who rely more heavily on subcontractors, our self-perform approach enables us to instill our safety-first culture throughout our organization and ensure consistent adherence to our rigorous safety standards across all project sites. We conduct regular safety audits, provide ongoing training, and maintain incident reporting and investigation processes to support continuous improvement. Our safety performance is an important consideration for customers, who increasingly evaluate safety outcomes when selecting contractors.
Facilities
Our corporate headquarters are located in Houston, Texas, and we maintain additional offices in Chattanooga, Tennessee and Albany, New York. Our Houston headquarters and Chattanooga office support our corporate, administrative, engineering and project management functions, while our Albany office primarily supports our high-voltage operations and projects in the northeastern United States. We are in the process of expanding our Houston office and believe that our corporate headquarters and other offices are adequate for our immediate needs and that we will be able to obtain additional or substitute space, as needed, on commercially reasonable terms to support our growth plans.
In addition to our office facilities, we operate a 54,000 square foot equipment yard and maintenance facility in Houston, Texas, which serves as a central hub for equipment maintenance and storage of materials. The facility performs inspections, repairs, preventative maintenance, major component replacements and equipment staging to reduce downtime, extend asset lifecycles and ensure equipment is ready for deployment. It also supports the centralized management of surplus and reusable materials, enabling efficient deployment to projects and contributing to consistent execution and cost efficiency.
Our Impact
We prioritize the communities where we work and are committed to partnering with our customers and local stakeholders to maximize positive social impacts from our projects. By collaborating closely with customers and local stakeholders, we strive to build trust and ensure our presence delivers tangible, shared value. We invest resources into being a responsible neighbor, supporting initiatives in the communities where our projects are located, like local charities, solar energy and battery storage education, public school partnerships, and community revitalization efforts. Our commitment to the communities we serve is an integral part of our company culture and reflects our belief that the energy transition should benefit all stakeholders. Our people are at the heart of our business, and we are focused on fostering an inclusive workplace culture that empowers every employee to contribute meaningfully to the communities we serve. Central to this commitment are our efforts to recruit from local communities, develop career pathways for craft workers (including enrolling local citizens in our apprenticeship training program), and promote diversity and inclusion throughout our organization.
126
Table of Contents
Our Operating Subsidiaries
We conduct our operations through two material operating subsidiaries of CoVolt Holdings. The following summarizes the services provided by each of our material operating subsidiaries and how our organizational structure aligns with our service lines:
Signal Energy, LLC is our primary operating subsidiary and serves as the principal platform for our solar and battery storage EPC service line. Signal Energy, LLC provides comprehensive engineering, procurement, and construction services for utility-scale solar generation projects and battery energy storage systems and serves as the prime contractor on our solar EPC projects, contracting directly with project owners for full-scope integrated delivery.
Applied High Voltage, LLC operates our high-voltage platform and serves as the principal platform for our T&D and high-voltage service line. Applied High Voltage, LLC is an EPC contractor that specializes in high-voltage electrical engineering services and designs and builds high-voltage substations, switchyards, collector systems, and transmission lines for projects across the United States. Applied High Voltage, LLC’s revenue comes from standalone high-voltage projects contracted directly with external customers, including independent power producers, utilities, and data center operators, and high-voltage scopes on integrated solar EPC projects where Signal Energy, LLC is the prime contractor.
Legal Proceedings
We are currently involved in, and may in the future from time to time become involved in, legal proceedings, claims and investigations in the ordinary course of our business, including with our customers, subcontractors, and suppliers. Although the results of these legal proceedings, claims and investigations cannot be predicted with certainty, we do not believe that the final outcome of any matters that we are currently involved in are reasonably likely to have a material adverse effect on our business, financial condition or results of operations. Regardless of final outcomes, however, any such proceedings, claims, and investigations may nonetheless impose a significant burden on management and employees and may be costly to pursue/or defend, with the possibility of unfavorable outcomes.
Insurance & Risk Management
Our construction and general business operations involve the use of heavy equipment and exposure to inherently hazardous conditions, and we accordingly maintain a broad portfolio of insurance policies designed to address the range of risks associated with these activities. Our insurance program covers, among other exposures, employer’s liability, workers’ compensation, automobile liability, aviation/drone, cyber risks, directors and officers liability, financial and general liability risks. We manage a portion of our overall risk exposure through self-insured retentions and deductibles under our primary insurance policies, supplemented by a tower of excess insurance coverage from additional carriers to protect against losses that exceed our primary limits. Our insurance policies are subject to annual renewal, and as a result, the applicable deductibles and coverage levels may be adjusted from period to period. We also work closely with our customers/project owners to ensure the procurement of builders risk insurance for each project with reasonable deductibles and sufficient limits to cover the loss or damage to the work itself, including customer supplied equipment (e.g. modules, inverters, etc.) that are under our care, custody, and control. For additional information regarding our insurance and the risks associated with insurance coverage, see “Risk Factors–Risks Related to Our Business–Our insurance coverage may be inadequate to cover all losses or liabilities we may incur, and insurance may become more difficult or expensive to obtain in the future.”
The physical risks associated with climate change have heightened certain hazards inherent in our operations and have contributed to increased potential liability exposure and higher operating costs. Severe weather
127
Table of Contents
events, including extreme temperatures, hail, hurricanes, ice, heavy snowfall, wildfires and flooding, may delay our operations and cause significant damage to both the equipment used on our projects and our customers’ assets. The potentially significant liabilities arising from any of these climate-related events could have a material adverse effect on our business, financial condition and results of operations. In addition, the increasing frequency and severity of these conditions may result in higher premiums for third-party insurance coverage and may reduce the capacity that insurance carriers are willing to extend to us under such policies. See “Risk Factors–Risks Related to Our Business–Our construction schedules, project economics, and results of operations are subject to physical risks, including severe weather events, natural disasters, and risks associated with climate change that can halt site work or damage projects in progress.”
Regulation
Compliance with a wide range of federal, state and local laws, regulations and standards materially affects our operations and the way we conduct business. The regulatory requirements to which we are subject include:
| • | Licensing, permitting and inspection requirements for contractors and engineers; |
| • | Building and electrical codes; |
| • | Wage and hour laws, including the Fair Labor Standards Act, as well as requirements arising under our collective bargaining agreements and obligations related to our unionized workforce; worker safety and health regulations, including those promulgated by the Occupational Safety and Health Administration; |
| • | Environmental protection and climate-related regulations, including those administered by the Environmental Protection Agency; |
| • | Permitting and inspection requirements for construction projects; applicable reliability standards, rules and guidelines of the North American Electric Reliability Corporation (including NERC CIP standards), the Federal Energy Regulatory Commission, the Electric Reliability Council of Texas and the relevant utility on any given project; |
| • | Regulations governing the sourcing and transportation of equipment and materials; requirements relating to the engagement of suppliers and subcontractors meeting diversity-ownership or disadvantaged-business criteria; |
| • | Applicable U.S. and non-U.S. anti-corruption laws; immigration laws applicable to domestic and cross-border employment; regulations pertaining to tax credits or tax abatement agreements pursued by project owners; and |
| • | Cybersecurity and other cyber-related requirements applicable to certain projects. |
We believe we are in compliance in all material respects with all material licensing and regulatory requirements necessary to conduct our business. Failure to maintain compliance with applicable regulations could expose us to substantial fines or the loss of certain operating licenses, and could trigger termination or cancellation rights under our contracts or render us ineligible for future bidding opportunities.
Our operations are also subject to numerous federal, state and local environmental laws and regulations governing the handling, transportation and disposal of hazardous and non-hazardous substances and wastes, as well as emissions and other discharges into the environment, including to air, surface water, groundwater and soil. Certain of these laws impose liability and cleanup responsibility for releases of hazardous substances into the environment. Such liability may be joint and several, meaning that a responsible party may be held liable for the entire cost of cleanup regardless of fault. These laws may also impose liability for cleanup costs at sites we previously owned or operated, or at our current sites where hazardous substances were discharged or
128
Table of Contents
disposed of by former owners or operators, even if such contamination was not caused by us or did not constitute a violation of law at the time. Any failure by us to control the use of, to remediate the presence of or to adequately restrict the discharge of such substances, materials or wastes, or to comply with applicable environmental laws and regulations, could subject us to potentially significant liabilities, including cleanup costs, monetary damages, fines, the revocation of licenses or permits and suspensions of our business operations, any of which could have a material adverse effect on our business, financial condition and results of operations. We believe we are in substantial compliance with our environmental obligations and, from time to time, we incur, and expect to continue to incur, costs and obligations related to maintaining compliance with environmental laws and regulations, correcting environmental noncompliance and remediating conditions at or relating to our project sites. New or amended laws and regulations, changes in the interpretation of existing requirements and increased regulatory scrutiny could further require us to incur significant costs or give rise to new or increased liabilities.
From time to time, we and our customers benefit from government subsidies and economic incentives, including solar energy and battery storage tax credits, rebates and other programs designed to support the development and adoption of clean energy solutions. For example, the IIJA supports solar power and solar energy and battery storage projects by providing federal tax credits that promote investment in infrastructure and clean energy programs. Additionally, the IRA introduced and extended several U.S. federal income tax credits aimed at promoting clean energy development. Since its enactment, the IRA has driven substantial investment in clean energy projects and has correspondingly increased demand from our customers for the services we provide.
While these government incentives benefit our business, adverse actions, interpretations or determinations under new or existing laws or regulations could have a negative impact on our operations. Under the OBBBA, which was signed into law on July 4, 2025, the CEPC and the CEIC under Section 45Y and Section 48E of the Code, respectively, for solar and wind projects are subject to an accelerated termination schedule. Solar and wind projects must either (1) begin construction (as determined for U.S. federal income tax purposes) on or before July 4, 2026 or (2) be placed in service (as determined for U.S. federal income tax purposes) on or before December 31, 2027 to qualify for these tax credits. Moreover, following the enactment of the OBBBA, the Trump Administration issued an executive order requiring the Treasury, among other things, to enforce the accelerated termination of the CEPC and CEIC for solar and wind projects. Treasury and the IRS subsequently released IRS Notice 2025-42, which, among other changes, eliminated the opportunity for developers and other project owners to be treated as having begun construction of a solar or wind project by paying or incurring at least five percent (5%) of the total costs of the relevant project. The accelerated sunset of the CEPC and CEIC for solar projects under the OBBBA, along with the Trump Administration’s recent enforcement efforts, could constrain the availability of U.S. federal income tax credits for future solar projects and therefore could have a material adverse impact on future levels of investment in utility-scale solar projects in the United States, potentially resulting in a significant reduction in demand for our services.
In addition, the OBBBA created new limitations and restrictions relating to the direct or indirect ownership, influence or control of U.S. clean energy projects by, and the inclusion of equipment and components within U.S. clean energy projects provided by, citizens of and entities organized under the laws of or having their principal place of business in certain non-U.S. countries, including the PRC and certain affiliated entities thereof. Solar and battery storage projects that fail to comply with these limitations and restrictions are generally ineligible to claim the CEPC and CEIC (in the case of solar projects) and the CEIC (in the case of battery storage projects). These new requirements may negatively affect the competitiveness of utility-scale solar projects and co-located solar and battery storage projects relative to conventional sources of electricity, which could reduce the number of new utility-scale solar and battery projects and result in a significant reduction in the demand for our services. Moreover, the restrictions on the inclusion of equipment and components
129
Table of Contents
provided by entities with nexus to the PRC may require us to reevaluate our suppliers and underlying supply chains and could materially increase the cost of delivering EPC services to our customers.
Collectively, these and other actions could have a material impact on future levels of investment in utility-scale solar projects. See “Risk Factors–Risks Related to Our Industry–The reduction, elimination, or expiration of government incentives for solar energy and battery storage could significantly reduce demand for our EPC services.”
In recent years, certain of our projects and certain customer spending in our industry have been negatively affected by regulatory and permitting delays. Any tariffs, duties, taxes, assessments or other limitations on the availability or sourcing of materials, equipment or components for our customers’ projects can increase costs and create variability in project timing. For example, regulatory, legislative or executive action with respect to regional and global trade relationships has impacted, and may continue to impact, the supply chain for certain critical components required for our customers’ projects (e.g., transformers, breakers and other key electrical components) and the costs associated therewith. For additional information regarding the effects of regulation on our business, see “Risk Factors–Risks Related to Our Business–The imposition of tariffs, duties, and other trade barriers could increase our costs, disrupt supply chains, and have a material adverse effect on our business.”
Conversely, we believe that several existing, pending or proposed legislative or regulatory actions may alleviate certain regulatory and permitting challenges and positively impact long-term demand, particularly in connection with solar and solar energy and battery storage projects. For example, regulatory changes aimed at reducing lengthy permitting processes could potentially result in accelerated project approvals, and a growing focus on domestic energy production could create additional incentives for solar and solar energy and battery storage development. Additionally, legislation such as the IIJA, together with other policy and economic incentives and overall public sentiment, is designed to support and encourage solar and solar energy and battery storage projects that can potentially increase demand for our services over the long term.
130
Table of Contents
Table of Contents
The following table sets forth information regarding our executive officers and members of our board of directors, including their ages as of the date of this prospectus. With respect to our directors, each biography includes information regarding the experience, qualifications, attributes, or skills that caused our board of directors to determine that such person should serve as a director of our company.
| Name | Age | Position(s) | ||||
| Executive Officers | ||||||
| Robert L. Tabb | 41 | President & Chief Executive Officer | ||||
| Ronnie V. Shields | 63 | Chief Financial Officer | ||||
| Samuel K. Robison | 62 | Chief Legal Officer | ||||
| Directors | ||||||
| Robert L. Tabb | 41 | President & Chief Executive Officer | ||||
| Avinash Kripalani | 42 | Director | ||||
| Stephen W. Atkins | 67 | Director | ||||
| Sean K. Coleman | 56 | Director | ||||
| Matthew Kimble | 55 | Director | ||||
| Rebekah B. Le | 51 | Director | ||||
| Louis Littman | 39 | Director | ||||
Executive Officers
Robert L. Tabb has served as our Chief Executive Officer since October 2024 and as a member of our board of directors since August 2026, and served as our Chief Financial Officer from 2021 to 2024. Prior to leading CoVolt Power, Mr. Tabb worked at Orion Group Holdings, a specialty construction firm, from 2014 to 2021 where he served as Executive Vice President & Chief Financial Officer. Prior to Orion Group Holdings, Mr. Tabb served in progressively more senior roles at Mattress Firm and MXenergy acquired by Constellation Energy, an Exelon company focused on power generation, wholesale power trading, regulated utilities and retail energy sales, from 2009 to 2014. Mr. Tabb holds a Bachelor of Business Administration degree in Finance from Texas Southern University and a Master of Business Administration from the University of Houston. We believe Mr. Tabb’s visionary leadership and innovative thinking, as well as his extensive knowledge and experience in the construction and energy industries, make him qualified to serve as a member of our board of directors.
Ronnie V. Shields has served as our Chief Financial Officer since October 2024 and served as our Chief Accounting Officer from January 2022 to October 2024. Prior to joining CoVolt Power, Mr. Shields worked at Orion Group Holdings, Inc., a publicly traded marine and concrete construction company, from July 2019 to January 2022, where he served as Chief Accounting Officer. Prior to Orion Group Holdings, Mr. Shields served as Director of Accounting at Constellation, an Exelon company focused on power generation, wholesale power trading, regulated utilities and retail energy sales, from June 2011 to September 2018. Mr. Shields holds a Bachelor of Arts degree in Accounting from Texas Southern University.
132
Table of Contents
Samuel K. Robison has served as our Chief Legal Officer since October 2022. Prior to joining CoVolt Power, Mr. Robison worked at Technip Energies N.V. (and its predecessor, Technip S.A.), a global energy technology and services company, from August 2012 to October 2022, where he most recently served as Vice President Legal–Innovation & Technology from January 2017 to October 2022. Prior to Technip, Mr. Robison served as Vice President & General Counsel, Energy & Chemicals Group at The Shaw Group Inc. from October 2011 to August 2012, having previously served as Division Counsel in The Shaw Group’s Energy & Chemicals Group from September 2006 to October 2011 and in its Construction & Maintenance Division from February 2004 to September 2006. Mr. Robison holds a Juris Doctor from Chicago-Kent College of Law, Illinois Institute of Technology and a Bachelor of Science in Construction Engineering from Purdue University.
Non-Employee Directors
Avinash Kripalani has served on our predecessor’s board of directors since 2022 and as a member of our board of directors since August 2026. Mr. Kripalani has served as a Senior Managing Director in the Opportunistic Credit group at Man Group since October 2025. Prior to Man Group’s acquisition of Bardin Hill Investment Partners, Mr. Kripalani served as a Partner and as the chair of the firm’s risk oversight committees at Bardin Hill, where he had worked since April 2008. Mr. Kripalani has served on the board of directors of NextDecade Corp., a publicly traded liquefied natural gas development company, since April 2016, where he currently serves on the Audit Committee and the Finance and Risk Committee. Mr. Kripalani holds a Master of Science degree in Systems and Information Engineering, a Bachelor of Science degree in Systems and Information Engineering, and a Bachelor of Arts degree in Economics, each from the University of Virginia. We believe Mr. Kripalani is qualified to serve on our board of directors because of his experience as a professional investor with extensive experience investing in companies in the power, renewables, midstream and utilities sectors and his tenure as a director of a public company.
Stephen W. Atkins has served on our predecessor’s board of directors since 2021 and as a member of our board of directors since August 2026. Mr. Atkins previously served as Executive Vice President and Chief Financial Officer of the construction services division of AECOM from December 1999 until his retirement in February 2019. Prior to AECOM, Mr. Atkins served as CFO of the OmniFax division of Xerox Corporation, Horizons Learning Centers LP, and EF Data Corporation from June 1992 to November 1999. Earlier in his career, Mr. Atkins served as a Senior Manager at Ernst & Young from June 1980 to June 1992. Mr. Atkins currently serves on the board of directors of ASU Newman Center Finance Council. Mr. Atkins holds a Bachelor of Science degree in Accounting from Arizona State University, where he graduated magna cum laude, and is a retired Certified Public Accountant. We believe Mr. Atkins is qualified to serve on our board of directors because of his nearly four decades of experience in public accounting and CFO roles in construction organizations and his deep construction risk management experience.
Sean K. Coleman has served on our predecessor’s board of directors since 2026 and as a member of our board of directors since August 2026. Mr. Coleman has served as Chief Executive Officer of Eyre Street Capital, an opportunistic credit investing firm, since April 2025. Prior to founding Eyre Street Capital, Mr. Coleman served as a Senior Portfolio Manager at Avenue Capital from April 2021 to March 2025. Earlier in his career, Mr. Coleman served as a Managing Director in the direct lending group at Golub Capital and served as Chief Financial Officer of Golub Capital BDC in 2010. Mr. Coleman holds a Bachelor of Arts degree in History from Princeton University and a Master of Business Administration from Harvard Business School, where he graduated with Distinction. We believe Mr. Coleman is qualified to serve on our board of directors because of his extensive experience in credit investing and capital markets and his financial reporting expertise.
Matthew Kimble has served on our predecessor’s board of directors since 2022 and as a member of our board of directors since August 2026. Mr. Kimble has served as a Senior Portfolio Manager at Avenue Capital Group
133
Table of Contents
since May 2003, where he has over 20 years of experience investing in power infrastructure and energy transition. Prior to joining Avenue Capital, Mr. Kimble served as an Analyst at Bellport Capital from September 2000 to March 2003. Mr. Kimble currently serves on the boards of directors of Homer City Holdings LLC. Mr. Kimble holds a Bachelor of Science degree in Accounting from the University of Illinois at Urbana-Champaign and a Master of Business Administration in Finance from NYU Stern School of Business. We believe Mr. Kimble is qualified to serve on our board of directors because of his more than two decades of experience investing in power infrastructure and energy transition and his expertise in industries with significant commodity and regulatory risks.
Rebekah B. Le has served on our predecessor’s board of directors since November 2021 and as a member of our board of directors since August 2026. Ms. Le has served as Chief Strategy and Financial Officer of Legacy Community Health since May 2024. Prior to joining Legacy Community Health, Ms. Le served as Chief Financial Officer of MasTec’s Power Delivery segment, an infrastructure construction company, from February 2023 to May 2024. Overall, Ms. Le has spent more than twenty years in the construction industry. Earlier in her career, Ms. Le served as Director of Technical Accounting and SEC Reporting at McDermott International, a publicly traded engineering and construction company, and as an auditor at PricewaterhouseCoopers LLP. Ms. Le currently serves on the advisory board of The Woman’s Hospital of Texas. Previously, Ms. Le served on the boards of directors at Legacy Community Health Services from November 2021 to May 2024 and at The Women’s Resource from November 2016 to December 2021. Ms. Le holds a Bachelor of Business Administration degree in Accounting from the University of Houston and is a Certified Public Accountant. We believe Ms. Le is qualified to serve on our board of directors because of her extensive experience in financial leadership, including technical accounting and SEC reporting at publicly traded companies, and her audit experience at a Big Four accounting firm.
Louis Littman has served on our predecessor’s board of directors since 2022 and as a member of our board of directors since August 2026. Mr. Littman is currently a Managing Director at Davidson Kempner Capital Management, LP, an investment management firm, and has been a member of the firm since 2013. Mr. Littman currently serves on the boards of directors of Prytek Holdings Pte and Delta Capita Holdings. Mr. Littman holds a Bachelor of Science degree in Economics from the University of Pennsylvania, where he graduated summa cum laude. We believe Mr. Littman is qualified to serve on our board of directors because of his extensive experience as an investor in the power and renewables industry, deep knowledge of public and private capital markets, and demonstrated expertise in capital allocation and other governance matters.
Family Relationships
There are no family relationships among any of our directors or executive officers.
Controlled Company Exception
After the completion of this offering, certain of our Continuing Equity Owners will collectively hold a majority of the combined voting power of our shares eligible to vote for the election of our directors. As a result, we will be a “controlled company” within the meaning of the NYSE corporate governance standards, and accordingly, we intend to elect not to comply with certain corporate governance standards, including the requirements (1) that a majority of our board of directors consist of independent directors, (2) that our board of directors have a compensation committee that is comprised entirely of independent directors with a written charter addressing the committee’s purpose and responsibilities, and (3) that our board of directors have a nominating and corporate governance committee that is comprised entirely of independent directors with a written charter addressing the committee’s purpose and responsibilities. Accordingly, you will not have the same protections afforded to shareholders of companies that are subject to all of these corporate governance requirements. In the event that we cease to be a “controlled company” and our Class A common stock continues to be listed on the NYSE, we will be required to comply with these provisions within the applicable transition periods.
134
Table of Contents
Composition of our Board of Directors
Our board of directors currently consists of seven directors. Our Amended Charter and Amended Bylaws will provide that the number of directors constituting our board of directors will be fixed exclusively by resolution of our board of directors from time to time, and that our board of directors will be divided into three classes, as nearly equal in number as possible, with the directors in each class serving for a three-year term, and one class being elected each year by our shareholders.
When considering whether directors have the experience, qualifications, attributes or skills, taken as a whole, to enable our board of directors to satisfy its oversight responsibilities effectively in light of our business and structure, the board of directors focuses primarily on each person’s background and experience as reflected in the information discussed in each of the directors’ individual biographies set forth above. We believe that our directors provide an appropriate mix of experience and skills relevant to the size and nature of our business.
Classified Board of Directors
Our Amended Bylaws will provide that, upon the completion of this offering, our board of directors will be divided into three classes with staggered three-year terms. Upon expiration of the term of a class of directors, directors for that class will be elected for three-year terms at the annual meeting of shareholders in the year in which that term expires. As a result, only one class of directors will be elected at each annual meeting of our shareholders, with the other classes continuing for the remainder of their respective three-year terms. Each director’s term will continue until the election and qualification of his or her successor, or his or her earlier death, resignation or removal for cause. Our directors will be divided among the three classes as follows:
| • | Class I directors, whose initial term will expire at our first annual meeting of shareholders following this offering, will consist of Mr. Tabb, Ms. Le and Mr. Littman; |
| • | Class II directors, whose initial term will expire at our second annual meeting of shareholders following this offering, will consist of Mr. Atkins and Mr. Coleman; and |
| • | Class III directors, whose initial term will expire at our third annual meeting of shareholders following this offering, will consist of Mr. Kripalani and Mr. Kimble. |
Our Amended Charter and Amended Bylaws will provide that only our board of directors may fill vacancies on our board. We expect that any additional directorships resulting from an increase in the number of directors will be distributed among the three classes so that, as nearly as possible, each class will consist of one-third of the total number of directors.
Pursuant to the terms of the Shareholders Agreement, directors nominated by the Continuing Equity Owners may be removed with or without cause at the request of the Continuing Equity Owner entitled to nominate such director in accordance with the bylaws of the Company then in effect. In all other cases, our Amended Charter provides that directors may only be removed from our board of directors for cause by the affirmative vote of at least two-thirds of the voting power of the then outstanding shares of voting stock. Following such time as when the Continuing Equity Owners cease to beneficially own at least 40% of the voting power of our outstanding shares of capital stock, any individual director may be removed with or without cause by the affirmative vote of a majority of the voting power of the outstanding shares of our capital stock.
The classification of our board of directors may have the effect of delaying or preventing changes in our control or management. See the section titled “Description of Capital Stock–Anti-Takeover Effects of Provisions of our Amended Charter and Amended Bylaws–Amended Charter and Amended Bylaw Provisions” for additional information.
135
Table of Contents
Director Independence
Prior to the consummation of this offering, our board of directors undertook a review of the independence of our directors and considered whether any director has a material relationship with us that could compromise that director’s ability to exercise independent judgment in carrying out that director’s responsibilities. Our board of directors has affirmatively determined that Ms. Le, Mr. Atkins and Mr. Kimble are each an “independent director,” as defined under the Exchange Act and the rules of the NYSE.
Committees of Our Board of Directors
Our board of directors directs the management of our business and affairs, as provided by Texas law, and conducts its business through meetings of the board of directors and standing committees. We will have a standing audit committee, nominating and corporate governance committee and compensation committee. In addition, from time to time, special committees may be established under the direction of the board of directors when necessary to address specific issues.
Audit Committee
Our audit committee will be responsible for, among other things:
| • | appointing, compensating, retaining, evaluating, terminating and overseeing our independent registered public accounting firm; |
| • | discussing with our independent registered public accounting firm their independence from management; |
| • | reviewing with our independent registered public accounting firm the scope and results of their audit; |
| • | approving all audit and permissible non-audit services to be performed by our independent registered public accounting firm; |
| • | overseeing the financial reporting process and discussing with management and our independent registered public accounting firm the interim and annual financial statements that we file with the SEC; |
| • | reviewing and monitoring our accounting principles, accounting policies, financial and accounting controls and compliance with legal and regulatory requirements; |
| • | reviewing our policies on risk assessment and risk management; |
| • | reviewing related party transactions; and |
| • | establishing procedures for the confidential anonymous submission of concerns regarding questionable accounting, internal controls or auditing matters. |
Upon the consummation of this offering, our audit committee will consist of Ms. Le, Mr. Atkins and Mr. Kimble, with Ms. Le serving as chair. Rule 10A-3 of the Exchange Act and the NYSE rules require that our audit committee have at least one independent member upon the listing of our Class A common stock, have a majority of independent members within 90 days of the date of this prospectus and be composed entirely of independent members within one year of the date of this prospectus. Our board of directors has affirmatively determined that Ms. Le, Mr. Atkins and Mr. Kimble each meet the definition of “independent director” for purposes of serving on the audit committee under Rule 10A-3 and the NYSE rules. Each member of our audit committee meets the financial literacy requirements of NYSE listing standards. In addition, our board of directors has determined that Ms. Le and Mr. Atkins will qualify as an “audit committee financial expert,” as such term is defined in
136
Table of Contents
Item 407(d)(5) of Regulation S-K. Our board of directors will adopt a new written charter for the audit committee, which will be available on our principal corporate website at www.covolt.com substantially concurrently with the consummation of this offering. The information on, or that can be accessed through, any of our websites is deemed not to be incorporated in this prospectus or to be part of this prospectus.
Nominating and Corporate Governance Committee
Our nominating and corporate governance committee will be responsible for, among other things:
| • | identifying individuals qualified to become members of our board of directors, consistent with criteria approved by our board of directors and in accordance with the terms of the Shareholders Agreement; |
| • | evaluating the overall effectiveness of our board of directors and its committees; and |
| • | reviewing developments in corporate governance compliance and developing and recommending to our board of directors a set of corporate governance guidelines and principles. |
Upon the consummation of this offering, our nominating and corporate governance committee will consist of Mr. Kripalani, Mr. Coleman and Ms. Le, with Mr. Kripalani serving as chair. Our board of directors will adopt a new written charter for the nominating and corporate governance committee, which will be available on our principal corporate website at www.covolt.com substantially concurrently with the consummation of this offering. The information on, or that can be accessed through, any of our websites is deemed not to be incorporated in this prospectus or to be part of this prospectus.
Compensation Committee
Our compensation committee will be responsible for, among other things:
| • | reviewing and approving, or recommending that our board of directors approve, the compensation of our Chief Executive Officer and other executive officers; |
| • | making recommendations to the board of directors regarding non-employee director compensation; |
| • | reviewing and approving, or making recommendations to our board of directors regarding, our incentive compensation and equity-based plans; and |
| • | appointing and overseeing any compensation consultants. |
Upon the consummation of this offering, our compensation committee will consist of Mr. Littman, Mr. Coleman and Mr. Kimble, with Mr. Littman serving as chair. Our board of directors has determined that Mr. Littman, Mr. Coleman and Mr. Kimble are “non–employee directors” as defined in Section 16b-3 of the Exchange Act. Our board of directors will adopt a new written charter for the compensation committee, which will be available on our principal corporate website at www.covolt.com substantially concurrently with the consummation of this offering. The information on, or that can be accessed through, any of our websites is deemed not to be incorporated in this prospectus or to be part of this prospectus.
Risk Oversight
Our board of directors is responsible for overseeing our risk management process. Our board of directors focuses on our general risk management strategy, the most significant risks facing us, and oversees the implementation of risk mitigation strategies by management. Our board of directors is also apprised of particular risk management matters in connection with its general oversight and approval of corporate matters and significant transactions.
137
Table of Contents
Compensation Committee Interlocks and Insider Participation
None of our executive officers serves as a member of the board of directors or compensation committee (or other committee performing equivalent functions) of any entity that has one or more members serving on our board of directors or compensation committee.
Board Diversity
Our nominating and corporate governance committee will be responsible for reviewing with the board of directors, on an annual basis, the appropriate characteristics, skills and experience required for the board of directors as a whole and its individual members. Although our board of directors does not have a formal written diversity policy with respect to the evaluation of director candidates, in its evaluation of director candidates, our nominating and corporate governance committee will consider factors including, without limitation, issues of character, integrity, judgment, potential conflicts of interest, other commitments, and diversity, and with respect to diversity, such factors as gender, race, ethnicity, experience, and area of expertise, as well as other individual qualities and attributes that contribute to the total diversity of viewpoints and experience represented on the board of directors.
Code of Ethics and Code of Conduct
Prior to the completion of this offering, we will adopt a written code of business conduct and ethics that applies to our directors, officers and employees, including our principal executive officer, principal financial officer, principal accounting officer or controller, or persons performing similar functions. A copy of the code will be posted on our website, www.covolt.com. In addition, we intend to post on our website all disclosures that are required by law or the NYSE listing standards concerning any amendments to, or waivers from, any provision of the code. The information on, or that can be accessed through, any of our websites is deemed not to be incorporated in this prospectus or to be part of this prospectus.
138
Table of Contents
EXECUTIVE AND DIRECTOR COMPENSATION
This section discusses the material components of the executive compensation program for our executive officers who are named in the “2025 Summary Compensation Table” below. Our named executive officers for our fiscal year ended December 31, 2025, which consist of our principal executive officer and our two next most highly compensated officers during the fiscal year, were as follows:
| • | Robert L. Tabb, President & Chief Executive Officer; |
| • | Samuel K. Robison, Chief Legal Officer; and |
| • | Ronnie V. Shields, Chief Financial Officer. |
This discussion may contain forward-looking statements that are based on our current plans, considerations, expectations, and determinations regarding future compensation programs. Actual compensation programs that we adopt may differ materially from currently planned programs as summarized in this discussion.
2025 Summary Compensation Table
The following table sets forth information about the compensation for each of our named executive officers for the fiscal year ended December 31, 2025.
| Name and Principal Position | Year | Salary ($) |
Bonus ($)(1) |
Stock Awards ($)(2) |
Non-Equity Incentive Plan Compensation ($)(3) |
All Other Compensation ($)(4) |
Total ($) |
|||||||||||||||||||||
| Robert L. Tabb |
2025 | 600,000 | 126,852 | 1,420,000 | 873,148 | 13,462 | 3,033,462 | |||||||||||||||||||||
| President & Chief Executive Officer |
||||||||||||||||||||||||||||
| Samuel K. Robison |
2025 | 500,000 | 72,377 | 887,500 | 727,623 | 15,616 | 2,203,116 | |||||||||||||||||||||
| Chief Legal Officer |
||||||||||||||||||||||||||||
| Ronnie V. Shields |
2025 | 350,000 | 69,398 | — | 305,602 | 11,846 | 736,846 | |||||||||||||||||||||
| Chief Financial Officer |
||||||||||||||||||||||||||||
| (1) | Amounts reflect (i) payment of a $25,000 one-time discretionary bonus to each of Messrs. Robison and Shields and (ii) discretionary annual bonuses earned by our named executive officers with respect to 2025. |
| (2) | Amounts reflect the aggregate grant date fair value of profits interests in SEC Member II, LLC (“SEC Member II”) granted to the named executive officers during 2025, computed in accordance with FASB ASC Topic 718, rather than the amounts paid to or realized by the named individual. We provide information regarding the assumptions used to calculate the value of all profits interests made to executive officers in Note 9 to our financial statements included in this prospectus. |
| (3) | Amounts reflect annual incentive bonuses earned by our named executive officers with respect to the fiscal year ended December 31, 2025. |
| (4) | Amounts reported for each of the named executive officers reflect 401(k) plan matching contributions made pursuant to our 401(k) plan. |
Narrative to 2025 Summary Compensation Table
Salaries
Each of our named executive officers receives an annual base salary to compensate the executive for services rendered to us. The annual base salary payable to each named executive officer is intended to provide a fixed component of compensation reflecting the executive’s skill set, experience, role and responsibilities.
For the fiscal year ended December 31, 2025, Messrs. Tabb, Robison and Shields had annual base salaries of $600,000, $500,000 and $350,000, respectively.
139
Table of Contents
The “Salary” column of the 2025 Summary Compensation Table above shows the actual base salaries earned by each named executive officer in the fiscal year ended December 31, 2025.
One-Time Bonuses
Each of Messrs. Robison and Shields was awarded a one-time discretionary cash bonus of $25,000 in December 2025.
In connection with this offering, we expect that each of our named executive officers will receive a one-time cash bonus equal to $750,000 for Mr. Tabb and $375,000 for each of Messrs. Robison and Shields.
2025 Annual Bonuses
Each named executive officer was eligible to earn an annual cash incentive bonus based upon the achievement of pre-determined Company performance goals for 2025, including goals related to Adjusted EBITDA, TRIR and cash flow generation, which were weighted at 70%, 15% and 15%, respectively, of the executive’s annual bonus opportunity for 2025. Each executive’s individual performance is also evaluated in determining the actual amount of their respective bonuses earned for the applicable calendar year.
The 2025 target bonuses for Messrs. Tabb, Robison and Shields were 100%, 100% and 60%, respectively, of the officer’s annual base salary. In 2025, the aggregate weighted achievement of the Company performance goals was approximately 146%. Based on this achievement, our named executive officers earned the annual bonuses in the amounts set forth above in the 2025 Summary Compensation Table in the column entitled “Non–Equity Incentive Plan Compensation.” In addition, we determined to award each named executive officer with an additional discretionary cash bonus based on their efforts for our company in 2025. These discretionary bonuses ($126,852, $47,377, and $44,398 for Messrs. Tabb, Robison and Shields, respectively) are reflected above in the “Bonus” column of the 2025 Summary Compensation Table.
Each executive’s aggregate annual bonus is paid in two equal installments following each of (x) the completion of our year-end financial statements and (y) the completion of our financial audit, subject to continued employment through the applicable payment date.
Equity Compensation
Incentive Units
Our named executive officers currently hold profits interests in SEC Member II. We refer to these profits interests as “Incentive Units.” The Incentive Units are intended to qualify as profits interests within the meaning of Internal Revenue Service Revenue Procedures 93-27 and 2001-43. The grant of Incentive Units is implemented through an “upstairs–downstairs” structure, such that our employees, including our named executive officers, hold Class BB Units of SEC Member II that mirror the economics (including vesting schedules) of corresponding units that SEC Member II holds in SEC Parent II, LLC (“SEC Parent II”).
In 2025, we granted the following Incentive Unit awards to Messrs. Tabb and Robison:
| Name | Number of Incentive Units (#) |
|||
| Robert L. Tabb |
400,000 | |||
| Samuel K. Robison |
250,000 | |||
The awards granted to Messrs. Tabb and Robison will vest (i) with respect to 66.667% of the award on December 31, 2026; and (ii) with respect to 33.333% of the award in substantially equal installments on each of
140
Table of Contents
the first four quarterly anniversaries of December 31, 2026, in each case, subject to the executive’s continued service through the applicable vesting date. Each award will vest in full upon a “Fundamental Change” (as defined in the applicable award agreement) to the extent any portion of the award is then-unvested, subject to the executive’s continued service.
All of the incentive equity awards held by our named executive officers that were unvested as of December 31, 2025 are further described below in “–Outstanding Equity Awards at Fiscal Year End.”
In January 2026, Mr. Tabb was granted an award of Incentive Units (the “Tabb 2026 Award”), 100% of which are eligible to vest upon a Fundamental Change, subject to his continued service. We expect that the Tabb 2026 Award will be amended in connection with the offering such that the Incentive Units will instead be eligible to vest with respect to 25% of the Incentive Units subject to the award on each of the first four anniversaries of January 9, 2026, subject to Mr. Tabb’s continued service through the applicable vesting date. We also expect that the Incentive Units subject to the Tabb 2026 Award will accelerate and vest in full upon a Fundamental Change, subject to Mr. Tabb’s continued service.
In addition, we expect that each Incentive Unit that is outstanding upon the consummation of this offering that is eligible to vest solely upon a Fundamental Change (other than the Incentive Units subject to the Tabb 2026 Award) will accelerate and vest in connection with this offering. We expect this to result in the accelerated vesting of 1,996,250 Incentive Units.
In connection with this offering and the Reorganization Transactions, we expect that each Incentive Unit will be recapitalized into a common unit of SEC Member II on a “value-for-value” basis based on the fair market value of the Incentive Units at the time of the closing of this offering and the common stock price in the offering, and taking into account applicable participation thresholds. Following this conversion, the common units will be subject to all other terms and conditions applicable to the underlying Incentive Units (including vesting), and following vesting will be redeemable for Common Units in CoVolt Holdings in accordance with the LLC agreement of SEC Member II.
2026 Incentive Award Plan and IPO Equity Awards
In connection with this initial public offering, we adopted (subject to shareholder approval) the 2026 Incentive Award Plan, or the 2026 Plan, in order to facilitate the grant of equity and cash incentives to directors, employees (including our named executive officers) and consultants of the Company and certain of our affiliates and to enable us to obtain and retain services of these individuals, which is essential to our long-term success. For additional information about the 2026 Plan, please see the section titled “–2026 Incentive Award Plan” below.
In connection with this offering, we expect to grant awards of restricted stock units (“RSUs”) pursuant to the 2026 Plan to each of our named executive officers, which grants will become effective upon the completion of this offering (“IPO Equity Awards”). The awards granted to our named executive officers will have a dollar-denominated value of $2,250,000 for Mr. Tabb and $1,125,000 for each of Messrs. Robison and Shields.
The IPO Equity Awards granted to our named executive officers are expected to vest as to one-third (1/3rd) of the RSUs in substantially equal annual installments on each of the first three anniversaries of the closing of the offering, subject to continued service through the applicable vesting date.
Other Elements of Compensation and Compensation Policies
Retirement Plans
We currently maintain a 401(k) retirement savings plan, or the 401(k) plan, for our employees, including our named executive officers, who satisfy certain eligibility requirements. Our named executive officers are eligible
141
Table of Contents
to participate in the 401(k) plan on the same terms as other full-time employees. The Code allows eligible employees to defer a portion of their compensation, within prescribed limits, through contributions to the 401(k) plan. Currently, we provide safe-harbor matching contributions equal to 4% of each participant’s contributions, up to 6% of such participant’s compensation, subject to limits provided in the Code. These matching contributions are fully vested as of the date on which the contribution is made. We believe that providing a vehicle for retirement savings through our 401(k) plan adds to the overall desirability of our compensation package and further incentivizes our employees, including our named executive officers, in accordance with our compensation policies.
Health and Welfare Benefits and Perquisites
All of our full-time employees, including our named executive officers, are eligible to participate in our health and welfare plans, including medical, dental and vision benefits; short-term and long-term disability insurance; basic life and AD&D insurance; voluntary life and AD&D insurance; voluntary accident, critical illness and hospital indemnity insurance; health savings accounts; limited use and dependent care flexible spending accounts; and an employee assistance plan.
No Tax Gross-Ups
We do not make gross-up payments to cover our named executive officers’ personal income taxes that may pertain to any of the compensation or perquisites paid or provided by our company.
Clawback Policy
In connection with this offering, our board of directors intends to adopt a compensation recovery policy that is compliant with the listing rules of NYSE, as required by the Dodd-Frank Act.
Outstanding Equity Awards at Fiscal Year End
The following table summarizes the number of outstanding and unvested Incentive Units held by each named executive officer as of December 31, 2025.
| Stock Awards | ||||||||||||||||
| Name | Grant Date | Vesting Commencement Date |
Number of Shares or Units of Stock That Have Not Vested (#) |
Market Value of Shares or Units of Stock That Have Not Vested ($)(1) |
||||||||||||
| Robert L. Tabb |
12/29/2023 | 09/30/2022 | 400,000 | (2) | 1,420,000 | |||||||||||
| 05/15/2025 | 12/31/2026 | 400,000 | (3) | 1,420,000 | ||||||||||||
| Samuel K. Robison |
12/29/2023 | 12/30/2023 | 441,667 | (2) | 1,567,918 | |||||||||||
| 05/15/2025 | 12/31/2026 | 250,000 | (3) | 887,500 | ||||||||||||
| Ronnie V. Shields |
04/10/2024 | 03/31/2024 | 62,500 | (4) | 221,875 | |||||||||||
| (1) | The Incentive Units are not publicly traded and, therefore, there was no ascertainable public market value for the Incentive Units as of December 31, 2025. The value of the Incentive Units is calculated as of December 31, 2025 and was determined to be $3.55 based on the number of outstanding unvested Incentive Units as of such date, and does not reflect any potential reduction in value due to applicable distribution thresholds. |
| (2) | This award vested with respect to 33.33% of the award on the applicable vesting commencement date, and vested or will vest (as applicable) (i) with respect to 41.67% of the award in substantially equal installments on each of the first ten quarterly anniversaries of the vesting commencement date and (ii) with respect to 25% of the award upon the consummation of a Fundamental Change, in each case, subject to the executive’s continued service through the applicable vesting date. In addition, this award will vest in full upon a Fundamental Change to the extent any portion of the award is then-unvested, subject to continued service. |
142
Table of Contents
| (3) | This award will vest (i) with respect to 66.667% of the award on December 31, 2026 and (ii) with respect to 33.333% of the award in substantially equal installments on each of the first four quarterly anniversaries of December 31, 2026, in each case, subject to the executive’s continued service through the applicable vesting date. In addition, this award will vest in full upon a Fundamental Change to the extent any portion of the award is then-unvested, subject to continued service. |
| (4) | This award vested (i) with respect to 45.835% of the award on March 31, 2024 and (ii) with respect to 29.165% of the award in substantially equal installments on each of the first seven quarterly anniversaries of March 31, 2024. The remaining 25% of the award will vest upon the consummation of a Fundamental Change, subject to the executive’s continued service through the applicable vesting date. |
Executive Compensation Arrangements
We have entered into employment agreements with each of Messrs. Tabb and Robison and an offer letter with Mr. Shields. We expect to amend and restate the employment agreements with each of Messrs. Tabb and Robison in connection with the IPO. The material terms of the employment agreements, as amended and restated (the “A&R Employment Agreements”), and Mr. Shields’ offer letter are described below.
Robert Tabb and Samuel Robison
The A&R Employment Agreements with Messrs. Tabb and Robison will provide for (i) “at will” employment; (ii) participation in our standard employee benefit plans; and (iii) an annual base salary of $600,000 and $500,000, respectively, pro-rated for partial years of employment. The actual base salaries earned by Messrs. Tabb and Robison for services during the last completed fiscal year are set forth above in the 2025 Summary Compensation Table.
Each of Messrs. Tabb and Robison is also eligible to earn an annual cash performance bonus based on the achievement of financial or other metrics determined by the board of directors, targeted at 100% of their respective base salaries. The payment of any annual bonus will be subject to the applicable executive’s continued employment through the applicable payment date.
Under the A&R Employment Agreements with Messrs. Tabb and Robison, on a termination of either executive’s employment by us without “cause” (as defined in the applicable A&R Employment Agreement), he will be entitled to receive: (i) continued payments of base salary for 12 months following the date of termination and (ii) reimbursement for the cost of COBRA premiums for up to 12 months. These severance payments and benefits are subject to the executive’s timely execution and non-revocation of a release of claims in our favor.
Each A&R Employment Agreement includes indefinite confidentiality and non-disparagement provisions, as well as non-competition and service provider/customer non-solicitation restrictions, both of which apply during employment and for 12 months thereafter.
Ronnie Shields Offer Letter
On December 28, 2021, we entered into an offer letter with Mr. Shields. Mr. Shields’ employment under the offer letter is at-will, and will continue until terminated at any time by either party.
Pursuant to his offer letter, Mr. Shields is (i) eligible to participate in our standard employee benefits plans; and (ii) entitled to receive an annual base salary of $250,000 per year; the actual base salary earned by Mr. Shields for services during the last completed fiscal year is set forth above in the 2025 Summary Compensation Table. In addition, Mr. Shields is eligible to earn an annual cash performance bonus, based on both individual and company performance. Pursuant to his offer letter, Mr. Shields’ target bonus opportunity is up to 60% of his annual base salary.
Director Compensation
During the fiscal year ended December 31, 2025, our non-employee directors were Stephen Atkins, Matthew Kimble, Avinash Kripalani, Rebekah Le and Louis Littman.
143
Table of Contents
During the fiscal year ended December 31, 2025, each of Stephen Atkins and Rebekah Le, who were our independent directors for 2025, was entitled to receive an annual retainer fee equal to $50,000, payable in cash. We did not grant either director an incentive equity award in 2025.
Director Compensation Table
The following table sets forth information regarding the compensation awarded to, earned by or paid to the non-employee directors who served on our board of directors during the fiscal year ended December 31, 2025.
| Name | Fees Earned or Paid in Cash ($) |
Total ($) |
||||||
| Stephen Atkins |
50,000 | 50,000 | ||||||
| Matthew Kimble |
— | — | ||||||
| Avinash Kripalani |
— | — | ||||||
| Rebekah Le |
50,000 | 50,000 | ||||||
| Louis Littman |
— | — | ||||||
The table below shows the aggregate number of unvested Incentive Units held by each non-employee director as of December 31, 2025.
| Name | Number of Unvested Incentive Units Outstanding at Fiscal Year End (#) |
|||
| Stephen Atkins |
25,000 | |||
| Matthew Kimble |
— | |||
| Avinash Kripalani |
— | |||
| Rebekah Le |
25,000 | |||
| Louis Littman |
— | |||
Post-IPO Director Compensation Program
In connection with this offering, we adopted (subject to shareholder approval) a compensation program (the “Director Compensation Program”), which will become effective upon the closing of this offering. The Director Compensation Program consists of annual retainer fees and long-term equity awards for certain of our non-employee directors (each, an “Eligible Director”) who are independent; the initial Eligible Directors will be Stephen Atkins and Rebekah Le. The material terms of the Director Compensation Program are described below.
The Director Compensation Program consists of the following components:
Cash Compensation:
| • | Annual Retainer: $60,000 |
| • | Annual Committee Chair Retainer: |
| • | Audit: $20,000 |
| • | Compensation: $15,000 |
144
Table of Contents
| • | Nominating and Corporate Governance: $12,500 |
| • | Non-Executive Chair Retainer: $100,000 |
The annual cash retainers will be paid in quarterly installments in arrears. Annual cash retainers will be pro-rated for any partial calendar quarter of service.
Equity Compensation:
| • | 2026 Awards: Each Eligible Director will receive an RSU award in connection with the completion of this offering (the “2026 Director Awards”). The dollar-denominated value of each award is $100,000 and the aggregate dollar-denominated value of these awards is $200,000. The aggregate number of shares of our common stock that will be subject to the 2026 Director Awards will be determined based on the initial public offering price per share of our common stock in this offering. |
The 2026 Director Awards will vest in full on the earlier to occur of the first anniversary of the closing of this offering and the date of the annual meeting following the closing of this offering, subject to continued service through the applicable vesting date.
| • | Initial Awards: Each Eligible Director who is initially elected or appointed to serve on our board of directors after the completion of this offering automatically will be granted, on the date of such Eligible Director’s election or appointment to the board, an RSU award with an aggregate value of $100,000, prorated based on the number of days from the immediately preceding date of an annual meeting of stockholders (or, if none, the completion of this offering). The number of RSUs subject to the award will be determined by dividing the value of the award by the price per share of the Company’s common stock on the applicable grant date. |
Each Initial Award will vest in full on the earlier to occur of the first anniversary of the grant date and the date of the next annual meeting following the grant date, subject to continued service.
| • | Annual Awards: An Eligible Director who is serving on our board of directors as of the date of an annual meeting of our shareholders (beginning with calendar year 2027) automatically will be granted, on the date of such annual meeting, an RSU award with an aggregate value of $100,000. The number of RSUs subject to the award will be determined by dividing the value of the award by the price per share of the Company’s common stock on the applicable grant date. |
Each Annual Award will vest in full on the earlier to occur of the first anniversary of the grant date and the date of the next annual meeting following the grant date, subject to continued service.
In addition, each equity award granted to an Eligible Director under the Director Compensation Program will vest in full immediately prior to the occurrence of a “change in control” (as defined in the 2026 Plan). Compensation under the Director Compensation Program will be subject to the annual limits on non-employee director compensation set forth in the 2026 Plan.
Equity Compensation Plans
The following summarizes the material terms of the 2026 Plan, which is the long-term incentive compensation plan in which our named executive officers will be eligible to participate following the completion of this offering. Our board of directors is still in the process of developing, approving and implementing the 2026 Plan and, accordingly, this summary is subject to change.
145
Table of Contents
2026 Incentive Award Plan
In connection with this offering, we adopted (subject to shareholder approval) the 2026 Plan, under which we may grant equity and cash incentive awards to eligible service providers in order to attract, motivate and retain the talent for which we compete, subject to shareholder approval. The material terms of the 2026 Plan are summarized below.
Eligibility and Administration. Our employees, consultants and directors and employees and consultants of our affiliates will be eligible to receive awards under the 2026 Plan. Following the completion of this offering, the 2026 Plan will be administered by our board of directors with respect to awards to non-employee directors and by our compensation committee with respect to other participants, each of which may delegate its duties and responsibilities to committees of our directors and/or officers (referred to collectively as the plan administrator), subject to the limitations imposed under the 2026 Plan, Section 16 of the Exchange Act, stock exchange rules and other applicable laws. The plan administrator will have the authority to take all actions and make all determinations under the 2026 Plan, to interpret the 2026 Plan and award agreements and to adopt, amend and repeal rules for the administration of the 2026 Plan as it deems advisable. The plan administrator will also have the authority to determine which eligible service providers receive awards, grant awards and set the terms and conditions of all awards under the 2026 Plan, including any vesting and vesting acceleration provisions, subject to the conditions and limitations in the 2026 Plan.
Limitation on Awards and Shares Available. The initial aggregate number of shares of our common stock that will be available for issuance under the 2026 Plan will be equal to 7% of the aggregate number of shares of our Class A common stock and Class B common stock outstanding as of immediately following the completion of this offering (which is expected to be shares, assuming an initial public offering price of $ per share, which is the midpoint of the price range set forth on the cover page of this prospectus). In addition, the number of shares of our common stock available for issuance under the 2026 Plan will be subject to an annual increase on the first day of each calendar year beginning on and including January 1, 2027 and ending on and including January 1, 2036, equal to the lesser of (A) 3% of the aggregate number of shares of our Class A common stock and Class B common stock outstanding on the final day of the immediately preceding calendar year and (B) such smaller number of shares as is determined by our board of directors.
The maximum number of shares that may be issued pursuant to the exercise of incentive stock options, or ISOs, granted under the 2026 Plan, will be 100,000,000. Any shares issued pursuant to the 2026 Plan may consist, in whole or in part, of authorized and unissued common stock, treasury common stock or common stock purchased on the open market.
If an award under the 2026 Plan expires, lapses or is terminated, exchanged for or settled in cash, any shares subject to such award (or portion thereof) may, to the extent of such expiration, lapse, termination or cash settlement, be used again for new grants under the 2026 Plan. Shares tendered or withheld to satisfy the exercise price or tax withholding obligation for any award will not reduce the shares available for grant under the 2026 Plan. Further, the payment of dividend equivalents in cash in conjunction with any awards under the 2026 Plan will not reduce the shares available for grant under the 2026 Plan. However, the following shares may not be used again for grant under the 2026 Plan: (i) shares subject to stock appreciation rights, or SARs, that are not issued in connection with the stock settlement of the SAR on exercise, and (ii) shares purchased on the open market with the cash proceeds from the exercise of options.
Awards granted under the 2026 Plan upon the assumption of, or in substitution for, awards authorized or outstanding under a qualifying equity plan maintained by an entity with which we enter into a merger or similar corporate transaction will not reduce the shares available for grant under the 2026 Plan but will count against the maximum number of shares that may be issued upon the exercise of ISOs.
146
Table of Contents
The 2026 Plan provides that the sum of any cash compensation and the aggregate grant date fair value (determined as of the date of the grant under ASC Topic 718, or any successor thereto) of all awards granted to a non-employee director as compensation for services as a non-employee director during any fiscal year, or director limit, may not exceed an amount equal to $750,000 which limits shall not apply to the compensation for any non-employee director who serves in any capacity in addition to that of a non-employee director for which he or she receives additional compensation or any compensation paid prior to the calendar year following the calendar year in which the 2026 Plan becomes effective.
Awards. The 2026 Plan provides for the grant of stock options, including ISOs and nonqualified stock options, or NSOs, SARs, restricted stock, dividend equivalents, restricted stock units, or RSUs, and other stock or cash based awards. Certain awards under the 2026 Plan may constitute or provide for payment of “nonqualified deferred compensation” under Section 409A of the Code, which may impose additional requirements on the terms and conditions of such awards. All awards under the 2026 Plan will be evidenced by award agreements, which will detail the terms and conditions of the awards, including any applicable vesting and payment terms and post-termination exercise limitations. Awards other than cash awards generally will be settled in shares of our common stock, but the applicable award agreement may provide for cash settlement of any award. A brief description of each award type follows.
| • | Stock Options and SARs. Stock options provide for the purchase of shares of our common stock in the future at an exercise price set on the grant date. ISOs, in contrast to NSOs, may provide tax deferral beyond exercise and favorable capital gains tax treatment to their holders if certain holding period and other requirements of the Code are satisfied. SARs entitle their holder, upon exercise, to receive from us an amount equal to the appreciation of the shares subject to the award between the grant date and the exercise date. Unless otherwise determined by our board, the exercise price of a stock option or SAR may not be less than 100% of the fair market value of the underlying share on the grant date (or 110% in the case of ISOs granted to certain significant shareholders), except with respect to certain substitute awards granted in connection with a corporate transaction. The term of a stock option or SAR may not be longer than ten years (or five years in the case of ISOs granted to certain significant shareholders). Conditions applicable to stock options and/or SARs may be based on continuing service, the attainment of performance goals and/or such other conditions as the plan administrator may determine. |
| • | Restricted Stock and RSUs. Restricted stock is an award of nontransferable shares of our common stock that are subject to certain vesting conditions and other restrictions. RSUs are contractual promises to deliver shares of our common stock in the future, which may also remain forfeitable unless and until specified conditions are met and may be accompanied by the right to receive the equivalent value of dividends paid on shares of our common stock prior to the delivery of the underlying shares (i.e., dividend equivalent rights). The plan administrator may provide that the delivery of the shares underlying RSUs will be deferred on a mandatory basis or at the election of the participant. The terms and conditions applicable to RSUs will be determined by the plan administrator, subject to the conditions and limitations contained in the 2026 Plan. Conditions applicable to restricted stock and RSUs may be based on continuing service, the attainment of performance goals and/or such other conditions as the plan administrator may determine. |
| • | Other Stock or Cash Based Awards. Other stock or cash based awards are awards of cash, fully vested shares of our common stock and other awards valued wholly or partially by referring to, or otherwise based on, shares of our common stock. Other stock or cash based awards may be granted to participants and may also be available as a payment form in the settlement of other awards, as standalone payments and as payment in lieu of compensation to which a participant is otherwise entitled. |
| • | Dividend Equivalents. Dividend equivalents represent the right to receive the equivalent value of dividends paid on shares of our common stock and may be granted alone or in tandem with awards other than stock |
147
Table of Contents
| options or SARs. Dividend equivalents are credited as of the dividend record dates during the period between the date an award is granted and the date such award vests, is exercised, is distributed or expires, as determined by the plan administrator. Dividend equivalents payable with respect to an award prior to the vesting of such award instead will be paid out to the participant only to the extent that the vesting conditions are subsequently satisfied and the award vests. |
Certain Transactions. The plan administrator has broad discretion to take action under the 2026 Plan, as well as make adjustments to the terms and conditions of existing and future awards, to prevent the dilution or enlargement of intended benefits and facilitate necessary or desirable changes in the event of certain transactions and events affecting our common stock, such as stock dividends, stock splits, mergers, acquisitions, consolidations and other corporate transactions. In addition, in the event of certain non-reciprocal transactions with our shareholders known as “equity restructurings,” the plan administrator will make equitable adjustments to the 2026 Plan and outstanding awards. In the event of a change in control (as defined in the 2026 Plan), to the extent that the surviving entity declines to continue, convert, assume or replace outstanding awards, then all such awards will become fully vested and exercisable in connection with the transaction. Upon or in anticipation of a change in control, the plan administrator may cause any outstanding awards to terminate at a specified time in the future and give the participant the right to exercise such awards during a period of time determined by the plan administrator in its sole discretion. Individual award agreements may provide for additional accelerated vesting and payment provisions.
Repricing. Our board of directors may, without approval of the shareholders, reduce the exercise price of any stock option or SAR, or cancel any stock option or SAR in exchange for cash, other awards or stock options or SARs with an exercise price per share that is less than the exercise price per share of the original stock options or SARs.
Plan Amendment and Termination. Our board of directors may amend or terminate the 2026 Plan at any time; however, no amendment, other than an amendment that increases the number of shares available under the 2026 Plan, may materially and adversely affect an award outstanding under the 2026 Plan without the consent of the affected participant, and shareholder approval will be obtained for any amendment to the extent necessary to comply with applicable laws. The 2026 Plan will remain in effect until terminated by the plan administrator in accordance with the 2026 Plan. No awards may be granted under the 2026 Plan after its termination.
Foreign Participants, Claw-back Provisions, Transferability and Participant Payments. The plan administrator may modify award terms, establish subplans and/or adjust other terms and conditions of awards, subject to the share limits described above, in order to facilitate grants of awards subject to the laws and/or stock exchange rules of countries outside of the United States. All awards will be subject to any Company clawback policy as set forth in such clawback policy or the applicable award agreement. Awards under the 2026 Plan are generally non-transferrable, except by will or the laws of descent and distribution, or, subject to the plan administrator’s consent, pursuant to a domestic relations order, and are generally exercisable only by the participant. With regard to tax withholding, exercise price and purchase price obligations arising in connection with awards under the 2026 Plan, the plan administrator may, in its discretion, accept cash or check, shares of our common stock that meet specified conditions, a “market sell order” or such other consideration as it deems suitable.
148
Table of Contents
PRINCIPAL AND SELLING SHAREHOLDERS
The following table sets forth information with respect to the beneficial ownership of our Class A common stock and Class B common stock as of , 2026, and as adjusted to reflect the filing and effectiveness of our Amended Charter and adoption of our Amended Bylaws upon the closing of this offering, in each case as if such event had occurred on , 2026, and to give effect to this offering, for:
| • | each person known by us to beneficially own more than 5% of our Class A common stock or Class B common stock; |
| • | each of our named executive officers and directors; |
| • | all of our executive officers and directors as a group; and |
| • | each selling shareholder. |
Beneficial ownership of Class A common stock and Class B common stock is determined in accordance with the rules of the SEC. Under these rules, beneficial ownership includes any shares as to which the individual or entity has sole or shared voting power or investment power. In computing the number of shares beneficially owned by an individual or entity and the percentage ownership of that person, warrants or other rights held by such person that are currently exercisable or will become exercisable within 60 days of are considered outstanding, although these shares are not considered outstanding for purposes of computing the percentage ownership of any other person. The applicable percentage ownership after this offering is based on shares of our Class A common stock and shares of our Class B common stock outstanding immediately following the completion of this offering, assuming that the underwriters will not exercise their option to purchase additional shares of Class A common stock and assuming the issuance of up to shares of Class A common stock at the closing of this offering. See “Organizational Structure.”
The following table does not reflect any shares of Class A common stock that may be purchased pursuant to our directed share program described under “Underwriting–Directed Share Program.”
Unless otherwise indicated, the address of all listed shareholders is 711 Louisiana St., Suite ST 2500, Houston, TX 77002. Each of the shareholders listed below has sole voting and investment power with respect to the shares beneficially owned by such shareholder unless noted otherwise, subject to community property laws where applicable.
| Class A Common Stock Beneficially Owned |
Class B Common Stock Beneficially Owned(1) |
|||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Prior to the Offering |
Shares to Be Sold (No Exercise Option) |
Shares to Be Sold (With Full Exercise Option) |
After the Offering (No Exercise Option) |
After the Offering (With Full Exercise Option) |
Prior to the Offering |
After the Offering (No Exercise Option) |
After the Offering (With Full Exercise Option) |
Before Offering |
After Giving Effect to the Offering |
|||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Name and Address of Beneficial Owner |
Shares | % | Shares | % | Shares | % | Shares | % | Shares | % | Shares | % | Shares | % | Shares | % | Percentage of total voting power |
|||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Greater than 5% Shareholders |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Entities affiliated with Davidson Kempner(2) |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Entities affiliated with Man Group(3) |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| ASSF Holdings, L.P.(4) |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Avenue MIC Power Opportunities Master Fund, L.P.(5) |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| SEC Member II, LLC(6) |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Named Executive Officers and Directors |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Robert L. Tabb |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Samuel K. Robison |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
149
Table of Contents
| Class A Common Stock Beneficially Owned |
Class B Common Stock Beneficially Owned(1) |
|||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Prior to the Offering |
Shares to Be Sold (No Exercise Option) |
Shares to Be Sold (With Full Exercise Option) |
After the Offering (No Exercise Option) |
After the Offering (With Full Exercise Option) |
Prior to the Offering |
After the Offering (No Exercise Option) |
After the Offering (With Full Exercise Option) |
Before Offering |
After Giving Effect to the Offering |
|||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Name and Address of Beneficial Owner |
Shares | % | Shares | % | Shares | % | Shares | % | Shares | % | Shares | % | Shares | % | Shares | % | Percentage of total voting power |
|||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Ronnie V. Shields |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Avinash Kripalani |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Stephen W. Atkins |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Sean K. Coleman |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Matthew Kimble |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Rebekah B. Le |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Louis Littman |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| All directors and executive officers as a group (10 individuals) |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Selling Shareholders |
||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| * | Less than 1% |
| (1) | Each share of Class B common stock will be cancelled upon the redemption of one Common Unit for one share of Class A common stock. Each share of Class B common stock entitles the registered holder to one vote per share on all matters presented to shareholders for a vote generally. Holders of Class A and Class B common stock will vote together as a single class on all matters to be presented to shareholders for their vote or approval, except as otherwise required by applicable law or the amended and restated certificate of formation. Our Class B common stock does not have economic rights. See “Description of Capital Stock.” |
| (2) | Consists of (i) shares of Class A common stock held by DK Swan Equity Holder, LLC (“DK Swan”), (ii) shares of Class A common stock held by Davidson Kempner International Master Fund Ltd. (“DKIMF”), (iii) shares of Class A common stock held by Davidson Kempner Institutional Partners, L.P. (“DKIP”) and (iv) shares of Class A common stock held by Davidson Kempner Distressed Opportunities International Ltd. (“DKDOI” and collectively with DK Swan, DKIMF and DKIP, the “DK Funds”). Davidson Kempner Capital Management LP (“DKCM”) is a Delaware limited partnership and a registered investment adviser with the SEC and is responsible for the voting and investment decisions of the DK Funds. DKCM GP LLC, a Delaware limited liability company, is the general partner of DKCM. The partners of DKCM are Anthony A. Yoseloff, Conor Bastable, Morgan P. Blackwell, Patrick W. Dennis, Gabriel T. Schwartz, Zachary Z. Altschuler, Joshua D. Morris, Suzanne K. Gibbons, Gregory S. Feldman, Melanie Levine, James Li, Michael Chiaramonte, Sona Gohel, Jeffrey Hurwitz and Andrew Tan. Anthony A. Yoseloff, through DKCM, is responsible for the voting and investment decisions relating to the securities reported herein, and each of the foregoing, other than funds covered hereby, disclaims any beneficial ownership of such securities. The principal business office of the foregoing entities and individuals is 9 W. 57th St., Floor 29, New York, NY 10019. |
| (3) | Consists of (i) shares of Class A common stock held by Bardin Hill Opportunistic Credit Master ECI Fund LP (“BH Opportunistic Credit Master”), (ii) shares of Class A common stock held by HDML Fund II LLC (“HDML Fund”) and (iii) shares of Class A common stock held by Bardin Hill NE Fund LP (“BH NE Fund” and collectively with BH Opportunistic Credit Master and HDML Fund, the “BH Funds”). Man Investment Partners (US) LP is the investment manager of the BH Funds. Investment and voting decisions of Man Investment Partners (US) LP are made by one or more of its portfolio managers, including Jason Dillow, John Greene and Pratik Desai, each of whom has individual decision-making authority. As such, each of the foregoing may be deemed to share beneficial ownership of the securities held by the BH Funds, but each disclaims beneficial ownership. The address of the principal office of the foregoing is c/o Man Investment Partners (US) LP, 299 Park Avenue, 24th Floor, New York, NY 10171. |
| (4) | Eyre Street Capital, LLC is the managing member of ESC Sustainable Solutions Partners, LLC, which is the general partner of ASSF Holdings, L.P. (“ASSF”). Sean Coleman and Jamie Devine serve on the investment committee of Eyre Street Capital, LLC. As a result, each of the foregoing may be deemed to share beneficial ownership of the securities held by ASSF. Each of the foregoing expressly disclaims beneficial ownership of the Class A common stock and Class B common stock. The principal business office of the foregoing entities and individuals is 666 Third Avenue Suite 600, New York, NY 10017. |
| (5) | Avenue MIC Power Opportunities Fund GenPar, LLC is the general partner of Avenue MIC Power Opportunities Master Fund, L.P. GL MIC Power Opportunities Partners, LLC is the sole member of Avenue MIC Power Opportunities Fund GenPar, LLC. Marc Lasry is the Managing Member of GL MIC Power Opportunities Partners, LLC, and as a result, has sole voting and dispositive power with respect to the securities held by Avenue MIC Power Opportunities Master Fund, L.P. Mr. Lasry expressly disclaims beneficial ownership of the Class A common stock and Class B common stock. The principal business office of the foregoing entities and individuals is 11 West 42nd Street, 9th Floor, New York, NY 10036. |
| (6) | SEC Member II, LLC is managed by a board of managers composed of Matthew Kimble, Avinash Kripalani, Louis Littman, Sean Coleman, Robert Tabb, Stephen Atkins, and Rebekah Le, each of whom serves on our board of directors. |
150
Table of Contents
CERTAIN RELATIONSHIPS AND RELATED PARTY TRANSACTIONS
The following includes a summary of transactions since January 1, 2024 and any currently proposed transactions, to which we were or are to be a participant, in which (i) the amount involved exceeded or will exceed $120,000; and (ii) any of our directors, executive officers, or holders of more than 5% of our capital stock, or any affiliate or member of the immediate family of the foregoing persons or entities, had or will have a direct or indirect material interest, other than compensation and other arrangements that are described under “Executive and Director Compensation.” We believe the terms obtained or consideration that we paid or received, as applicable, in connection with the transactions described below were comparable to terms available or the amounts that we would pay or receive, as applicable, in arm’s-length transactions.
Transactions
In connection with the Reorganization Transactions, we will engage in certain transactions with certain of our directors, executive officers and other persons and entities which are or will become holders of 5% or more of our voting securities upon the consummation of the Reorganization Transactions. These transactions are described in “Organizational Structure.” We intend to use the net proceeds from this offering (including any net proceeds from any exercise of the underwriters’ option) to purchase newly issued Common Units for approximately $ million directly from CoVolt Holdings at a price per unit equal to the initial public offering price per share of Class A common stock in this offering less the underwriting discount, and to purchase Common Units from certain of the Continuing Equity Owners for cash.
Distributions to Parent
CoVolt Holdings is a wholly owned subsidiary of SEC Intermediate, LLC (the “Parent”). Prior to the consummation of the Reorganization Transactions, SEC Intermediate, LLC will merge with and into SEC Parent II, LLC, with SEC Parent II, LLC surviving such merger, and SEC Parent II, LLC will then liquidate with the holders of equity interests in SEC Parent II, LLC receiving equity interests in CoVolt Holdings (together, the “Simplification Transactions”). Following the Simplification Transactions, CoVolt Holdings will no longer have a parent entity. During the year ended December 31, 2025, CoVolt Holdings made distributions to the Parent of $6.0 million. The distributions were approved by the Board of Directors on the respective dates of the distributions and were funded from cash on hand. The distributions were non-interest bearing and were recorded as a reduction to members’ equity. In January and April 2026, CoVolt Holdings made additional cash distributions to the Parent of approximately $8.0 million and $23.5 million, respectively. In July 2026, the Company made additional cash distributions to the Parent of approximately $30.0 million. In August 2026, the Company made additional cash distributions to the Parent of approximately $31.0 million.
Reorganization Transactions
In connection with the consummation of this offering, we will complete a series of reorganization transactions, including: (i) the amendment and restatement of the CoVolt Holdings LLC Agreement to, among other things, effect a recapitalization in which all existing ownership interests in CoVolt Holdings are converted into one class of Common Units; (ii) the amendment and restatement of the CoVolt Power, Inc. certificate of formation to, among other things, authorize two classes of common stock; (iii) CoVolt Power, Inc.’s designation as managing member of CoVolt Holdings; (iv) the merger of SEC Intermediate, LLC with and into SEC Parent II, LLC, with SEC Parent II, LLC surviving such merger, followed by the liquidation of SEC Parent II, LLC; (v) the amendment and restatement of the SEC Member II, LLC Agreement to, among other things, effect a recapitalization in which all existing membership interests of SEC Member II, LLC are converted into one class of common units; (vi) the Blocker Mergers, pursuant to which each Blocker Corporation will merge with and into CoVolt Power, Inc., with
151
Table of Contents
the Blocker Shareholders receiving shares of Class A common stock; (vii) the contribution by an affiliate of Avenue Capital Group of its Common Units to CoVolt Power, Inc. in exchange for shares of Class A common stock; (viii) CoVolt Power, Inc.’s acquisition of Common Units held by certain of the Continuing Equity Owners in exchange for an equal number of shares of Class A common stock or, in the case of certain Continuing Equity Owners, cash; and (ix) CoVolt Power, Inc.’s issuance of Class B common stock to the Continuing Equity Owners in exchange for a nominal cash contribution made by such Continuing Equity Owners, resulting in a combined company organized in an Up-C structure. Further, in connection with the Reorganization Transactions, CoVolt Holdings made a distribution to fund SEC Parent II’s full redemption of the 2023 Preferred on August 7, 2026. The distribution was funded using amounts other than the proceeds of this offering. See “Organizational Structure” for additional information.
Tax Receivable Agreement
As a result of our post-offering organizational structure, we expect to obtain Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions that may have the effect of reducing the amounts we would otherwise pay in the future to various tax authorities and may also decrease gains (or increase losses) on future dispositions of certain assets to the extent tax basis is allocated to those assets.
In connection with the completion of this offering, we will enter into the Tax Receivable Agreement with CoVolt Holdings and the TRA Holders. The Tax Receivable Agreement will provide for the payment by us to the TRA Holders of % of the amount of cash tax savings, if any, that we actually realize, or in some circumstances are deemed to realize, as a result of the Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions. CoVolt Holdings and its applicable subsidiaries will have an election under Section 754 of the Code in effect for each taxable year in which a redemption or exchange of Common Units for shares of our Class A common stock or cash occurs. Assuming no material changes in the relevant tax laws and that we earn sufficient taxable income to realize all tax benefits that are subject to the Tax Receivable Agreement, we expect that the tax savings associated with the Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions would aggregate to approximately $ million over years from the date of this offering based on the initial public offering price of $ per share of our Class A common stock, and assuming all redemptions or exchanges would occur immediately after the initial public offering for the remaining ownership of CoVolt Holdings not acquired by us, which is assumed to occur on , 2026 for purposes of the pro forma information presented herein and elsewhere in this prospectus. Under such scenario, assuming future payments are made on the date each relevant tax return is due, without extensions, we would be required to pay approximately % of such amount, or approximately $ million, over the year period from the date of this offering, to the TRA Holders. These Tax Receivable Agreement payments are not conditioned upon any continued ownership interest in either CoVolt Holdings or CoVolt Power, Inc. by any TRA Holder. The rights of each TRA Holder under the Tax Receivable Agreement are assignable regardless of whether the underlying Common Units are also assigned. In general, the TRA Holders’ rights under the Tax Receivable Agreement may not be assigned, sold, pledged or otherwise alienated to any person, other than certain permitted transferees, without such person becoming a party to the Tax Receivable Agreement and agreeing to succeed to the applicable TRA Holders’ interest therein.
The actual Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions, as well as any amounts paid to the TRA Holders under the Tax Receivable Agreement, will vary depending on a number of factors, including:
| • | the price of shares of our Class A common stock at the time of redemptions or exchanges—the Basis Adjustments, as well as any related increase in any tax deductions, are directly related to the price of shares of our Class A common stock at the time of each redemption or exchange; |
152
Table of Contents
| • | the timing of any subsequent redemptions or exchanges—for instance, the increase in any tax deductions will vary depending on the fair value, which may fluctuate over time, of the depreciable or amortizable assets of CoVolt Holdings and certain of its direct and indirect subsidiaries at the time of each redemption, exchange or distribution (or deemed distribution) as well as the amount of remaining existing tax basis at the time of such redemption, exchange or distribution (or deemed distribution); |
| • | the extent to which such redemptions or exchanges are taxable—if a redemption or exchange is not taxable for any reason, certain of the increased tax deductions will not be available; |
| • | the extent to which such Basis Adjustments are immediately deductible—we may be permitted to immediately expense a portion of the Basis Adjustments attributable to a redemption or exchange, which could significantly accelerate the timing of our realization of the associated tax benefits; and |
| • | the extent to which CoVolt Holdings and its subsidiaries acquire or construct assets following this offering, which could result in additional Exchange Existing Basis and, as a result, could significantly increase amounts payable under the Tax Receivable Agreement; and |
| • | the amount and timing of our income—the Tax Receivable Agreement generally will require us to pay % of the amount of cash tax savings as and when such cash tax savings are treated as realized under the terms of the Tax Receivable Agreement. If we do not have sufficient taxable income to realize any of the applicable tax benefits, we generally will not be required (absent a change of control or other circumstances requiring an early termination payment) to make payments under the Tax Receivable Agreement for that taxable year because no tax benefits will have been actually realized. However, any tax benefits that do not result in realized tax benefits in a given taxable year may generate tax attributes that may be used to generate tax benefits in previous or future taxable years. The use of any such tax attributes will result in payments under the Tax Receivable Agreement. |
For purposes of the Tax Receivable Agreement, cash savings in income taxes will be computed by comparing our actual income tax liability to the amount of such taxes that we would have been required to pay had there been no Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions; provided that, for purposes of determining cash savings with respect to state and local income taxes an assumed tax rate will be used. The Tax Receivable Agreement will generally apply to each of our taxable years, beginning with the first taxable year ending after the completion of this offering. There is no maximum term for the Tax Receivable Agreement, although, as discussed further below, the Tax Receivable Agreement may be terminated by us pursuant to an early termination procedure or upon the occurrence of certain events, in each case, that requires us to pay the TRA Holders an agreed upon amount equal to the estimated present value of the remaining payments to be made under the agreement (calculated based on certain assumptions, including regarding tax rates and use of the Basis Adjustments, Blocker Transferred Basis, Existing Basis, Exchange Existing Basis and Interest Deductions).
The payment obligations under the Tax Receivable Agreement are obligations of us and not CoVolt Holdings. Although the actual timing and amount of any payments that may be made under the Tax Receivable Agreement will vary, it is expected that the payments that we may be required to make to the TRA Holders could be substantial. Any payments made by us to the TRA Holders under the Tax Receivable Agreement will generally reduce the amount of overall cash flow that might have otherwise been available to us and, to the extent that we are unable to make payments under the Tax Receivable Agreement for any reason, the unpaid amounts generally will be deferred and will accrue interest until paid by us; provided, however, that nonpayment for a specified period may constitute a material breach of a material obligation under the Tax Receivable Agreement and, therefore, may accelerate payments due under the Tax Receivable Agreement, which could be substantial.
153
Table of Contents
We anticipate funding ordinary course payments under the Tax Receivable Agreement from cash flow from operations of CoVolt Holdings and its subsidiaries, available cash or available borrowings under debt agreements or any future debt agreements.
Decisions made by us in the course of running our business, such as with respect to mergers, asset sales, other forms of business combinations or other changes in control, may influence the timing and amount of payments that we are required to make to a TRA Holder under the Tax Receivable Agreement. For example, the earlier disposition of assets following an exchange or acquisition transaction will generally accelerate payments under the Tax Receivable Agreement and increase the present value of such payments.
The Tax Receivable Agreement provides that if (i) we materially breach any of our material obligations under the Tax Receivable Agreement, (ii) certain mergers, asset sales, other forms of business combination, or other changes of control were to occur after the consummation of the Transactions, or (iii) we elect an early termination of the Tax Receivable Agreement, then our obligations, or our successor’s obligations, under the Tax Receivable Agreement would accelerate and become due and payable, based on certain assumptions, including an assumption that we would have sufficient taxable income to fully use all potential future tax benefits that are subject to the Tax Receivable Agreement. In those circumstances, TRA Holders would be deemed to exchange any remaining outstanding Common Units for our Class A common stock and the TRA Holders generally would be entitled to payments under the Tax Receivable Agreement resulting from such deemed exchanges. We may elect to completely terminate the Tax Receivable Agreement early only with the written approval of each of a majority of our “independent directors” (within the meaning of the listing rules). The amount due and payable in those circumstances is based on the present value (at a discount rate of SOFR plus basis points) of projected future tax benefits that are based on certain assumptions, including an assumption that we would have sufficient taxable income to fully use all potential future tax benefits that are subject to the Tax Receivable Agreement. Based on such assumptions, if we were to exercise our termination right, or the Tax Receivable Agreement is otherwise terminated, immediately following the date of this offering, the aggregate amount of the termination payments would be approximately $ .
As a result of the foregoing, we could be required to make an immediate cash payment, possibly significantly in advance of the actual realization, if any, of such future cash tax savings. We also could be required to make cash payments to the TRA Holders that are greater than % of the actual benefits we ultimately realize in respect of the tax benefits that are subject to the Tax Receivable Agreement. In these situations, our obligations under the Tax Receivable Agreement could have a substantial negative impact on our liquidity and could have the effect of deferring or preventing certain mergers, asset sales, other forms of business combination, or other changes of control. There can be no assurance that we will be able to finance our obligations under the Tax Receivable Agreement.
Payments under the Tax Receivable Agreement will be based on the tax reporting positions that we determine, which are complex and factual in nature, and the IRS or another taxing authority may challenge all or any part of the Basis Adjustments, as well as other tax positions that we take, and a court may sustain such a challenge. We will not be reimbursed for any cash payments previously made to the TRA Holders pursuant to the Tax Receivable Agreement if any tax benefits initially claimed by us are subsequently challenged by a taxing authority and ultimately disallowed. Instead, any excess cash payments made by us to a TRA Holder will be netted against future cash payments, if any, that we might otherwise be required to make under the terms of the Tax Receivable Agreement to such TRA Holders. However, a challenge to any tax benefits initially claimed by us may not arise for a number of years following the initial time of such payment or, even if challenged early, such excess cash payment may be greater than the amount of future cash payments, if any, that we might otherwise be required to make under the terms of the Tax Receivable Agreement and, as a result, there might not be future cash payments from which to net against. As a result, it is possible we could make cash payments under the Tax Receivable Agreement that are substantially greater than % of our actual cash tax savings.
154
Table of Contents
We will have full responsibility for, and sole discretion over, all of our and CoVolt Holdings’ tax matters, including the filing and amendment of all tax returns and claims for refund and defense of all tax contests, subject to certain participation and approval rights held by certain TRA Holders. If the outcome of any such challenge would reasonably be expected to materially affect the rights and obligations of TRA Holders under the Tax Receivable Agreement, then our ability to settle such challenges may be restricted by the rights of the TRA Holders pursuant to the Tax Receivable Agreement, and such restrictions apply for as long as the Tax Receivable Agreement remains in effect. The interests of the TRA Holders in any such challenge may differ from or conflict with our interests and your interests, and the TRA Holders may exercise their consent rights relating to any such challenge in a manner adverse to our interests and your interests.
Under the Tax Receivable Agreement, we are required to provide each TRA Holder that holds an interest in the Tax Receivable Agreement and to which a tax benefit or detriment is attributable with a schedule showing the calculation of payments that are due under the Tax Receivable Agreement with respect to each taxable year with respect to which a payment obligation to such holder arises within a specified period of time after filing our U.S. federal income tax return for such taxable year. This calculation will be based upon the advice of our tax advisors. Payments are generally due under the Tax Receivable Agreement within a specified period of time following the filing of our tax return for the taxable year with respect to which the payment obligation arises, although interest on such payments will begin to accrue at a rate of a SOFR plus basis points from the due date (without extensions) of such tax return. Some late payments that may be made under the Tax Receivable Agreement will continue to accrue interest at a rate of SOFR plus basis points until such payments are made, including any late payments that we may subsequently make because we did not have enough available cash to satisfy our payment obligations at the time at which they originally arose.
CoVolt Holdings LLC Agreement
In connection with the consummation of the Reorganization Transactions, we and the Continuing Equity Owners will enter into the CoVolt Holdings LLC Agreement. The following is a description of the material terms of the CoVolt Holdings LLC Agreement to be in effect upon consummation of the Reorganization Transactions.
Appointment as managing member. Under the CoVolt Holdings LLC Agreement, CoVolt Power, Inc. will become a member and the sole managing member of CoVolt Holdings. As the sole managing member, CoVolt Power, Inc. will be able to control all of the day-to-day business affairs and decision-making of CoVolt Holdings without the approval of any other member. As such, we, through our officers and directors, will be responsible for all operational and administrative decisions of CoVolt Holdings and daily management of CoVolt Holdings’ business.
Distributions. The CoVolt Holdings LLC Agreement will require “tax distributions” to be made by CoVolt Holdings to its members. Tax distributions will be made on a quarterly basis to each member of CoVolt Holdings, including us, pro rata in accordance with economic interests and based on such member’s allocable share of the taxable income of CoVolt Holdings and an assumed tax rate that will be determined by us. Our share of tax distributions shall be in amounts that permit us to satisfy our tax liabilities and our ordinary course payment obligations under the Tax Receivable Agreement but may be significantly in excess of those amounts.
Common Unit Redemption Right. Under the CoVolt Holdings LLC Agreement, each holder of Common Units will, subject to certain limitations, have the right (the “Redemption Right”) to cause CoVolt Holdings to redeem all or a portion of its Common Units for, at CoVolt Holdings’ election, (i) shares of our Class A common stock at a redemption ratio of one share of Class A common stock for each Common Unit redeemed, subject to conversion rate adjustments for stock splits, stock dividends and reclassifications and other similar transactions, or (ii) an equivalent amount of cash. Alternatively, upon the exercise of the Redemption Right, CoVolt Power, Inc. will have the right (the “Call Right”) to acquire the tendered Common Units directly from the redeeming holder by paying, at its option, either shares of Class A common stock or cash. In connection with any redemption of
155
Table of Contents
Common Units pursuant to the Redemption Right (or an acquisition of Common Units by us pursuant to the Call Right), a corresponding number of shares of Class B common stock will be cancelled. Our decision to cause CoVolt Holdings to make a cash payment upon a redemption election will be made by our independent directors (within the meaning of the listing rules).
Maintenance of One-to-One Ratios. The CoVolt Holdings LLC Agreement will require that Covolt Holdings and CoVolt Power, respectively, maintain at all times (i) a one-to-one ratio between the number of Common Units owned by CoVolt Power, directly or indirectly, and the number of outstanding shares of CoVolt Power’s Class A common stock, and (ii) a one-to-one ratio between the number of Common Units owned by members (other than CoVolt Power and its subsidiaries), directly or indirectly, and the number of outstanding shares of CoVolt Power’s Class B common stock owned by such members, directly or indirectly.
Transfer restrictions. The CoVolt Holdings LLC Agreement generally will not permit transfers of Common Units by members, except for transfers to permitted transferees, transfers approved in writing by us as manager, and other limited exceptions. The CoVolt Holdings LLC Agreement may impose additional restrictions on transfers (including redemptions) that are necessary or advisable so that CoVolt Holdings is not treated as a “publicly traded partnership” for U.S. federal income tax purposes.
Dissolution. The CoVolt Holdings LLC Agreement will provide that the consent of CoVolt Power, Inc. as the managing member of CoVolt Holdings and members holding a majority of the Common Units will be required to voluntarily dissolve CoVolt Holdings. In addition to a voluntary dissolution, CoVolt Holdings will be dissolved upon the entry of a decree of judicial dissolution or other circumstances in accordance with applicable law.
Shareholders Agreement
In connection with this offering, we expect to enter into a Shareholders Agreement with certain Continuing Equity Owners. We expect that our board of directors will initially consist of seven directors, and pursuant to the Shareholders Agreement, each such Continuing Equity Owner will have the right to propose to the nominating and corporate governance committee for nomination and election to our board of directors (i) two directors at such time as such Continuing Equity Owner holds greater than or equal to 20% of the then outstanding shares of our total common stock and (ii) one director at such time as such Continuing Equity Owner holds less than 20% but greater than or equal to 10% of the then outstanding shares of our total common stock. We shall be obligated to take certain actions within our control to cause the nominating and corporate governance committee to nominate such individuals to our board of directors and to cause them to be included in our proxy statement and recommend their election. If such Continuing Equity Owner loses its right to designate any directors pursuant to the terms of the Shareholders Agreement, these positions will be filled by our board of directors or our shareholders, as applicable, in accordance with our Amended Charter. See “Description of Capital Stock” for more information regarding our Amended Charter. Additionally, each of the Continuing Equity Owners shall have the right to appoint certain of their director designees, subject to applicable laws and stock exchange regulations, to the committees of our board of directors. Further, under certain circumstances, the Continuing Equity Owners may designate individuals to serve as observers to our board of directors.
Further, for so long as the Continuing Equity Owners beneficially own at least % of our Class A common stock and Class B common stock (on an as-converted basis), the approval of our board or our shareholders, including a majority of the total voting power of the Continuing Equity Owners party to the Shareholders Agreement, is required, subject to certain exceptions, for certain actions of the Company, including but not limited to: (i) an amendment to our Amended Charter or Amended Bylaws, (ii) entering into or effecting a change in control, (iii) entering into any agreement providing for the acquisition or divestiture of assets or equity securities in excess of $200 million, (iv) entering into any joint venture or similar business alliance having a fair market
156
Table of Contents
value in excess of $100 million, (v) initiating a voluntary liquidation, dissolution, receivership, bankruptcy or other insolvency proceeding involving the Company, (vi) any material change in the nature of our business, taken as a whole, (vii) certain redemptions, acquisition or other purchases of equity securities, (viii) the incurrence of indebtedness in excess of $200 million (excluding borrowings under revolving credit facilities), (ix) terminating the employment of our chief executive officer, (x) increasing or decreasing the size or composition of our board of directors, other than to comply with the independence requirements of the NYSE listing rules, (xi) transfer, issue, sell or dispose of common stock in excess of 10% of our outstanding equity securities, (xii) any transaction with or involving any of our “affiliates” (as defined in Rule 12b-2 of the Exchange Act) and (xiii) entering into an agreement with respect to any of the foregoing.
Under the Shareholders Agreement, the Continuing Equity Owners party thereto will agree with the Company (and only the Company) to take all necessary action, including casting all votes such Continuing Equity Owners are entitled to cast at any annual or special meeting of shareholders, to elect or appoint to our board of directors each individual nominated by the nominating and corporate governance committee in accordance with the Shareholders Agreement.
Registration Rights Agreement
We intend to enter into a Registration Rights Agreement with certain of the Continuing Equity Owners in connection with this offering, which we refer to as the Registration Rights Agreement.
The Registration Rights Agreement will provide certain Continuing Equity Owners with certain demand registration rights, including shelf registration rights, in respect of any shares of our Class A common stock held by them, subject to certain conditions. In addition, in the event that we register additional shares of Class A common stock for sale to the public following the completion of this offering, we will be required to give notice of such registration to certain Continuing Equity Owners and, subject to certain limitations, include shares of Class A common stock held by them in such registration. The agreement will include customary indemnification provisions in favor of certain Continuing Equity Owners and related parties against certain losses and liabilities arising out of or based upon any filing or other disclosure made by us under the securities laws relating to any such registration.
Director and Officer Indemnification and Insurance
Prior to the consummation of this offering, we intend to enter into separate indemnification agreements with each of our directors and executive officers. We have also purchased directors’ and officers’ liability insurance. See “Description of Capital Stock–Limitations on Liability and Indemnification of Officers and Directors.”
Directed Share Program
At our request, the underwriters have reserved for sale at the initial public offering up to % of the Class A common stock being offered for sale, to our directors, officers and certain employees and other related parties. The sales will be made at our direction by , an underwriter of this offering, and its affiliates through a directed share program. The number of shares of Class A common stock available for sale to the general public will be reduced to the extent these individuals purchase such reserved shares. Any reserved shares that are not so purchased will be offered by the underwriters to the general public on the same basis as the other shares offered by this prospectus. Except for any shares acquired by our directors and officers, shares purchased pursuant to the directed share program will not be subject to lock-up agreements with the underwriters. We have agreed to indemnify the representatives in connection with the directed share program, including for the failure of any participant to pay for its shares of Class A common stock. Other than the underwriting discount described on the front cover of this prospectus, the underwriters will not be entitled to any commission with respect to shares of Class A common stock sold pursuant to the directed share program.
157
Table of Contents
Our Policy Regarding Related Party Transactions
Our board of directors recognizes the fact that transactions with related persons present a heightened risk of conflicts of interests, improper valuation or the perception thereof. Prior to the consummation of this offering, our board of directors will adopt a written policy on transactions with related persons that is in conformity with the requirements for issuers having publicly held common stock that is listed on the NYSE. Under the new policy:
| • | any related person transaction, and any material amendment or modification to a related person transaction, must be reviewed and approved or ratified by a committee of the board of directors composed solely of independent directors who are disinterested or by the disinterested members of the board of directors; and |
| • | any employment relationship or transaction involving an executive officer and any related compensation must be approved by the compensation committee of the board of directors or recommended by the compensation committee to the board of directors for its approval. |
| • | In connection with the review and approval or ratification of a related person transaction: |
| • | management must disclose to the committee or disinterested directors, as applicable, the name of the related person and the basis on which the person is a related person, the material terms of the related person transaction, including the approximate dollar value of the amount involved in the transaction, and all the material facts as to the related person’s direct or indirect interest in, or relationship to, the related person transaction; |
| • | management must advise the committee or disinterested directors, as applicable, as to whether the related person transaction complies with the terms of our agreements governing our material outstanding indebtedness that limit or restrict our ability to enter into a related person transaction; |
| • | management must advise the committee or disinterested directors, as applicable, as to whether the related person transaction will be required to be disclosed in our applicable filings under the Securities Act or the Exchange Act, and related rules, and, to the extent required to be disclosed, management must ensure that the related person transaction is disclosed in accordance with the Securities Act and the Exchange Act and related rules; and |
| • | management must advise the committee or disinterested directors, as applicable, as to whether the related person transaction constitutes a “personal loan” for purposes of Section 402 of the Sarbanes-Oxley Act. |
In addition, the related person transaction policy provides that the committee or disinterested directors, as applicable, in connection with any approval or ratification of a related person transaction involving a non-employee director should consider whether such transaction would compromise the director’s status as an “independent,” “outside,” or “non-employee” director, as applicable, under the rules and regulations of the SEC, the NYSE and the Code.
158
Table of Contents
General
The following summary describes the material provisions of our capital stock and certain provisions of our amended and restated certificate of formation and our amended and restated bylaws, each of which will become effective immediately prior to the completion of this offering, and the Texas Business Organizations Code (the “TBOC”), and is qualified by reference to the amended and restated certificate of formation, the amended and restated bylaws, and the TBOC. We urge you to read our amended and restated certificate of formation and our amended and restated bylaws, which are included as exhibits to the registration statement of which this prospectus forms a part. In this “Description of Capital Stock” section, “we,” “us,” “our,” and “our company” refer to CoVolt Power and not any of its subsidiaries.
Upon the consummation of this offering, our authorized capital stock will consist of shares of Class A common stock, par value $ per share, Class B common stock, par value $ per share and shares of preferred stock, par value $ per share, the rights and preferences of which the board of directors may establish from time to time.
We are selling shares of Class A common stock in this offering. All shares of our Class A common stock outstanding upon consummation of this offering will be fully paid and non-assessable. We are issuing shares of Class B common stock to the Continuing Equity Owners in connection with the Reorganization Transactions.
Common Stock
Class A common stock
Holders of shares of our Class A common stock are entitled to one vote for each share held of record on all matters submitted to a vote of shareholders.
Holders of shares of our Class A common stock are entitled to receive dividends when and if declared by our board of directors out of funds legally available therefor, subject to any statutory or contractual restrictions on the payment of dividends and to any restrictions on the payment of dividends imposed by the terms of any outstanding preferred stock.
Upon our dissolution or liquidation, after payment in full of all amounts required to be paid to creditors and to the holders of preferred stock having liquidation preferences, if any, the holders of shares of our Class A common stock will be entitled to receive pro rata our remaining assets available for distribution.
Holders of shares of our Class A common stock do not have preemptive, subscription, redemption or conversion rights. There will be no redemption or sinking fund provisions applicable to the Class A common stock.
Class B common stock
Each share of our Class B common stock entitles its holders to one vote per share on all matters presented to our shareholders generally.
Shares of Class B common stock will be issued in the future only to the extent necessary to maintain a one-to-one ratio between the number of Common Units held by the Continuing Equity Owners and the number of shares of Class B common stock issued to the Continuing Equity Owners. Shares of Class B common stock are transferable only together with an equal number of Common Units. Only permitted transferees of Common Units held by the Continuing Equity Owners will be permitted transferees of Class B common stock. See “Certain Relationships and Related Person Transactions–CoVolt Holdings LLC Agreement.”
159
Table of Contents
Holders of shares of our Class B common stock will vote together with holders of our Class A common stock as a single class on all matters presented to our shareholders for their vote or approval, except for certain amendments to our amended and restated certificate of formation described below or as otherwise required by applicable law or the amended and restated certificate of formation.
Holders of our Class B common stock do not have any right to receive dividends or to receive a distribution upon dissolution or liquidation. Additionally, holders of shares of our Class B common stock do not have preemptive, subscription, redemption or conversion rights. There will be no redemption or sinking fund provisions applicable to the Class B common stock. Any amendment of our amended and restated certificate of formation that gives holders of our Class B common stock (i) any rights to receive dividends or any other kind of distribution, (ii) any right to convert into or be exchanged for Class A common stock or (iii) any other economic rights will require, in addition to shareholder approval, the affirmative vote of holders of our Class A common stock voting separately as a class.
Upon the closing of this offering, the Continuing Equity Owners will own, in the aggregate, shares of our Class B common stock.
Voting Rights
Holders of our common stock are entitled to one vote for each share held on all matters submitted to a vote of shareholders. The holders of our common stock vote together as a single class, unless otherwise required by law. The holders of our common stock do not have cumulative voting rights in the election of directors.
Our Amended Bylaws will provide for a classified board of directors consisting of three classes of approximately equal size, each serving staggered three-year terms. If the number of directors is changed, any increase or decrease shall be apportioned among the classes by the board of directors so as to maintain the number of directors in each class as nearly equal as possible, and any additional director of any class elected to fill a vacancy resulting from an increase in such class shall hold office for a term that shall coincide with the remaining term of that class. In no case will a decrease in the number of directors shorten the term of any incumbent director.
Preferred Stock
No shares of preferred stock will be issued or outstanding immediately after the offering contemplated by this prospectus. Our Amended Charter authorizes our board of directors to establish one or more series of preferred stock. Unless required by law or any stock exchange, the authorized shares of preferred stock will be available for issuance without further action by the holders of our common stock. Our board of directors is able to determine, without shareholder approval and with respect to any series of preferred stock, the powers (including voting powers), preferences and relative, participating, optional, or other special rights, and the qualifications, limitations, or restrictions thereof, including, without limitation:
| • | the designation of the series; |
| • | the number of shares of the series, which our board of directors may, except where otherwise provided in the preferred stock designation, increase (but not above the total number of authorized shares of the class) or decrease (but not below the number of shares then outstanding); |
| • | whether dividends, if any, will be cumulative or non-cumulative and the dividend rate of the series; |
| • | the dates at which dividends, if any, will be payable; |
| • | the redemption or repurchase rights and price or prices, if any, for shares of the series; |
160
Table of Contents
| • | the terms and amounts of any sinking fund provided for the purchase or redemption of shares of the series; |
| • | the amounts payable on shares of the series in the event of any voluntary or involuntary liquidation, dissolution, or winding-up of our affairs; |
| • | whether the shares of the series will be convertible into shares of any other class or series, or any other security, of us or any other entity, and, if so, the specification of the other class or series or other security, the conversion price or prices, or rate or rates, any rate adjustments, the date or dates as of which the shares will be convertible and all other terms and conditions upon which the conversion may be made; |
| • | restrictions on the issuance of shares of the same series or of any other class or series; and |
| • | the voting rights, if any, of the holders of the series. |
We could issue a series of preferred stock that could, depending on the terms of the series, impede or discourage an acquisition attempt or other transaction that some, or a majority, of the holders of our common stock might believe to be in their best interests or in which the holders of our common stock might receive a premium over the market price of the shares of our common stock. Additionally, the issuance of preferred stock may adversely affect the rights of holders of our common stock by restricting dividends on the common stock, diluting the voting power of the common stock or subordinating the liquidation rights of the common stock. As a result of these or other factors, the issuance of preferred stock could have an adverse impact on the market price of our common stock. We have no current plan for the issuance of any shares of preferred stock.
Registration Rights
After the completion of this offering, certain holders of our common stock will be entitled to rights with respect to the registration of their shares under the Securities Act. See “Certain Relationships and Related Party Transactions–Related Party Agreements in Effect Prior to this Offering–Registration Rights Agreement” for more information.
In connection with this offering, we expect to enter into the Shareholders Agreement pursuant to which certain Continuing Equity Owners will have specified board representation, governance and other rights. See “Management–Composition of our Board of Directors.”
Anti-Takeover Effects of Provisions of our Amended Charter and Amended Bylaws
Our amended and restated certificate of formation and amended and restated bylaws will contain and the TBOC contains provisions, which are summarized in the following paragraphs, that are intended to enhance the likelihood of continuity and stability in the composition of our Board. These provisions are intended to avoid costly takeover battles, reduce our vulnerability to a hostile change of control, and enhance the ability of our Board to maximize shareholder value in connection with any unsolicited offer to acquire us. However, these provisions may have an anti-takeover effect and may delay, deter, or prevent a merger or acquisition of us by means of a tender offer, a proxy contest, or other takeover attempt that a shareholder might consider in its best interest, including those attempts that might result in a premium over the prevailing market price for the shares of common stock held by shareholders.
Authorized but Unissued Shares
Texas law does not require shareholder approval for any issuance of authorized shares. Accordingly, the authorized but unissued shares of our common stock and our preferred stock are available for future issuance
161
Table of Contents
without shareholder approval, subject to any limitations imposed by NYSE rules. The listing standards of NYSE, which would apply if and so long as our common stock remains listed on NYSE, require shareholder approval of certain issuances equal to or exceeding 20% of the then-outstanding voting power or then-outstanding number of shares of common stock. These additional shares may be issued in the future for a variety of corporate finance transactions, acquisitions, and employee benefit plans and, as described under “Certain Relationships and Related Party Transactions–CoVolt Power LLC Agreement–Agreement in effect upon consummation of the Transactions–Common unit redemption right,” funding of redemptions of Common Units. The existence of authorized but unissued and unreserved common stock and preferred stock could make more difficult or discourage an attempt to obtain control of us by means of a proxy contest, tender offer, merger, or otherwise.
Business Combinations
We are subject to the affiliated business combinations provisions of Title 2, Chapter 21, Subchapter M of the TBOC (Sections 21.601 through 21.610), which provides that a Texas “issuing public corporation”, which applies to any Texas corporation that, among other things, has more than 100 shareholders, may not engage in specified types of business combinations, including mergers, consolidations, and asset sales, with a person, or an affiliate or associate of that person, who is an “affiliated shareholder.” For purposes of this law, an “affiliated shareholder” is generally defined as the holder of 20% or more of the corporation’s voting shares, for a period of three years from the date that person became an affiliated shareholder. The law’s prohibitions do not apply if:
| • | the business combination or the acquisition of shares by the affiliated shareholder was approved by the board of directors of the corporation before the affiliated shareholder became an affiliated shareholder; or |
| • | the business combination was approved by the affirmative vote of the holders of at least two-thirds of the outstanding voting shares of the corporation not beneficially owned by the affiliated shareholder, at a meeting of shareholders called for that purpose, not less than six months after the affiliated shareholder became an affiliated shareholder. |
Because we will have more than 100 shareholders, we will be considered to be an “issuing public corporation” for purposes of this law. The affiliated business combinations provisions of the TBOC do not apply to the following:
| • | the business combination of an issuing public corporation where: (a) the corporation’s original certificate of formation or bylaws contain a provision expressly electing not to be governed by the affiliated business combinations provisions of the TBOC or (b) the corporation adopts an amendment to its certificate of formation or bylaws, by the affirmative vote of the holders, other than affiliated shareholders, of at least two-thirds of the outstanding voting shares of the corporation, expressly electing not to be governed by the affiliated business combinations provisions of the TBOC, so long as the amendment does not take effect for 18 months following the date of the vote and does not apply to a business combination with an affiliated shareholder who became affiliated on or before the effective date of the amendment; |
| • | a business combination of an issuing public corporation with an affiliated shareholder that became an affiliated shareholder inadvertently, if the affiliated shareholder: (a) divests itself, as soon as practicable, of enough shares to no longer be a beneficial owner of 20% or more of the outstanding voting shares of the issuing public corporation and (b) would not at any time within the three-year period preceding the announcement of the business combination have been an affiliated shareholder but for the inadvertent acquisition; |
| • | a business combination with an affiliated shareholder who became an affiliated shareholder through a transfer of shares by will or intestacy and continuously was an affiliated shareholder until the announcement date of the business combination; or |
162
Table of Contents
| • | a business combination of a corporation with its wholly owned Texas subsidiary if the subsidiary is not an affiliate or associate of the affiliated shareholder other than by reason of the affiliated shareholder’s beneficial ownership of voting shares of the corporation. |
Neither our amended and restated certificate of formation nor our amended and restated bylaws contain any provision expressly providing that we will not be subject to the affiliated business combinations provisions of the TBOC. The affiliated business combinations provisions of the TBOC may have the effect of inhibiting a non-negotiated merger or other business combination involving us, even if that event would be beneficial to our shareholders.
Vacancies
Our amended and restated certificate of formation will provide that, subject to the special rights of the holders of one or more outstanding series of preferred stock to elect directors, and except as otherwise provided by law, any vacancies on our board of directors resulting from the death, resignation, disqualification or removal of any director may be filled by a majority of the directors then in office, even though less than a quorum, or by a sole remaining director, or by election at an annual or special meeting of shareholders called for that purpose, with any director so elected to hold office for the remainder of the unexpired term of his or her predecessor. Newly created directorships resulting from any increase in the authorized number of directors may be filled by election at an annual or special meeting of shareholders called for that purpose or by the board of directors; provided that any director elected by the board of directors to fill such a newly created directorship shall hold office only until the next election of one or more directors by the shareholders; provided, however, that, for so long as the TBOC prohibits such action, the board of directors may not fill more than two such directorships during the period between any two successive annual meetings of shareholders.
No Cumulative Voting
Under Texas law, the right to vote cumulatively does not exist unless the certificate of formation specifically authorizes cumulative voting. Our amended and restated certificate of formation will not authorize cumulative voting. Therefore, shareholders holding a majority in voting power of the shares of our capital stock entitled to vote generally in the election of directors will be able to elect all of our directors.
Shareholder Action; Special Meetings of Shareholders
Our amended and restated certificate of formation will provide that, prior to the first date on which no shares of Class B common stock remain outstanding (the “Sunset Date”), our shareholders may take action by consent without a meeting, and at any time from and after the Sunset Date, our shareholders may not take action by consent without a meeting, but may only take action at a meeting of shareholders. These provisions might delay the ability of our shareholders to force consideration of a proposal or for shareholders controlling a majority of our capital stock to take any action, including the removal of directors.
Requirements for Advance Notification of Director Nominations and Shareholder Proposals
Our amended and restated bylaws will establish advance notice procedures with respect to shareholder proposals and the nomination of candidates for election as directors, other than nominations made by or at the direction of the Board or a committee of the Board. In order for any matter to be “properly brought” before a meeting, a shareholder will have to comply with advance notice requirements and provide us with certain information. Generally, to be timely, a shareholder’s notice must be received at our principal executive offices not less than 90 days nor more than 120 days prior to the first anniversary date of the immediately preceding annual meeting
163
Table of Contents
of shareholders. Our amended and restated bylaws will also specify requirements as to the form and content of a shareholder’s notice. Our amended and restated bylaws will allow the chair of the meeting at a meeting of the shareholders to adopt rules and regulations for the conduct of meetings which may have the effect of precluding the conduct of certain business at a meeting if the rules and regulations are not followed. These provisions may also defer, delay, or discourage a potential acquiror from conducting a solicitation of proxies to elect the acquiror’s own slate of directors or otherwise attempting to influence or obtain control of us.
Amendment of Amended Charter or Amended Bylaws
Our Amended Charter requires the approval of the holders of at least two-thirds in the voting power of the outstanding shares of our capital stock in order to amend certain provisions including those relating to removal of directors, rights and privileges of the common stock, indemnification, exclusive forum, and the prohibition on shareholder action by written consent. However, if the Continuing Equity Owners cease to beneficially own at least 40% of the total voting power of the outstanding shares of our capital stock, our Amended Charter will require the approval of the holders of a majority of the voting power of the outstanding shares of our capital stock in order to amend such provisions. Our Amended Bylaws provide that the approval of the holders of at least two-thirds in the voting power of the outstanding shares of our capital stock of the outstanding shares of capital stock entitled to vote thereon is required for shareholders to amend or adopt any provision of our Amended Bylaws.
The foregoing provisions of our Amended Charter and Amended Bylaws could discourage potential acquisition proposals and could delay or prevent a change in control. These provisions are intended to enhance the likelihood of continuity and stability in the composition of our board of directors and in the policies formulated by our board of directors and to discourage certain types of transactions that may involve an actual or threatened change of control. These provisions are designed to reduce our vulnerability to an unsolicited acquisition proposal. The provisions also are intended to discourage certain tactics that may be used in proxy fights. However, such provisions could have the effect of discouraging others from making tender offers for our shares and, as a consequence, they also may inhibit fluctuations in the market price of our shares of common stock that could result from actual or rumored takeover attempts. Such provisions also may have the effect of preventing changes in our management or delaying or preventing a transaction that might benefit you or other minority shareholders.
Issuance of Undesignated Preferred Stock
Our board of directors will have the authority, without further action by our shareholders, to issue up to shares of undesignated preferred stock with rights and preferences, including voting rights, designated from time to time by our board of directors. The existence of authorized but unissued shares of preferred stock would enable our board of directors to render more difficult or to discourage an attempt to obtain control of us by means of a merger, tender offer, proxy contest or other means.
Exclusive Forum
Under our Amended Bylaws, the Business Court in the Eleventh Business Court Division of the State of Texas will serve as the exclusive forum for the following categories of legal actions or proceedings governed by Texas statutory or common law: derivative suits or proceedings initiated on our behalf; claims alleging that any of our directors, officers, employees, or agents breached a fiduciary duty owed to us or our shareholders; claims against us or any of our directors, officers, or employees that arise under the TBOC or our LLC Agreement; and claims against us or any of our directors, officers, or employees relating to other entity claims as that term is defined in Section 2.115 of the TBOC. These forum selection provisions do not apply to actions seeking to
164
Table of Contents
enforce obligations or liabilities arising under the Exchange Act, the Securities Act, or any other claims within the exclusive jurisdiction of the federal courts. For such federal securities law claims, our LLC Agreement designates the United States District Court for the Southern District of Texas as the sole and exclusive forum, to the fullest extent permitted by applicable law. These forum selection provisions may restrict a shareholder’s ability to pursue claims in a judicial forum that the shareholder considers more favorable for disputes involving us, our directors, officers, employees, agents, or other shareholders. This could discourage litigation against us and such persons and may increase the costs to shareholders of bringing such claims. Any person or entity purchasing or otherwise acquiring any interest in our securities shall be deemed to have notice of and consented to these provisions.
Conflicts of Interest
Texas law permits corporations to adopt provisions renouncing any interest or expectancy in certain opportunities that are presented to the corporation or its officers, directors, or shareholders. Our amended and restated certificate of formation will, to the maximum extent permitted from time to time by Texas law, renounce any interest or expectancy that we have in, or right to be offered an opportunity to participate in, specified business opportunities that are from time to time presented to any of our directors or shareholders who are not employed by us or our subsidiaries (each such person, an “exempt person”). Our amended and restated certificate of formation will provide that, to the fullest extent permitted by law, no exempt person will have any duty to refrain from (1) engaging in a corporate opportunity in the same or similar lines of business in which we or our subsidiaries now engage or propose to engage or (2) otherwise competing with us or our subsidiaries. In addition, to the fullest extent permitted by applicable law, if any exempt person acquires knowledge of a potential transaction or other business opportunity which may be a corporate opportunity for itself or himself or its or his affiliates or for us or our affiliates, such exempt person will have no duty to communicate or offer such transaction or business opportunity to us or any of our subsidiaries and they may take any such opportunity for themselves or offer it to another person or entity, unless such opportunity was expressly offered to them solely in their capacity as a director, executive officer or employee of us or our subsidiaries. To the fullest extent permitted by Texas law, no potential transaction or business opportunity may be deemed to be a corporate opportunity of the corporation or our subsidiaries unless (1) we or our subsidiaries would be permitted to undertake such transaction or opportunity in accordance with our amended and restated certificate of formation, (2) we or our subsidiaries, at such time have sufficient financial resources to undertake such transaction or opportunity, (3) we or our subsidiaries have an interest or expectancy in such transaction or opportunity and (4) such transaction or opportunity would be in the same or similar line of our business in which we or our subsidiaries are engaged or a line of business that is reasonably related to, or a reasonable extension of, such line of business. Our amended and restated certificate of formation will not renounce our interest in any business opportunity that is expressly offered to an employee director or employee in his or her capacity as a director or employee of CoVolt Power.
Limitations on Liability and Indemnification of Officers and Directors
The TBOC authorizes corporations to limit or eliminate the personal liability of directors and officers to corporations and their shareholders for monetary damages for breaches of directors’ and officers’ fiduciary duties (other than breaches of such person’s duty of loyalty to corporations or their shareholders), except for liability for:
| • | any breach of the director’s duty of loyalty to us or our shareholders; |
| • | any act or omission not in good faith that constitutes a breach of duty of the person to us or which involved intentional misconduct or a knowing violation of law; |
165
Table of Contents
| • | any transaction from which the director derived an improper personal benefit; and |
| • | any act or omission for which the liability of a director is expressly provided by an applicable statute. |
Our amended and restated certificate of formation will include a provision that eliminates the personal liability of directors and officers for monetary damages for any breach of fiduciary duty as a director or officer, except to the extent such exemption from liability or limitation thereof is not permitted under the TBOC. The effect of these provisions will be to eliminate, other than limited exceptions, the rights of us and our shareholders, through shareholders’ derivative suits on our behalf, to recover monetary damages from a director for breach of fiduciary duty as a director or officer, including breaches resulting from grossly negligent behavior. However, exculpation will not apply to any director or officer if such person has acted in bad faith, engaged in intentional misconduct, knowingly violated the law, authorized illegal dividends or redemptions, derived an improper benefit from his or her actions as a director or officer, or engaged in an act or omission for which the liability of the director or officer is expressly provided by an applicable statute.
Our amended and restated bylaws will provide generally that we must indemnify and advance expenses to our directors and officers to the fullest extent authorized by the TBOC. We also have entered into separate indemnification agreements with each of our directors and executive officers and will be expressly authorized to carry directors’ and officers’ liability insurance providing indemnification for our directors, officers, and certain employees for some liabilities. We believe that these indemnification and advancement provisions and insurance will be useful to attract and retain qualified directors and officers.
These limitation of liability, indemnification, and advancement provisions may discourage shareholders from bringing a lawsuit against directors for breach of their fiduciary duty. These provisions also may have the effect of reducing the likelihood of derivative litigation against directors and officers, even though such an action, if successful, might otherwise benefit us and our shareholders. In addition, your investment may be adversely affected to the extent we pay the costs of settlement and damage awards against directors and officers pursuant to these indemnification provisions.
There is currently no pending material litigation or proceeding involving any of our directors, officers, or employees for which indemnification is sought.
Dissenters’ Rights of Appraisal and Payment
Under the TBOC, with certain exceptions, our shareholders will have appraisal rights in connection with a merger, a sale of all or substantially all of our assets, an interest exchange, or a conversion. Pursuant to the TBOC, shareholders who properly request and perfect appraisal rights in connection with such merger, sale of all or substantially all of our assets, interest exchange, or conversion will have the right to receive payment of the fair value of their shares as agreed to between the shareholder and us or, if unable to reach agreement, as determined by the Eleventh Business Court Division of the State of Texas.
Shareholders’ Derivative Actions
Under the TBOC, any of our shareholders may bring a civil action in our name to procure a judgment in our favor, also known as a derivative proceeding, provided that the shareholder bringing the action (i) is a holder of our shares at the time of the transaction to which the action relates or such shareholder became a shareholder by operation of law from a person that was a shareholder at the time of the transaction to which the action relates and (ii) fairly and adequately represents the interests of the Company in enforcing the right of the Company.
166
Table of Contents
Stock Exchange Listing
We have applied to list our common stock on the NYSE under the symbol “KVLT.”
Transfer Agent and Registrar
The transfer agent and registrar for our common stock is Equiniti Trust Company, LLC. The transfer agent and registrar’s address is 28 Liberty Street, Floor 53, New York, New York 10005.
167
Table of Contents
SHARES ELIGIBLE FOR FUTURE SALE
Immediately prior to this offering, there was no public market for our Class A common stock. Future sales of substantial amounts of Class A common stock in the public market, or the perception that such sales may occur, could adversely affect the market price of our Class A common stock. Although we have applied to have our Class A common stock listed on the NYSE, we cannot assure you that there will be an active public market for our Class A common stock.
Upon the closing of this offering, we will have outstanding an aggregate of shares of Class A common stock, assuming the issuance of shares of Class A common stock offered by us and the selling shareholders in this offering. Of these shares, all shares sold in this offering will be freely tradable without restriction or further registration under the Securities Act, except for any shares purchased by our “affiliates,” as that term is defined in Rule 144 under the Securities Act, whose sales would be subject to the Rule 144 resale restrictions described below, other than the holding period requirement.
The remaining shares of Class A common stock will be “restricted securities,” as that term is defined in Rule 144 under the Securities Act. These restricted securities are eligible for public sale only if they are registered under the Securities Act or if they qualify for an exemption from registration under Rules 144 or 701 under the Securities Act, which are summarized below.
Registration Rights
Pursuant to our registration rights agreement, after the completion of this offering, the holders of up to shares of our Class A common stock, or certain transferees, will be entitled to certain rights with respect to the registration of the offer and sale of those shares under the Securities Act. See the section titled “Description of Capital Stock–Registration Rights” for a description of these registration rights. If the offer and sale of these shares of our Class A common stock are registered, the shares will be freely tradable without restriction under the Securities Act, subject to the Rule 144 limitations applicable to affiliates, and a large number of shares may be sold into the public market.
Lock-Up Agreements
We, our officers and directors will agree that, without the prior written consent of J.P. Morgan Securities LLC and Jefferies LLC, as representatives of the underwriters, we and they will not, subject to certain exceptions, during the period ending 180 days after the date of this prospectus:
| • | offer, sell, contract to sell, pledge, grant any option to purchase, make any short sale or otherwise transfer or dispose of, directly or indirectly or publicly disclose the intention to make any offer, sale, pledge or disposition of any shares of our Class A common stock, or any options or warrants to purchase any shares of our Class A common stock, or any securities convertible into, or exchangeable for, or that represent the right to receive, shares of our Class A common stock; or |
| • | enter into any swap or other arrangement that transfers to another, all or a portion of the economic consequences of ownership of our Class A common stock or any securities convertible into or exercisable or exchangeable for shares of our Class A common stock, |
whether any transaction described above is to be settled by delivery of our Class A common stock or such other securities, in cash or otherwise.
The representatives of the underwriters have advised us that they have no present intent or arrangement to release any shares subject to a lock-up, and will consider the release of any lock-up on a case-by-case basis.
168
Table of Contents
Upon a request to release any shares subject to a lock-up, the representatives of the underwriters would consider the particular circumstances surrounding the request, including, but not limited to, the length of time before the lock-up expires, the number of shares requested to be released, reasons for the request, the possible impact on the market or our Class A common stock and whether the holder of our shares requesting the release is an officer, director or other affiliate of ours.
Upon the expiration of the applicable lock-up periods, substantially all of the shares subject to such lock-up restrictions will become eligible for sale, subject to the limitations discussed above. For a further description of these lock-up agreements, see “Underwriting.”
Rule 144
Affiliate Resales of Restricted Securities
In general, beginning 90 days after the effective date of the registration statement of which this prospectus is a part, a person who is an affiliate of ours, or who was an affiliate at any time during the 90 days before a sale, who has beneficially owned shares of our Class A common stock for at least six months would be entitled to sell in “broker’s transactions” or certain “riskless principal transactions” or to market makers, a number of shares within any three-month period that does not exceed the greater of:
| • | 1% of the number of shares of our Class A common stock then outstanding; and |
| • | the average weekly trading volume in our Class A common stock on the NYSE during the four calendar weeks preceding the filing of a notice on Form 144 with respect to such sale. |
Affiliate resales under Rule 144 are also subject to the availability of current public information about us. In addition, if the number of shares being sold under Rule 144 by an affiliate during any three-month period exceeds 5,000 shares or has an aggregate sale price in excess of $50,000, the seller must file a notice on Form 144 with the SEC and the NYSE concurrently with either the placing of a sale order with the broker or the execution directly with a market maker.
Non-Affiliate Resales of Restricted Securities
Under Rule 144, a person who is not an affiliate of ours at the time of sale, and has not been an affiliate at any time during the 90 days preceding a sale, and who has beneficially owned shares of our Class A common stock for at least six months but less than a year, is entitled to sell such shares subject only to the availability of current public information about us. If such person has held our shares for at least one year, such person can resell without regard to any Rule 144 restrictions, including the 90-day public company requirement and the current public information requirement.
Non-affiliate resales are not subject to the manner of sale, volume limitation or notice filing provisions of Rule 144.
Rule 701
In general, under Rule 701, any of our employees, directors, officers, consultants or advisors who purchases shares from us in connection with a compensatory stock or option plan or other written agreement before the effective date of the registration statement of which this prospectus forms a part is entitled to sell such shares 90 days after such effective date in reliance on Rule 144. Our affiliates can resell shares in reliance on Rule 144 without having to comply with the holding period requirement, and non-affiliates of the issuer can resell shares in reliance on Rule 144 without having to comply with the current public information and holding period requirements.
169
Table of Contents
Equity Plans
We intend to file with the SEC a registration statement on Form S-8 under the Securities Act to register the offer and sale of all shares of Class A common stock reserved for issuance under our 2026 Plan. We expect this registration statement will be filed and become effective as soon as practicable after the completion of this offering. Accordingly, shares registered under such registration statement will be available for sale in the open market following its effective date, subject to certain Rule 144 limitations applicable to affiliates, vesting restrictions, and the lock-up agreements and market standoff restrictions described above, if applicable.
170
Table of Contents
MATERIAL U.S. FEDERAL INCOME TAX CONSEQUENCES TO NON-U.S. HOLDERS
The following discussion is a summary of the material U.S. federal income tax consequences to Non-U.S. Holders (as defined below) of the purchase, ownership and disposition of our Class A common stock issued pursuant to this offering, but does not purport to be a complete analysis of all potential tax effects. The effects of other U.S. federal tax laws, such as estate and gift tax laws, and any applicable state, local or non-U.S. tax laws are not discussed. This discussion is based on the U.S. Internal Revenue Code of 1986, as amended (the “Code”), Treasury Regulations promulgated under the Code, judicial decisions, and published rulings and administrative pronouncements of the U.S. Internal Revenue Service (the “IRS”) in each case in effect as of the date of this prospectus. These authorities may change or be subject to differing interpretations. Any such change or differing interpretation may be applied retroactively in a manner that could adversely affect a Non-U.S. Holder. We have not sought and will not seek any rulings from the IRS regarding the matters discussed below. There can be no assurance the IRS or a court will not take a contrary position to that discussed below regarding the tax consequences of the purchase, ownership and disposition of our Class A common stock.
This discussion is limited to Non-U.S. Holders that hold our Class A common stock as a “capital asset” within the meaning of Section 1221 of the Code (generally, property held for investment). This discussion does not address all U.S. federal income tax consequences relevant to a Non-U.S. Holder’s particular circumstances, including the impact of the Medicare contribution tax on net investment income. In addition, it does not address consequences relevant to Non-U.S. Holders subject to special rules, including, without limitation:
| • | U.S. expatriates and former citizens or long-term residents of the United States; |
| • | persons subject to alternative minimum tax; |
| • | persons holding our Class A common stock as part of a hedge, straddle, or other risk reduction strategy or as part of a conversion transaction or other integrated investment; |
| • | banks, insurance companies, and other financial institutions; |
| • | brokers, dealers, or traders in securities; |
| • | “controlled foreign corporations,” “foreign controlled foreign corporations,” “passive foreign investment companies,” and corporations that accumulate earnings to avoid U.S. federal income tax; |
| • | partnerships or other entities or arrangements classified as partnerships for U.S. federal income tax purposes and other pass-through entities (and investors in such entities); |
| • | tax-exempt organizations or governmental organizations; |
| • | persons deemed to sell our Class A common stock under the constructive sale provisions of the Code; |
| • | persons who hold or receive our Class A common stock pursuant to the exercise of any employee stock option or otherwise as compensation; |
| • | tax-qualified retirement plans; |
| • | “qualified foreign pension funds” as defined in Section 897(l)(2) of the Code and entities all of the interests of which are held by qualified foreign pension funds; and |
| • | persons subject to special tax accounting rules as a result of any item of gross income with respect to the Class A common stock being taken into account in an applicable financial statement. |
171
Table of Contents
If an entity classified as a partnership for U.S. federal income tax purposes holds our Class A common stock, the tax treatment of a partner in the partnership will depend on the status of the partner, the activities of the partnership, and certain determinations made at the partner level. Accordingly, partnerships holding our Class A common stock and the partners in such partnerships should consult their tax advisors regarding the U.S. federal income tax consequences to them.
THIS DISCUSSION IS FOR INFORMATIONAL PURPOSES ONLY AND IS NOT TAX ADVICE. INVESTORS SHOULD CONSULT THEIR TAX ADVISORS WITH RESPECT TO THE APPLICATION OF THE U.S. FEDERAL INCOME TAX LAWS TO THEIR PARTICULAR SITUATIONS, AS WELL AS ANY TAX CONSEQUENCES OF THE PURCHASE, OWNERSHIP, AND DISPOSITION OF OUR CLASS A COMMON STOCK ARISING UNDER THE U.S. FEDERAL ESTATE OR GIFT TAX LAWS OR UNDER THE LAWS OF ANY STATE, LOCAL, OR NON-U.S. TAXING JURISDICTION OR UNDER ANY APPLICABLE INCOME TAX TREATY.
Definition of a Non-U.S. Holder
For purposes of this discussion, a “Non-U.S. Holder” is any beneficial owner of our Class A common stock that is neither a “U.S. person” nor an entity classified as a partnership for U.S. federal income tax purposes. A U.S. person is any person that, for U.S. federal income tax purposes, is or is treated as any of the following:
| • | an individual who is a citizen or resident of the United States; |
| • | a corporation (or other entity treated as a corporation for U.S. federal income tax purposes) created or organized under the laws of the United States, any state thereof, or the District of Columbia; |
| • | an estate, the income of which is subject to U.S. federal income tax regardless of its source; or |
| • | a trust that (1) is subject to the primary supervision of a U.S. court and the control of one or more “United States persons” (within the meaning of Section 7701(a)(30) of the Code), or (2) has a valid election in effect to be treated as a United States person for U.S. federal income tax purposes. |
Distributions
If we make distributions of cash or property on our Class A common stock, such distributions will constitute dividends for U.S. federal income tax purposes to the extent paid from our current or accumulated earnings and profits, as determined under U.S. federal income tax principles. Amounts not treated as dividends for U.S. federal income tax purposes will constitute a return of capital and first be applied against and reduce a Non-U.S. Holder’s adjusted tax basis in its Class A common stock, but not below zero. Any excess will be treated as capital gain and will be treated as described below under “–Sale or Other Taxable Disposition.”
Subject to the discussions below on the withholding requirements with respect to foreign accounts and effectively connected income, dividends paid to a Non-U.S. Holder will be subject to U.S. federal withholding tax at a rate of 30% of the gross amount of the dividends (or such lower rate specified by an applicable income tax treaty, provided the Non-U.S. Holder furnishes a valid IRS Form W-8BEN or W-8BEN-E (or other applicable documentation) certifying qualification for the lower treaty rate). A Non-U.S. Holder that does not timely furnish the required documentation, but that qualifies for a reduced treaty rate, may obtain a refund of any excess amounts withheld by timely filing an appropriate claim for refund with the IRS. Non-U.S. Holders should consult their tax advisors regarding their entitlement to benefits under any applicable income tax treaty.
If dividends paid to a Non-U.S. Holder are effectively connected with the Non-U.S. Holder’s conduct of a trade or business within the United States (and, if required by an applicable income tax treaty, the Non-U.S. Holder
172
Table of Contents
maintains a permanent establishment in the United States to which such dividends are attributable), the Non-U.S. Holder will be exempt from the U.S. federal withholding tax described above. To claim the exemption, the Non-U.S. Holder must furnish to the applicable withholding agent a valid IRS Form W-8ECI, certifying that the dividends are effectively connected with the Non-U.S. Holder’s conduct of a trade or business within the United States.
Any such effectively connected dividends will be subject to U.S. federal income tax on a net income basis at the regular graduated rates. A Non-U.S. Holder that is a corporation also may be subject to a branch profits tax at a rate of 30% (or such lower rate specified by an applicable income tax treaty) on such effectively connected dividends, as adjusted for certain items. Non-U.S. Holders should consult their tax advisors regarding any applicable tax treaties that may provide for different rules.
Sale or Other Taxable Disposition
Subject to the discussion below on information reporting, backup withholding and foreign accounts, a Non-U.S. Holder will not be subject to U.S. federal income tax on any gain realized upon the sale or other taxable disposition of our Class A common stock unless:
| • | the gain is effectively connected with the Non-U.S. Holder’s conduct of a trade or business within the United States (and, if required by an applicable income tax treaty, the Non-U.S. Holder maintains a permanent establishment in the United States to which such gain is attributable); |
| • | the Non-U.S. Holder is a nonresident alien individual present in the United States for 183 days or more during the taxable year of the disposition and certain other requirements are met; or |
| • | our Class A common stock constitutes a U.S. real property interest (“USRPI”) by reason of our status as a U.S. real property holding corporation (“USRPHC”) for U.S. federal income tax purposes and as a result such gain is treated as effectively connected with a trade or business conducted by the Non-U.S. Holder in the United States. |
Gain described in the first bullet point above generally will be subject to U.S. federal income tax on a net income basis in the manner and at the regular graduated rates applicable to U.S. persons. A Non-U.S. Holder that is a corporation also may be subject to a branch profits tax at a rate of 30% (or such lower rate specified by an applicable income tax treaty) on such effectively connected gain, as adjusted for certain items.
A Non-U.S. Holder described in the second bullet point above will be subject to U.S. federal income tax at a rate of 30% (or such lower rate specified by an applicable income tax treaty) on gain realized upon the sale or other taxable disposition of our Class A common stock, which may be offset by U.S. source capital losses of the Non-U.S. Holder (even though the individual is not considered a resident of the United States), provided the Non-U.S. Holder has timely filed U.S. federal income tax returns with respect to such losses.
With respect to the third bullet point above, we believe we currently are not, and do not anticipate becoming, a USRPHC. Because the determination of whether we are a USRPHC depends, however, on the fair market value of our USRPIs relative to the fair market value of our non-U.S. real property interests and our other business assets, there can be no assurance we currently are not a USRPHC or will not become one in the future. Even if we are or were to become a USRPHC, gain arising from the sale or other taxable disposition of our Class A common stock by a Non-U.S. Holder would not be subject to U.S. federal income tax so long as our Class A common stock is “regularly traded,” as defined by applicable Treasury Regulations, on an established securities market, and such Non-U.S. Holder owned, actually and constructively, 5% or less of our Class A common stock throughout the shorter of the five-year period ending on the date of the sale or other taxable disposition or the Non-U.S. Holder’s holding period.
173
Table of Contents
Non-U.S. Holders should consult their tax advisors regarding potentially applicable income tax treaties that may provide for different rules.
Information Reporting and Backup Withholding
Payments of dividends on our Class A common stock will not be subject to backup withholding, provided the applicable withholding agent does not have actual knowledge or reason to know the holder is a United States person and the holder either certifies its non-U.S. status, such as by furnishing a valid IRS Form W-8BEN, W-8BEN-E or W-8ECI, or other applicable documentation, or otherwise establishes an exemption. However, information returns are required to be filed with the IRS in connection with any dividends on our Class A common stock paid to the Non-U.S. Holder, regardless of whether any tax was actually withheld. In addition, proceeds of the sale or other taxable disposition of our Class A common stock within the United States or conducted through certain U.S.-related brokers generally will not be subject to backup withholding or information reporting, if the applicable withholding agent receives the certification described above and does not have actual knowledge or reason to know that such holder is a United States person, or the holder otherwise establishes an exemption. Proceeds of a disposition of our Class A common stock conducted through a non-U.S. office of a non-U.S. broker generally will not be subject to backup withholding or information reporting.
Copies of information returns that are filed with the IRS may also be made available under the provisions of an applicable treaty or agreement to the tax authorities of the country in which the Non-U.S. Holder resides or is established.
Backup withholding is not an additional tax. Any amounts withheld under the backup withholding rules may be allowed as a refund or a credit against a Non-U.S. Holder’s U.S. federal income tax liability, provided the required information is timely furnished to the IRS.
Additional Withholding Tax on Payments Made to Foreign Accounts
Withholding taxes may be imposed under Sections 1471 to 1474 of the Code (such Sections commonly referred to as the Foreign Account Tax Compliance Act, or “FATCA”) on certain types of payments made to non-U.S. financial institutions and certain other non-U.S. entities. Specifically, a 30% withholding tax may be imposed on dividends on, or (subject to the proposed Treasury Regulations discussed below) gross proceeds from the sale or other disposition of, our Class A common stock paid to a “foreign financial institution” or a “non-financial foreign entity” (each as defined in the Code), unless (1) the foreign financial institution undertakes certain diligence and reporting obligations, (2) the non-financial foreign entity either certifies it does not have any “substantial United States owners” (as defined in the Code) or furnishes identifying information regarding each substantial United States owner, or (3) the foreign financial institution or non-financial foreign entity otherwise qualifies for an exemption from these rules. If the payee is a foreign financial institution and is subject to the diligence and reporting requirements in (1) above, it must enter into an agreement with the U.S. Department of the Treasury requiring, among other things, that it undertake to identify accounts held by certain “specified United States persons” or “United States–owned foreign entities” (each as defined in the Code), annually report certain information about such accounts, and withhold 30% on certain payments to non-compliant foreign financial institutions and certain other account holders. Foreign financial institutions located in jurisdictions that have an intergovernmental agreement with the United States governing FATCA may be subject to different rules.
Under the applicable Treasury Regulations and administrative guidance, withholding under FATCA generally applies to payments of dividends on our Class A common stock. While withholding under FATCA would also have applied to payments of gross proceeds from the sale or other disposition of stock on or after January 1, 2019,
174
Table of Contents
proposed Treasury Regulations eliminate FATCA withholding on payments of gross proceeds entirely. Taxpayers generally may rely on these proposed Treasury Regulations until final Treasury Regulations are issued.
Prospective investors should consult their tax advisors regarding the potential application of withholding under FATCA to their investment in our Class A common stock.
175
Table of Contents
We are offering the shares of common stock described in this prospectus through a number of underwriters. J.P. Morgan Securities LLC and Jefferies LLC are acting as joint book-running managers of the offering and as representatives of the underwriters. We have entered into an underwriting agreement with the underwriters. Subject to the terms and conditions of the underwriting agreement, we have agreed to sell to the underwriters, and each underwriter has severally agreed to purchase, at the public offering price less the underwriting discounts and commissions set forth on the cover page of this prospectus, the number of shares of Class A common stock listed next to its name in the following table:
| Name | Number of Shares |
|||
| J.P. Morgan Securities LLC |
||||
| Jefferies LLC |
||||
| RBC Capital Markets, LLC |
||||
| UBS Securities LLC |
||||
| KeyBanc Capital Markets Inc. |
||||
| Nomura Securities International, Inc. |
||||
| WR Securities, LLC |
||||
| Robert W. Baird & Co. Incorporated |
||||
| Needham & Company, LLC |
||||
| Roth Capital Partners, LLC |
||||
| Total |
||||
The underwriters are committed to purchase all the common shares offered by us if they purchase any shares. The underwriting agreement also provides that if an underwriter defaults, the purchase commitments of non-defaulting underwriters may also be increased or the offering may be terminated.
The underwriters propose to offer the common shares directly to the public at the initial public offering price set forth on the cover page of this prospectus and to certain dealers at that price less a concession not in excess of $ per share. Any such dealers may resell shares to certain other brokers or dealers at a discount of up to $ per share from the initial public offering price. After the initial offering of the shares to the public, if all of the common shares are not sold at the initial public offering price, the underwriters may change the offering price and the other selling terms. Sales of any shares made outside of the United States may be made by affiliates of the underwriters.
The underwriters have an option to buy up to additional shares of Class A common stock from the selling shareholders to cover sales of shares by the underwriters which exceed the number of shares specified in the table above. The underwriters have 30 days from the date of this prospectus to exercise this option to purchase additional shares. If any shares are purchased with this option to purchase additional shares, the underwriters will purchase shares in approximately the same proportion as shown in the table above. If any additional shares of Class A common stock are purchased, the underwriters will offer the additional shares on the same terms as those on which the shares are being offered.
The underwriting fee is equal to the public offering price per share of Class A common stock less the amount paid by the underwriters to us per share of Class A common stock. The underwriting fee is $ per share. The following table shows the per share and total underwriting discounts and commissions to be paid to the underwriters assuming both no exercise and full exercise of the underwriters’ option to purchase additional shares.
176
Table of Contents
| Without option to purchase additional shares exercise |
With full option to purchase additional shares exercise |
|||||||
| Per Share |
$ | $ | ||||||
| Total |
$ | $ | ||||||
We estimate that the total expenses of this offering, including registration, filing and listing fees, printing fees and legal and accounting expenses, but excluding the underwriting discounts and commissions, will be approximately $ . We have also agreed to reimburse the underwriters for certain expenses, including those related to the Financial Industry Regulatory Authority, Inc., incurred by them in connection with this offering.
A prospectus in electronic format may be made available on the web sites maintained by one or more underwriters, or selling group members, if any, participating in the offering. The underwriters may agree to allocate a number of shares to underwriters and selling group members for sale to their online brokerage account holders. Internet distributions will be allocated by the representatives to underwriters and selling group members that may make Internet distributions on the same basis as other allocations.
We have agreed that we will not (i) offer, pledge, sell, contract to sell, sell any option or contract to purchase, purchase any option or contract to sell, grant any option, right or warrant to purchase, lend or otherwise transfer or dispose of, directly or indirectly, or submit to, or file with, the Securities and Exchange Commission a registration statement under the Securities Act relating to, any shares of our Class A common stock or securities convertible into or exercisable or exchangeable for any shares of our Class A common stock, or publicly disclose the intention to make any offer, sale, pledge, loan, disposition or filing, or (ii) enter into any swap or other arrangement that transfers all or a portion of the economic consequences associated with the ownership of any shares of Class A common stock or any such other securities (regardless of whether any of these transactions are to be settled by the delivery of shares of Class A common stock or such other securities, in cash or otherwise), in each case without the prior written consent of J.P. Morgan Securities LLC and Jefferies LLC for a period of 180 days after the date of this prospectus, other than the shares of our Class A common stock to be sold in this offering.
The restrictions on our actions, as described above, do not apply to certain transactions, including (i) the issuance of shares of Class A common stock or securities convertible into or exercisable for shares of our Class A common stock pursuant to the conversion or exchange of convertible or exchangeable securities or the exercise of warrants or options (including net exercise) or the settlement of RSUs (including net settlement), in each case outstanding on the date of the underwriting agreement and described in this prospectus; (ii) grants of stock options, stock awards, restricted stock, RSUs, or other equity awards and the issuance of shares of our Class A common stock or securities convertible into or exercisable or exchangeable for shares of our Class A common stock (whether upon the exercise of stock options or otherwise) to our employees, officers, directors, advisors, or consultants pursuant to the terms of an equity compensation plan in effect as of the closing of this offering and described in this prospectus, provided that such recipients enter into a lock-up agreement with the underwriters; or (iii) our filing of any registration statement on Form S-8 relating to securities granted or to be granted pursuant to any plan in effect on the date of the underwriting agreement and described in this prospectus or any assumed benefit plan pursuant to an acquisition or similar strategic transaction.
Our directors and executive officers, and substantially all of our shareholders (such persons, the “lock-up parties”) have entered into lock-up agreements with the underwriters prior to the commencement of this offering pursuant to which each lock-up party, with limited exceptions, for a period of 180 days after the date of
177
Table of Contents
this prospectus (such period, the “restricted period”), may not (and may not cause any of their direct or indirect affiliates to), without the prior written consent of J.P. Morgan Securities LLC and Jefferies LLC, (1) offer, pledge, sell, contract to sell, sell any option or contract to purchase, purchase any option or contract to sell, grant any option, right or warrant to purchase, lend or otherwise transfer or dispose of, directly or indirectly, any shares of our Class A common stock or any securities convertible into or exercisable or exchangeable for our Class A common stock (including, without limitation, Class A common stock or such other securities which may be deemed to be beneficially owned by such lock-up parties in accordance with the rules and regulations of the SEC and securities which may be issued upon exercise of a stock option or warrant (collectively with the Class A common stock, the “lock-up securities”)), (2) enter into any hedging, swap or other agreement or transaction that transfers, in whole or in part, any of the economic consequences of ownership of the lock-up securities, whether any such transaction described in clause (1) or (2) above is to be settled by delivery of lock-up securities, in cash or otherwise, (3) make any demand for, or exercise any right with respect to, the registration of any lock-up securities, or (4) publicly disclose the intention to do any of the foregoing. Such persons or entities have further acknowledged that these undertakings preclude them from engaging in any hedging or other transactions or arrangements (including, without limitation, any short sale or the purchase or sale of, or entry into, any put or call option, or combination thereof, forward, swap or any other derivative transaction or instrument, however described or defined) designed or intended, or which could reasonably be expected to lead to or result in, a sale or disposition or transfer (by any person or entity, whether or not a signatory to such agreement) of any economic consequences of ownership, in whole or in part, directly or indirectly, of any lock-up securities, whether any such transaction or arrangement (or instrument provided for thereunder) would be settled by delivery of lock-up securities, in cash or otherwise.
The restrictions described in the immediately preceding paragraph and contained in the lock-up agreements between the underwriters and the lock-up parties do not apply, subject in certain cases to various conditions, to certain transactions, including (a) transfers of lock-up securities: (i) as bona fide gifts, or for bona fide estate planning purposes, (ii) by will or intestacy, (iii) to any trust for the direct or indirect benefit of the lock-up party or any immediate family member, (iv) to a partnership, limited liability company or other entity of which the lock-up party and its immediate family members are the legal and beneficial owner of all of the outstanding equity securities or similar interests, (v) to a nominee or custodian of a person or entity to whom a disposition or transfer would be permissible under clauses (i) through (iv), (vi) in the case of a corporation, partnership, limited liability company, trust or other business entity, (A) to another corporation, partnership, limited liability company, trust or other business entity that is an affiliate of the lock-up party, or to any investment fund or other entity controlling, controlled by, managing or managed by or under common control with the lock-up party or its affiliates or (B) as part of a distribution to members or shareholders of the lock-up party; (vii) by operation of law, (viii) to us from an employee upon death, disability or termination of employment of such employee, (ix) as part of a sale of lock-up securities acquired in open market transactions after the completion of this offering, (x) to us in connection with the vesting, settlement or exercise of restricted stock units, options, warrants or other rights to purchase shares of our Class A common stock (including “net” or “cashless” exercise), including for the payment of exercise price and tax and remittance payments, or (xi) pursuant to a bona fide third-party tender offer, merger, consolidation or other similar transaction approved by our board of directors and made to all shareholders involving a change in control, provided that if such transaction is not completed, all such lock-up securities would remain subject to the restrictions in the immediately preceding paragraph; (b) exercise of the options, settlement of RSUs or other equity awards, or the exercise of warrants granted pursuant to plans described in this prospectus, provided that any lock-up securities received upon such exercise, vesting or settlement would be subject to restrictions similar to those in the immediately preceding paragraph; (c) the conversion of outstanding preferred stock, warrants to acquire preferred stock, or convertible securities into shares of our Class A common stock or warrants to acquire shares of our Class A common stock, provided that any Class A common stock or warrant received upon such conversion would be
178
Table of Contents
subject to restrictions similar to those in the immediately preceding paragraph; and (d) the establishment by lock-up parties of trading plans under Rule 10b5-1 under the Exchange Act, provided that such plan does not provide for the transfer of lock-up securities during the restricted period.
J.P. Morgan Securities LLC and Jefferies LLC, in their sole discretion, may release the securities subject to any of the lock-up agreements with the underwriters described above, in whole or in part at any time.
We have a large number of shareholders and such shareholders have acquired their interests over an extended period of time and pursuant to a number of different agreements containing a variety of terms governing restrictions on the sale, short sale, transfer, hedging, pledging, loan or other disposition of their interests in our equity. Record holders of our outstanding shares of Class A common stock and securities convertible into or exercisable or exchangeable for shares of our Class A common stock are subject to restrictions on their ability to sell or transfer their equity during a period preceding the pricing of this offering or the 180-day period following the pricing of this offering. During such pre-pricing period, record holders of approximately % of our outstanding equity interests on a fully diluted basis are subject to the restrictions on the sale, transfer, short sale, hedging, pledging, lending or other disposition of their equity interests imposed by either (i) lock-up agreements with the underwriters that are effective when signed, and which were signed on or prior to , (ii) market standoff agreements with us, or (iii) agreements that subject their equity interests to transfer restrictions set forth in our bylaws. During the post-pricing period (and before giving effect to the shares sold in the offering), (i) approximately % of our outstanding registered equity interests are subject to restrictions imposed by lock-up agreements with the underwriters, (ii) an additional approximately % are subject to the market standoff provisions in our investors’ rights agreement, which imposes restrictions on the sale, short sale, loan, granting of any option to purchase, or other disposition of any of our securities, or entering into any swap or other arrangement that transfers to another, in whole or in part, any of the economic consequences of ownership of our securities, and (iii) the remaining approximately % are subject to restrictions contained in a variety of market standoff agreements with us which include restrictions on the sale, short sale, loan, granting of any option to purchase, or other disposition of our securities, and in some cases other restrictions. The forms and specific restrictive provisions within these market standoff provisions vary significantly between shareholders. For example, some of these market standoff agreements do not specifically restrict hedging transactions and others may be subject to different interpretations between us and shareholders as to whether they restrict hedging.
Record holders of our securities are typically the parties to the lock-up agreements with the underwriters and the market standoff agreements with us referred to above, while holders of beneficial interests in our shares who are not also record holders in respect of such shares are not typically subject to any such agreements or other similar restrictions. Accordingly, we believe that certain holders of beneficial interests who are not record holders and are not bound by market standoff or lock-up agreements could enter into transactions with respect to those beneficial interests that negatively impact our stock price. In addition, any shareholder who is neither subject to a market standoff agreement with us nor a lock-up agreement with the underwriters may be able to sell, short sell, transfer, hedge, pledge, lend or otherwise dispose of or attempt to sell short sell, transfer, hedge, pledge, lend or otherwise dispose of, their equity interests at any time after the closing of this offering.
We have agreed to indemnify the underwriters against certain liabilities, including liabilities under the Securities Act of 1933.
We have applied to have our Class A common stock approved for listing/quotation on NYSE under the symbol “KVLT”.
In connection with this offering, the underwriters may engage in stabilizing transactions, which involves making bids for, purchasing and selling shares of Class A common stock in the open market for the purpose of
179
Table of Contents
preventing or retarding a decline in the market price of the Class A common stock while this offering is in progress. These stabilizing transactions may include making short sales of Class A common stock, which involves the sale by the underwriters of a greater number of shares of Class A common stock than they are required to purchase in this offering, and purchasing shares of Class A common stock on the open market to cover positions created by short sales. Short sales may be “covered” shorts, which are short positions in an amount not greater than the underwriters’ option to purchase additional shares referred to above, or may be “naked” shorts, which are short positions in excess of that amount. The underwriters may close out any covered short position either by exercising their option to purchase additional shares, in whole or in part, or by purchasing shares in the open market. In making this determination, the underwriters will consider, among other things, the price of shares available for purchase in the open market compared to the price at which the underwriters may purchase shares through the option to purchase additional shares. A naked short position is more likely to be created if the underwriters are concerned that there may be downward pressure on the price of the Class A common stock in the open market that could adversely affect investors who purchase in this offering. To the extent that the underwriters create a naked short position, they will purchase shares in the open market to cover the position.
The underwriters have advised us that, pursuant to Regulation M of the Securities Act of 1933, they may also engage in other activities that stabilize, maintain or otherwise affect the price of the Class A common stock, including the imposition of penalty bids. This means that if the representatives of the underwriters purchase Class A common stock in the open market in stabilizing transactions or to cover short sales, the representatives can require the underwriters that sold those shares as part of this offering to repay the underwriting discount received by them.
These activities may have the effect of raising or maintaining the market price of the Class A common stock or preventing or retarding a decline in the market price of the Class A common stock, and, as a result, the price of the Class A common stock may be higher than the price that otherwise might exist in the open market. If the underwriters commence these activities, they may discontinue them at any time. The underwriters may carry out these transactions on the NYSE, in the over-the-counter market or otherwise.
Prior to this offering, there has been no public market for our Class A common stock. The initial public offering price will be determined by negotiations between us and the representatives of the underwriters. In determining the initial public offering price, we and the representatives of the underwriters expect to consider a number of factors including:
| • | the information set forth in this prospectus and otherwise available to the representatives; |
| • | our prospects and the history and prospects for the industry in which we compete; |
| • | an assessment of our management; |
| • | our prospects for future earnings; |
| • | the general condition of the securities markets at the time of this offering; |
| • | the recent market prices of, and demand for, publicly traded Class A common stock of generally comparable companies; and |
| • | other factors deemed relevant by the underwriters and us. |
Neither we nor the underwriters can assure investors that an active trading market will develop for our common shares, or that the shares will trade in the public market at or above the initial public offering price.
Other than in the United States, no action has been taken by us or the underwriters that would permit a public offering of the securities offered by this prospectus in any jurisdiction where action for that purpose is required.
180
Table of Contents
The securities offered by this prospectus may not be offered or sold, directly or indirectly, nor may this prospectus or any other offering material or advertisements in connection with the offer and sale of any such securities be distributed or published in any jurisdiction, except under circumstances that will result in compliance with the applicable rules and regulations of that jurisdiction. Persons into whose possession this prospectus comes are advised to inform themselves about and to observe any restrictions relating to the offering and the distribution of this prospectus. This prospectus does not constitute an offer to sell or a solicitation of an offer to buy any securities offered by this prospectus in any jurisdiction in which such an offer or a solicitation is unlawful.
Directed Share Program
At our request, the underwriters have reserved for sale at the initial public offering price up to % of the Class A common stock being offered for sale, to our directors, officers, and certain employees and other related parties. The sales will be made at our direction by , an underwriter of this offering, and its affiliates through a directed share program. The number of shares of Class A common stock available for sale to the general public will be reduced to the extent these individuals purchase such reserved shares. Any reserved shares that are not so purchased will be offered by the underwriters to the general public on the same basis as the other shares offered by this prospectus. Except for any shares acquired by our directors and officers, shares purchased pursuant to the directed share program will not be subject to lock-up agreements with the underwriters. Other than the underwriting discount described on the front cover of this prospectus, the underwriters will not be entitled to any commission with respect to shares of Class A common stock sold pursuant to the directed share program.
Other Activities and Relationships
The underwriters and certain of their affiliates are full service financial institutions engaged in various activities, which may include securities trading, commercial and investment banking, financial advisory, investment management, investment research, principal investment, hedging, financing and brokerage activities. The underwriters and certain of their affiliates have, from time to time, performed, and may in the future perform, various commercial and investment banking and financial advisory services for us and our affiliates, for which they received or will receive customary fees and expenses.
In the ordinary course of their various business activities, the underwriters and certain of their affiliates may make or hold a broad array of investments and actively trade debt and equity securities (or related derivative securities) and financial instruments (including bank loans) for their own account and for the accounts of their customers, and such investment and securities activities may involve securities and/or instruments issued by us and our affiliates. If the underwriters or their respective affiliates have a lending relationship with us, they routinely hedge their credit exposure to us consistent with their customary risk management policies. The underwriters and their respective affiliates may hedge such exposure by entering into transactions which consist of either the purchase of credit default swaps or the creation of short positions in our securities or the securities of our affiliates, including potentially the Class A common stock offered hereby. Any such short positions could adversely affect future trading prices of the Class A common stock offered hereby. The underwriters and certain of their respective affiliates may also communicate independent investment recommendations, market color or trading ideas and/or publish or express independent research views in respect of such securities or instruments and may at any time hold, or recommend to clients that they acquire, long and/or short positions in such securities and instruments.
“Wolfe | Nomura Alliance” is the marketing name used by Wolfe Research Securities and Nomura Securities International, Inc. in connection with certain equity capital markets activities conducted jointly by the firms.
181
Table of Contents
Both Nomura Securities International, Inc. and WR Securities, LLC are serving as underwriters in the offering described herein. In addition, WR Securities, LLC and certain of its affiliates may provide sales support services, investor feedback, investor education, and/or other independent equity research services in connection with this offering.
Selling Restrictions
Other than in the United States, no action has been taken by us or the underwriters that would permit a public offering of the securities offered by this prospectus in any jurisdiction where action for that purpose is required. The securities offered by this prospectus may not be offered or sold, directly or indirectly, nor may this prospectus or any other offering material or advertisements in connection with the offer and sale of any such securities be distributed or published in any jurisdiction, except under circumstances that will result in compliance with the applicable rules and regulations of that jurisdiction. Persons into whose possession this prospectus comes are advised to inform themselves about and to observe any restrictions relating to the offering and the distribution of this prospectus. This prospectus does not constitute an offer to sell or a solicitation of an offer to buy any securities offered by this prospectus in any jurisdiction in which such an offer or a solicitation is unlawful.
European Economic Area
In relation to each Member State of the European Economic Area (each a “Relevant State”), no Class A common stock has been offered or will be offered pursuant to the offering to the public in that Relevant State prior to the publication of a prospectus in relation to the Class A common stock which has been approved by the competent authority in that Relevant State or, where appropriate, approved in another Relevant State and notified to the competent authority in that Relevant State, all in accordance with the Prospectus Regulation, except that offers of Class A common stock may be made to the public in that Relevant State at any time under the following exemptions under the Prospectus Regulation:
| (a) | to any legal entity which is a qualified investor as defined under Article 2 of the Prospectus Regulation; |
| (b) | to fewer than 150 natural or legal persons (other than qualified investors as defined under Article 2 of the Prospectus Regulation), subject to obtaining the prior consent of the representatives for any such offer; or |
| (c) | in any other circumstances falling within Article 1(4) of the Prospectus Regulation, |
provided that no such offer of Class A common stock shall require us or any representative to publish a prospectus pursuant to Article 3 of the Prospectus Regulation or supplement a prospectus pursuant to Article 23 of the Prospectus Regulation, and each person who initially acquires any Class A common stock or to whom any offer is made will be deemed to have represented, acknowledged and agreed to and with each of the representatives and us that it is a “qualified investor” within the meaning of Article 2(e) of the Prospectus Regulation. In the case of any Class A common stock being offered to a financial intermediary as that term is used in the Prospectus Regulation, each such financial intermediary will be deemed to have represented, acknowledged and agreed that the Class A common stock acquired by it in the offer have not been acquired on a non-discretionary basis on behalf of, nor have they been acquired with a view to their offer or resale to, persons in circumstances which may give rise to an offer of any Class A common stock to the public other than their offer or resale in a Relevant State to qualified investors as so defined or in circumstances in which the prior consent of the representatives has been obtained to each such proposed offer or resale.
For the purposes of this provision, the expression an “offer to the public” in relation to any Class A common stock in any Relevant State means the communication in any form and by any means of sufficient information
182
Table of Contents
on the terms of the offer and any Class A common stock to be offered so as to enable an investor to decide to purchase or subscribe for any Class A common stock, and the expression “Prospectus Regulation” means Regulation (EU) 2017/1129.
United Kingdom
No Class A common stock has been offered or will be offered pursuant to the offering to the public in the United Kingdom prior to the publication of a prospectus in relation to the Class A common stock which (i) has been approved by the Financial Conduct Authority or (ii) is to be treated as if it had been approved by the Financial Conduct Authority in accordance with the transitional provisions in Article 74 (transitional provisions) of the Prospectus Amendment etc. (EU Exit) Regulations 2019/1234, except that the Class A common stock may be offered to the public in the United Kingdom at any time:
| (a) | to any legal entity which is a qualified investor as defined under Article 2 of the UK Prospectus Regulation; |
| (b) | to fewer than 150 natural or legal persons (other than qualified investors as defined under Article 2 of the UK Prospectus Regulation), subject to obtaining the prior consent of the representatives for any such offer; or |
| (c) | in any other circumstances falling within Section 86 of the Financial Services and Markets Act 2000 (“FSMA”). |
provided that no such offer of the Class A common stock shall require us or any representative to publish a prospectus pursuant to Section 85 of the FSMA or supplement a prospectus pursuant to Article 23 of the UK Prospectus Regulation. For the purposes of this provision, the expression an “offer to the public” in relation to the Class A common stock in the United Kingdom means the communication in any form and by any means of sufficient information on the terms of the offer and any Class A common stock to be offered so as to enable an investor to decide to purchase or subscribe for any Class A common stock and the expression “UK Prospectus Regulation” means Regulation (EU) 2017/1129 as it forms part of domestic law by virtue of the European Union (Withdrawal) Act 2018.
In addition, in the United Kingdom, this document is being distributed only to, and is directed only at, and any offer subsequently made may only be directed at persons who are “qualified investors” (as defined in the Prospectus Regulation) (i) who have professional experience in matters relating to investments falling within Article 19(5) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005, as amended (the “Order”) and/or (ii) who are high net worth companies (or persons to whom it may otherwise be lawfully communicated) falling within Article 49(2)(a) to (d) of the Order (all such persons together being referred to as “relevant persons”) or otherwise in circumstances which have not resulted and will not result in an offer to the public of the Class A common stock in the United Kingdom within the meaning of the FSMA. Any person in the United Kingdom that is not a relevant person should not act or rely on the information included in this document or use it as basis for taking any action. In the United Kingdom, any investment or investment activity that this document relates to may be made or taken exclusively by relevant persons.
Canada
The Class A common stock may be sold in Canada only to purchasers purchasing, or deemed to be purchasing, as principal that are accredited investors, as defined in National Instrument 45-106 Prospectus Exemptions or subsection 73.3(1) of the Securities Act (Ontario), and are permitted clients, as defined in National Instrument 31-103 Registration Requirements, Exemptions and Ongoing Registrant Obligations. Any resale of the Class A common stock must be made in accordance with an exemption from, or in a transaction not subject to, the prospectus requirements of applicable securities laws.
183
Table of Contents
Securities legislation in certain provinces or territories of Canada may provide a purchaser with remedies for rescission or damages if this prospectus (including any amendment thereto) contains a misrepresentation, provided that the remedies for rescission or damages are exercised by the purchaser within the time limit prescribed by the securities legislation of the purchaser’s province or territory. The purchaser should refer to any applicable provisions of the securities legislation of the purchaser’s province or territory for particulars of these rights or consult with a legal advisor.
Pursuant to section 3A.3 of National Instrument 33-105 Underwriting Conflicts (NI 33-105), the underwriters are not required to comply with the disclosure requirements of NI 33-105 regarding underwriter conflicts of interest in connection with this offering.
Hong Kong
The Class A common stock has not been offered or sold and will not be offered or sold in Hong Kong, by means of any document, other than (a) to “professional investors” as defined in the Securities and Futures Ordinance (Cap. 571 of the Laws of Hong Kong) (the “SFO”) of Hong Kong and any rules made thereunder; or (b) in other circumstances which do not result in the document being a “prospectus” as defined in the Companies (Winding Up and Miscellaneous Provisions) Ordinance (Cap. 32) of Hong Kong (the “CO”) or which do not constitute an offer to the public within the meaning of the CO. No advertisement, invitation or document relating to the Class A common stock has been or may be issued or has been or may be in the possession of any person for the purposes of issue, whether in Hong Kong or elsewhere, which is directed at, or the contents of which are likely to be accessed or read by, the public of Hong Kong (except if permitted to do so under the securities laws of Hong Kong) other than with respect to Class A common stock which are or are intended to be disposed of only to persons outside Hong Kong or only to “professional investors” as defined in the SFO and any rules made thereunder.
Singapore
This prospectus has not been registered as a prospectus with the Monetary Authority of Singapore. Accordingly, no Class A common stock has been or will be offered or sold and no Class A common stock has been or will be made the subject of an invitation for subscription or purchase, and no prospectus or any other document or material in connection with the offer or sale, or invitation for subscription or purchase, of the Class A common stock, has been or will be circulated or distributed, whether directly or indirectly, to any person in Singapore other than (i) to an institutional investor (as defined in Section 4A of the Securities and Futures Act 2001 of Singapore, as modified or amended from time to time (the “SFA”)) pursuant to Section 274 of the SFA or (ii) to an accredited investor (as defined in Section 4A of the SFA) pursuant to and in accordance with the conditions specified in Section 275 of the SFA.
Singapore SFA Product Classification—In connection with Section 309B of the SFA and the CMP Regulations 2018, unless otherwise specified before an offer of Class A common stock, we have determined, and hereby notify all relevant persons (as defined in Section 309A(1) of the SFA), that the Class A common stock are “prescribed capital markets products” (as defined in the CMP Regulations 2018) and Excluded Investment Products (as defined in MAS Notice SFA 04-N12: Notice on the Sale of Investment Products and MAS Notice FAA-N16: Notice on Recommendations on Investment Products).
Japan
The Class A common stock has not been and will not be registered pursuant to Article 4, Paragraph 1 of the Financial Instruments and Exchange Act. Accordingly, none of the Class A common stock nor any interest
184
Table of Contents
therein may be offered or sold, directly or indirectly, in Japan or to, or for the benefit of, any “resident” of Japan (which term as used herein means any person resident in Japan, including any corporation or other entity organized under the laws of Japan), or to others for re-offering or resale, directly or indirectly, in Japan or to or for the benefit of a resident of Japan, except pursuant to an exemption from the registration requirements of, and otherwise in compliance with, the Financial Instruments and Exchange Act and any other applicable laws, regulations and ministerial guidelines of Japan in effect at the relevant time.
Switzerland
This prospectus does not constitute an offer to the public or a solicitation to purchase or invest in any Class A common stock. No Class A common stock has been offered or will be offered to the public in Switzerland, except that offers of Class A common stock may be made to the public in Switzerland at any time under the following exemptions under the Swiss Financial Services Act (“FinSA”):
| (a) | to any person which is a professional client as defined under the FinSA; |
| (b) | to fewer than 500 persons (other than professional clients as defined under the FinSA), subject to obtaining the prior consent of the representatives for any such offer; or |
| (c) | in any other circumstances falling within Article 36 FinSA in connection with Article 44 of the Swiss Financial Services Ordinance; |
provided that no such offer of Class A common stock shall require us or any representative to publish a prospectus pursuant to Article 35 FinSA.
The Class A common stock has not been and will not be listed or admitted to trading on a trading venue in Switzerland.
Neither this document nor any other offering or marketing material relating to the Class A common stock constitutes a prospectus as such term is understood pursuant to the FinSA, and neither this document nor any other offering or marketing material relating to the Class A common stock may be publicly distributed or otherwise made publicly available in Switzerland.
Dubai International Financial Centre
This prospectus relates to an Exempt Offer in accordance with the Markets Law, DIFC Law No. 1 of 2012, as amended. This prospectus is intended for distribution only to persons of a type specified in the Markets Law, DIFC Law No. 1 of 2012, as amended. It must not be delivered to, or relied on by, any other person. The Dubai Financial Services Authority (DFSA) has no responsibility for reviewing or verifying any documents in connection with Exempt Offers. The DFSA has not approved this prospectus nor taken steps to verify the information set forth herein and has no responsibility for this prospectus. The Class A common stock to which this prospectus relates may be illiquid and/or subject to restrictions on their resale. Prospective purchasers of the Class A common stock offered should conduct their own due diligence on the Class A common stock. If you do not understand the contents of this prospectus, you should consult an authorized financial advisor.
In relation to its use in the DIFC, this prospectus is strictly private and confidential and is being distributed to a limited number of investors and must not be provided to any person other than the original recipient, and may not be reproduced or used for any other purpose. The interests in the Class A common stock may not be offered or sold directly or indirectly to the public in the DIFC.
185
Table of Contents
Australia
This prospectus:
| (a) | does not constitute a disclosure document or a prospectus under Chapter 6D.2 of the Corporations Act 2001 (Cth) (the “Corporations Act”); |
| (b) | has not been, and will not be, lodged with the Australian Securities and Investments Commission (“ASIC”), as a disclosure document for the purposes of the Corporations Act and does not purport to include the information required of a disclosure document for the purposes of the Corporations Act; and |
| (c) | may only be provided in Australia to select investors who are able to demonstrate that they fall within one or more of the categories of investors, available under section 708 of the Corporations Act (“Exempt Investors”). |
The Class A common stock may not be directly or indirectly offered for subscription or purchased or sold, and no invitations to subscribe for or buy the Class A common stock may be issued, and no draft or definitive offering memorandum, advertisement or other offering material relating to any Class A common stock may be distributed in Australia, except where disclosure to investors is not required under Chapter 6D of the Corporations Act or is otherwise in compliance with all applicable Australian laws and regulations. By submitting an application for the Class A common stock, you represent and warrant to us that you are an Exempt Investor.
As any offer of Class A common stock under this document will be made without disclosure in Australia under Chapter 6D.2 of the Corporations Act, the offer of the Class A common stock for resale in Australia within 12 months may, under section 707 of the Corporations Act, require disclosure to investors under Chapter 6D.2 if none of the exemptions in section 708 applies to that resale. By applying for the Class A common stock, you undertake to us that you will not, for a period of 12 months from the date of issue of the Class A common stock, offer, transfer, assign or otherwise alienate those Class A common stock to investors in Australia except in circumstances where disclosure to investors is not required under Chapter 6D.2 of the Corporations Act or where a compliant disclosure document is prepared and lodged with ASIC.
Bermuda
The Class A common stock may be offered or sold in Bermuda only in compliance with the provisions of the Investment Business Act of 2003 of Bermuda which regulates the sale of securities in Bermuda. Additionally, non-Bermudian persons (including companies) may not carry on or engage in any trade or business in Bermuda unless such persons are permitted to do so under applicable Bermuda legislation.
Brazil
The offer and sale of the Class A common stock has not been and will not be registered with the Brazilian Securities Commission (Comissão de Valores Mobiliários, or “CVM”) and, therefore, will not be carried out by any means that would constitute a public offering in Brazil under CVM Resolution No. 160, dated July 13, 2022, as amended, or unauthorized distribution under Brazilian laws and regulations. The Class A common stock will be authorized for trading on organized non-Brazilian securities markets and may only be offered to Brazilian Professional Investors (as defined by applicable CVM regulation), who may only acquire the Class A common stock through a non-Brazilian account, with settlement outside Brazil in non-Brazilian currency. The trading of the Class A common stock on regulated securities markets in Brazil is prohibited.
Israel
In the State of Israel this prospectus shall not be regarded as an offer to the public to purchase shares of our Class A common stock under the Israeli Securities Law, 5728—1968, or the Israeli Securities Law, which requires
186
Table of Contents
a prospectus to be published and authorized by the Israel Securities Authority if it complies with certain provisions of Section 15 of the Israeli Securities Law, including, inter alia, if: (i) the offer is made, distributed or directed to not more than 35 investors, subject to certain conditions; or (ii) the offer is made, distributed or directed to certain qualified investors defined in the First Addendum of the Israeli Securities Law, subject to certain conditions. We have not and will not take any action that would require us to publish a prospectus in accordance with and subject to the Israeli Securities Law. We have not and will not distribute this prospectus or make, distribute or direct an offer to subscribe for our shares of Class A common stock to any person within the State of Israel.
187
Table of Contents
Table of Contents
The financial statement of CoVolt Power, Inc. as of April 22, 2026 included in this prospectus and in the
Registration Statement has been so included in reliance on the report of BDO USA, P.C., an independent
registered public accounting firm, given on the authority of said firm as experts in auditing and accounting.
The consolidated financial statements of CoVolt Holdings as of December 31, 2025 and 2024 and
for the years then ended included in this Prospectus and in the Registration Statement have been so included in
reliance on the reports of BDO USA, P.C., an independent registered public accounting firm, given on the
authority of said firm as experts in auditing and accounting.
189
Table of Contents
WHERE YOU CAN FIND MORE INFORMATION
We have filed with the Securities and Exchange Commission a registration statement on Form S-1 under the Securities Act with respect to the shares of Class A common stock offered hereby. This prospectus, which constitutes a part of the registration statement, does not contain all of the information set forth in the registration statement or the exhibits and schedules filed with the registration statement. For further information about us and the Class A common stock offered hereby, we refer you to the registration statement and the exhibits filed with the registration statement. Statements contained in this prospectus regarding the contents of any contract or any other document that is filed as an exhibit to the registration statement are not necessarily complete, and each such statement is qualified in all respects by reference to the full text of such contract or other document filed as an exhibit to the registration statement. The SEC also maintains an internet website that contains reports, proxy statements and other information about registrants, like us, that file electronically with the SEC. The address of that website is www.sec.gov.
Upon the closing of this offering, we will be required to file periodic reports, proxy statements, and other information with the SEC pursuant to the Exchange Act. These reports, proxy statements, and other information will be available on the website of the SEC referred to above.
We also maintain a website at http://www.covolt.com, through which you may access these materials free of charge as soon as reasonably practicable after they are electronically filed with, or furnished to, the SEC. Information contained on, or that can be accessed through, our website is not a part of this prospectus and the inclusion of our website address in this prospectus is an inactive textual reference only.
190
Table of Contents
INDEX TO CONSOLIDATED FINANCIAL STATEMENTS
F-1
Table of Contents
Report of Independent Registered Public Accounting Firm
Shareholders and Board of Managers
CoVolt Power, Inc.
Houston, Texas
Opinion on the Financial Statements
We have audited the accompanying balance sheet of CoVolt Power, Inc. (the “Company”) as of April 22, 2026, and the related notes (collectively referred to as the “financial statement”). In our opinion, the financial statement presents fairly, in all material respects, the financial position of the Company at April 22, 2026, in conformity with accounting principles generally accepted in the United States of America.
Basis for Opinion
The financial statement is the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s financial statement based on our audit. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audit in accordance with the standards of the PCAOB. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the financial statement is free of material misstatement, whether due to error or fraud. The Company is not required to have, nor were we engaged to perform, an audit of its internal control over financial reporting. As part of our audit we are required to obtain an understanding of internal control over financial reporting but not for the purpose of expressing an opinion on the effectiveness of the Company’s internal control over financial reporting. Accordingly, we express no such opinion.
Our audit included performing procedures to assess the risks of material misstatement of the financial statement, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the financial statement. Our audit also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the financial statement. We believe that our audit provides a reasonable basis for our opinion.
/s/ BDO USA, P.C.
We have served as the Company’s auditor since 2026.
Chicago, Illinois
June 12, 2026
F-2
Table of Contents
CoVolt Power, Inc.
(in dollars)
| April 22, | 2026 | |||
| Assets: |
||||
| Total assets |
$ | — | ||
| Liabilities and shareholders’ equity: |
||||
| Total liabilities |
$ | — | ||
| Shareholders’ equity: |
||||
| Deemed non-cash contribution |
(1,000 | ) | ||
| Common Stock, $0.01 par value per share, 100,000 shares authorized, issued, and outstanding |
1,000 | |||
| Additional paid-in capital |
— | |||
| Total liabilities and stockholders’ equity |
$ | — | ||
CoVolt Power, Inc. (the “Company”) was formed as a Texas corporation on April 22, 2026. The Company was formed for the purpose of completing a public offering and related transactions in order to carry on the business of CoVolt Holdings Group, LLC and its subsidiaries (“Holdings LLC”). As the sole managing member of Holdings LLC, the Company is expected to operate and control all of the business and affairs of Holdings LLC and, through Holdings LLC, continue to conduct the business historically conducted by these subsidiaries.
2. Summary of significant accounting policies
Basis of accounting and presentation
The balance sheet has been prepared in accordance with accounting principles generally accepted in the United States of America (“U.S. GAAP”). Separate statements of operations, comprehensive income, changes in stockholder’s equity, and cash flows have not been presented because there have been no activities in this entity as of April 22, 2026.
Use of Estimates
The preparation of financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the amounts reported herein. Actual results may differ materially from our estimates.
3. Common stock
As of April 22, 2026, the Company was authorized to issue 100,000 shares of common stock, par value $0.01 per share, and had 100,000 shares of common stock issued and outstanding. The Company was capitalized with a deemed non-cash contribution of $1,000 from Holdings LLC on April 22, 2026.
4. Commitments and contingencies
In the ordinary course of business, the Company may be subject to various legal, regulatory, and/or other administrative proceedings. There are currently no such proceedings to which the Company is a party.
F-3
Table of Contents
5. Subsequent Events
The Company has reviewed subsequent events through June 12, 2026, the date these consolidated financial statements were available to be issued and has identified no material subsequent events requiring disclosure other than the matters described elsewhere in the consolidated financial statements.
F-4
Table of Contents
CoVolt Power, Inc.
(in dollars, unaudited)
| June 30, | 2026 | |||
| Assets: |
||||
| Total assets |
$ | — | ||
| Liabilities and shareholders’ equity: |
||||
| Total liabilities |
$ | — | ||
| Shareholders’ equity: |
||||
| Deemed non-cash contribution |
(1,000 | ) | ||
| Common Stock, $0.01 par value per share, 100,000 shares authorized, issued, and outstanding |
1,000 | |||
| Additional paid-in capital |
— | |||
| Total liabilities and stockholders’ equity |
$ | — | ||
CoVolt Power, Inc. (the “Company”) was formed as a Texas corporation on April 22, 2026. The Company was formed for the purpose of completing a public offering and related transactions in order to carry on the business of CoVolt Holdings Group, LLC and its subsidiaries (“Holdings LLC”). As the sole managing member of Holdings LLC, the Company is expected to operate and control all of the business and affairs of Holdings LLC and, through Holdings LLC, continue to conduct the business historically conducted by these subsidiaries.
2. Summary of significant accounting policies
Basis of accounting and presentation
The balance sheet has been prepared in accordance with accounting principles generally accepted in the United States of America (“U.S. GAAP”). Separate statements of operations, comprehensive income, changes in stockholder’s equity, and cash flows have not been presented because there have been no activities in this entity as of June 30, 2026.
Use of Estimates
The preparation of financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the amounts reported herein. Actual results may differ materially from our estimates.
3. Common stock
As of June 30, 2026, the Company was authorized to issue 100,000 shares of common stock, par value $0.01 per share, and had 100,000 shares of common stock issued and outstanding. The Company was capitalized with a deemed non-cash contribution of $1,000 from Holdings LLC on April 22, 2026.
4. Commitments and contingencies
In the ordinary course of business, the Company may be subject to various legal, regulatory, and/or other administrative proceedings. There are currently no such proceedings to which the Company is a party.
F-5
Table of Contents
5. Subsequent Events
The Company has reviewed subsequent events through August 21, 2026, the date these consolidated financial statements were available to be issued and has identified no material subsequent events requiring disclosure other than the matters described elsewhere in the consolidated financial statements.
F-6
Table of Contents
Report of independent registered public accounting firm
Shareholders and Board of Managers
CoVolt Holdings Group, LLC
Houston, TX
Opinion on the consolidated financial statements
We have audited the accompanying consolidated balance sheets of CoVolt Holdings Group, LLC and Subsidiaries (the “Company”) as of December 31, 2025 and 2024, the related consolidated statements of operations, comprehensive income (loss), members’ equity, and cash flows for the years then ended, and the related notes (collectively referred to as the “consolidated financial statements”). In our opinion, the consolidated financial statements present fairly, in all material respects, the financial position of the Company at December 31, 2025 and 2024, and the results of its operations and its cash flows for the years then ended, in conformity with accounting principles generally accepted in the United States of America.
Basis for opinion
These consolidated financial statements are the responsibility of the Company’s management. Our responsibility is to express an opinion on the Company’s consolidated financial statements based on our audits. We are a public accounting firm registered with the Public Company Accounting Oversight Board (United States) (PCAOB) and are required to be independent with respect to the Company in accordance with the U.S. federal securities laws and the applicable rules and regulations of the Securities and Exchange Commission and the PCAOB.
We conducted our audits in accordance with the standards of the PCAOB and in accordance with auditing standards generally accepted in the United States of America. Those standards require that we plan and perform the audit to obtain reasonable assurance about whether the consolidated financial statements are free of material misstatement, whether due to error or fraud. The Company is not required to have, nor were we engaged to perform, an audit of its internal control over financial reporting. As part of our audits we are required to obtain an understanding of internal control over financial reporting but not for the purpose of expressing an opinion on the effectiveness of the Company’s internal control over financial reporting.
Accordingly, we express no such opinion.
Our audits included performing procedures to assess the risks of material misstatement of the consolidated financial statements, whether due to error or fraud, and performing procedures that respond to those risks. Such procedures included examining, on a test basis, evidence regarding the amounts and disclosures in the consolidated financial statements. Our audits also included evaluating the accounting principles used and significant estimates made by management, as well as evaluating the overall presentation of the consolidated financial statements. We believe that our audits provide a reasonable basis for our opinion.
/s/ BDO USA, P.C.
We have served as the Company’s auditor since 2020.
Chicago, Illinois
May 8, 2026
F-7
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
(In thousands)
| December 31, | 2025 | 2024 | ||||||
| Assets |
||||||||
| Current assets |
||||||||
| Cash and cash equivalents |
$ | 140,590 | $ | 84,691 | ||||
| Restricted cash |
10,494 | — | ||||||
| Accounts receivable, net |
42,929 | 69,533 | ||||||
| Contract assets |
12,485 | 19,941 | ||||||
| Other current assets |
19,320 | 43,650 | ||||||
| Total current assets |
225,818 | 217,815 | ||||||
| Property and equipment, net |
3,396 | 2,017 | ||||||
| Finance lease right-of-use assets, net |
5,263 | 6,404 | ||||||
| Operating lease right-of-use assets |
2,049 | 568 | ||||||
| Goodwill |
62,852 | 62,852 | ||||||
| Other intangible assets, net |
3,583 | 11,314 | ||||||
| Other non-current assets |
147 | 212 | ||||||
| Total assets |
$ | 303,108 | $ | 301,182 | ||||
| Liabilities and members’ equity |
||||||||
| Current liabilities |
||||||||
| Accounts payable |
$ | 75,572 | $ | 107,640 | ||||
| Contract liabilities |
93,039 | 123,263 | ||||||
| Accrued expenses and other |
24,897 | 15,088 | ||||||
| Finance lease liabilities, current portion |
1,706 | 1,951 | ||||||
| Operating lease liabilities, current portion |
50 | 545 | ||||||
| Total current liabilities |
195,264 | 248,487 | ||||||
| Finance lease liabilities, net of current portion |
1,430 | 1,486 | ||||||
| Operating lease liabilities, net of current portion |
2,083 | 50 | ||||||
| Other non-current liabilities |
2,241 | 2,226 | ||||||
| Total liabilities |
201,018 | 252,249 | ||||||
| Commitments and contingencies (note 11) |
||||||||
| Members’ equity |
||||||||
| Members’ equity: 100 authorized, issued, and outstanding units as of December 31, 2025 and 2024 |
104,152 | 51,062 | ||||||
| Accumulated other comprehensive loss |
(2,073 | ) | (2,140 | ) | ||||
| Total CoVolt Holdings Group, LLC |
102,079 | 48,922 | ||||||
| Non-controlling interests |
11 | 11 | ||||||
| Total members’ equity |
102,090 | 48,933 | ||||||
| Total liabilities and members’ equity |
$ | 303,108 | $ | 301,182 | ||||
See accompanying notes to consolidated financial statements.
F-8
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Consolidated statements of operations
(In thousands)
| Year ended December 31, | 2025 | 2024 | ||||||
| Revenue |
$ | 739,405 | $ | 442,724 | ||||
| Cost of revenue |
637,137 | 411,146 | ||||||
| Gross profit |
102,268 | 31,578 | ||||||
| General and administrative |
34,413 | 29,838 | ||||||
| Depreciation and amortization |
8,040 | 8,852 | ||||||
| Loss (gain) on disposal of assets |
69 | (165 | ) | |||||
| Operating income (loss) |
59,746 | (6,947 | ) | |||||
| Other income (expense) |
||||||||
| Interest income |
1,297 | 29 | ||||||
| Interest expense |
(654 | ) | (1,945 | ) | ||||
| Other income (expense), net |
192 | (146 | ) | |||||
| Total other income (expense) |
835 | (2,062 | ) | |||||
| Net income (loss) |
60,581 | (9,009 | ) | |||||
| Net income (loss) attributable to non-controlling interest |
— | — | ||||||
| Net income (loss) attributable to CoVolt Holdings Group, LLC |
$ | 60,581 | $ | (9,009 | ) | |||
See accompanying notes to consolidated financial statements.
F-9
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Consolidated statements of comprehensive income (loss)
(In thousands)
| Year ended December 31, | 2025 | 2024 | ||||||
| Net income (loss) |
$ | 60,581 | $ | (9,009 | ) | |||
| Other comprehensive income (loss) |
||||||||
| Foreign currency translation adjustment |
67 | (222 | ) | |||||
| Comprehensive income (loss) |
60,648 | (9,231 | ) | |||||
| Comprehensive income (loss) attributable to non-controlling interests |
— | — | ||||||
| Comprehensive income (loss) attributable to CoVolt Holdings Group, LLC |
$ | 60,648 | $ | (9,231 | ) | |||
See accompanying notes to consolidated financial statements.
F-10
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Consolidated statements of changes in members’ equity
(In thousands)
| Members’ equity |
Accumulated other comprehensive (loss) |
Non-controlling interests |
Total | |||||||||||||
| Balance, January 1, 2024 |
$ | 57,310 | $ | (1,918 | ) | $ | 11 | $ | 55,403 | |||||||
| Unit-based compensation |
2,761 | — | — | 2,761 | ||||||||||||
| Foreign currency translation adjustment |
— | (222 | ) | — | (222 | ) | ||||||||||
| Net loss |
(9,009 | ) | — | — | (9,009 | ) | ||||||||||
| Balance, December 31, 2024 |
51,062 | (2,140 | ) | 11 | 48,933 | |||||||||||
| Unit-based compensation |
601 | — | — | 601 | ||||||||||||
| Distributions to Parent |
(6,012 | ) | — | — | (6,012 | ) | ||||||||||
| Foreign currency translation adjustment |
— | 67 | — | 67 | ||||||||||||
| Repurchase of New Class B units |
(2,080 | ) | — | — | (2,080 | ) | ||||||||||
| Net income |
60,581 | — | — | 60,581 | ||||||||||||
| Balance, December 31, 2025 |
$ | 104,152 | $ | (2,073 | ) | $ | 11 | $ | 102,090 | |||||||
See accompanying notes to consolidated financial statements.
F-11
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Consolidated statements of cash flows
(In thousands)
| Year ended December 31, | 2025 | 2024 | ||||||
| Cash flows from operating activities |
||||||||
| Net income (loss) |
$ | 60,581 | $ | (9,009 | ) | |||
| Adjustments to reconcile net income (loss) to net cash provided by operating activities: |
||||||||
| Depreciation and amortization |
8,630 | 7,682 | ||||||
| Amortization of finance lease ROU assets |
2,080 | 3,031 | ||||||
| Amortization of deferred debt issuance costs |
548 | 291 | ||||||
| Loss (gain) on sale of property and equipment |
69 | (165 | ) | |||||
| Unit-based compensation |
601 | 2,761 | ||||||
| Changes in operating assets and liabilities: |
||||||||
| Accounts receivable |
26,604 | (38,194 | ) | |||||
| Contract assets |
7,455 | 7,966 | ||||||
| Accounts payable |
(32,068 | ) | 40,170 | |||||
| Contract liabilities |
(30,226 | ) | 64,515 | |||||
| Accrued expenses and other |
9,464 | (4,114 | ) | |||||
| Other current assets |
24,331 | (2,508 | ) | |||||
| Other non-current assets |
67 | (129 | ) | |||||
| Net cash provided by operating activities |
78,136 | 72,297 | ||||||
| Cash flows from investing activities |
||||||||
| Purchases of property and equipment |
(365 | ) | (266 | ) | ||||
| Proceeds from sale of property and equipment |
19 | 204 | ||||||
| Net cash used in investing activities |
(346 | ) | (62 | ) | ||||
| Cash flows from financing activities |
||||||||
| Payments on other non-current liability |
— | (360 | ) | |||||
| Distributions to Parent |
(6,012 | ) | — | |||||
| Repurchase of New Class B units |
(2,080 | ) | — | |||||
| Borrowings on revolving credit facility |
— | 123,000 | ||||||
| Repayments on revolving credit facility |
— | (163,113 | ) | |||||
| Payments of finance lease liabilities |
(3,372 | ) | (2,797 | ) | ||||
| Net cash used in financing activities |
(11,464 | ) | (43,270 | ) | ||||
| Effect of exchange rate on cash, cash equivalents, and restricted cash |
67 | (222 | ) | |||||
| Net increase in cash, cash equivalents, and restricted cash |
66,393 | 28,743 | ||||||
| Cash, cash equivalents, and restricted cash beginning of year |
84,691 | 55,948 | ||||||
| Cash, cash equivalents, and restricted cash end of year |
$ | 151,084 | $ | 84,691 | ||||
See accompanying notes to consolidated financial statements.
F-12
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Consolidated statements of cash flows – (continued)
(In thousands)
| Year ended December 31, | 2025 | 2024 | ||||||
| Supplemental disclosure of cash flow information |
||||||||
| Cash paid during the year for interest |
$ | 578 | $ | 1,646 | ||||
| Supplemental disclosure of non-cash activities |
||||||||
| Right-of-use assets obtained in exchange for new operating lease obligations |
$ | 2,010 | $ | — | ||||
| Right-of-use assets obtained in exchange for new finance lease obligations |
2,934 | 2,698 | ||||||
The table below provides a reconciliation of cash, cash equivalents, and restricted cash reported on the
consolidated balance sheets to the amount reported in the consolidated statements of cash flows for the
periods presented:
| Year ended December 31, | 2025 | 2024 | ||||||
| Cash and cash equivalents |
$ | 140,590 | $ | 84,691 | ||||
| Restricted cash(1) |
10,494 | — | ||||||
| Total cash, cash equivalents, and restricted cash shown in consolidated statements of cash flows |
$ | 151,084 | $ | 84,691 | ||||
| (1) | Restricted cash represents amounts pledged as collateral to support outstanding letters of credit under the Company’s revolving credit facility and is not available for general corporate purposes while pledged. |
See accompanying notes to consolidated financial statements.
F-13
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
1. Organization and business
CoVolt Holdings Group, LLC (the “Company”) (formerly known as SEC Holdings Group, LLC) is a wholly owned subsidiary of SEC Intermediate, LLC (“the Parent”), which is a wholly owned subsidiary of SEC Parent II, LLC (“the Ultimate Parent”).
The Company, headquartered in Houston, Texas, is a general contractor that engages in and performs engineering, procurement, and construction contracts for solar projects throughout the United States. The work is primarily performed under fixed-priced contracts.
2. Summary of significant accounting policies
Basis of accounting and presentation
The accompanying consolidated financial statements include the accounts of the Company and its controlled subsidiaries which reflect all adjustments necessary to state fairly the Company’s consolidated financial position, results of operations, and cash flows in accordance with principles generally accepted in the United States of America (“U.S. GAAP”).
The Company classifies certain assets and liabilities as current utilizing the duration of the related contract or program as the Company’s operating cycle, which is generally longer than one year. This primarily impacts Contract Assets and Contract Liabilities. The Company classifies all other assets and liabilities based on whether the asset will be realized or the liability will be paid within one year.
Principles of consolidation
The consolidated financial statements include the accounts of the Company and its subsidiaries. All material intercompany balances and transactions have been eliminated during consolidation. Any minority ownership is reported as a non-controlling interest. Non-controlling interests primarily relate to the Company’s partial ownership interest in a subsidiary. For the years presented, the activity attributable to non-controlling interests was not material.
Use of estimates
The preparation of consolidated financial statements in conformity with accounting principles generally accepted in the United States requires management to make estimates and assumptions that affect the amounts reported in the accompanying consolidated financial statements and these notes.
Actual results could differ materially from those estimates and may result in material effects on the Company’s operating results and financial position. Estimates made in preparing the accompanying consolidated financial statements primarily include, but are not limited to, those related to revenue recognition, goodwill and long-lived asset valuations, impairment assessments, and unit-based compensation. Management believes that these estimates and assumptions provide a reasonable basis for the fair presentation of the consolidated financial statements.
Cash and cash equivalents
The Company considers cash and cash equivalents to include cash on hand, cash held in demand deposit accounts, and all highly liquid financial instruments purchased with an original maturity of three months or
F-14
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
less. The Company places its cash and cash equivalents with high credit quality financial institutions. At times, such amounts may be in excess of the Federal Deposit Insurance Corporation limits.
Restricted cash
Restricted cash represents amounts pledged as collateral to support outstanding letters of credit under the Company’s revolving credit facility and is not available for general corporate purposes while pledged. Restricted cash is classified as current on the consolidated balance sheets as the related letters of credit are expected to expire within the next 12 months of the consolidated balance sheet date.
Accounts receivable
The Company accounts for trade receivables based on the amounts billed to customers. The Company generally does not accrue interest on any of its trade receivables. As of January 1, 2025 and 2024, the balance of gross trade receivables was $69.5 million, and $31.3 million, respectively. Specific projects are reserved against once there is indication that the customer will not be able to pay as well as for general billing disputes with customers. Account balances are written off against the allowance when management determines it is probable that the receivable will not be recovered.
As the financial conditions of these parties change, circumstances develop or additional information becomes available, write-offs may occur and adjustments to the allowance for expected credit losses may be required. Management has assessed the allowance for credit losses and determined the amount and related activity to be immaterial as of December 31, 2025 and 2024.
Other current assets
From time to time, the Company provides surety bonds, letters of credit, bank guarantees, or other financial assurances on the Company’s projects. Sureties issue or renew bonds on a project-by-project basis and can require the posting of additional collateral as a condition to issuing or renewing bonds. Additionally, the Company makes downpayments to various vendors and subcontractors related to the purchase of materials for the Company’s projects. As of December 31, 2025, the Company had $10.3 million of project downpayments, $3.3 million security deposit receivable, and $5.7 million of other prepaid expenses. As of December 31, 2024, the Company had $21.1 million of project downpayments, $17.9 million of cash security receivables, and
$4.7 million of other prepaid expenses.
Property and equipment, net
Property and equipment acquired in business combinations are initially recorded at fair value. Property and equipment acquired outside of business combinations are recorded at cost. The cost of property and equipment is depreciated using the straight-line method over the estimated useful lives. Expenditures for maintenance and repairs are charged to expense as incurred, while the cost of additions and betterments are capitalized. At the time assets are sold or disposed of, the cost and accumulated depreciation are removed from their respective accounts and the related gains or losses are reflected in the consolidated statements of operations.
F-15
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
Depreciation is recognized over the assets estimated useful lives using the straight-line method. The range of estimated useful lives for the respective assets is as follows:
| Furniture and fixtures |
5-7 years | |||
| Buildings |
39 years | |||
| Computer equipment |
3-5 years | |||
| Software |
3-5 years | |||
| Leasehold improvements |
* | |||
| Construction equipment |
3-7 years | |||
| * | Lesser of estimated useful life or lease term |
Leases
A lease contract conveys the right to use an underlying asset for a period of time in exchange for consideration. At inception, the Company determines whether a contract contains a lease by determining if there is an identified asset and if the contract conveys the right to control the use of the identified asset in exchange for consideration over a period of time. Control over the use of the identified asset means the lessee has both (a) the right to obtain substantially all of the economic benefits from the use of the asset and (b) the right to direct the use of the asset.
The Company elected to apply the “Package of Three relief” practical expedients as outlined in Accounting Standards Codification (“ASC”) 842, Leases, which permits the Company not to reassess whether existing or expired contracts are or contain leases, the classification of leases or whether any initial direct costs previously capitalized continue to qualify for capitalization. In addition, the Company elected not to apply the recognition requirements to short-term leases (those with terms of 12 months or less), and not to separate non-lease components from associated lease components for all classes of underlying assets.
Finance and operating lease ROU assets and liabilities are recognized based on the present value of future lease payments over the expected lease term at commencement date. If the implicit rate is not readily determinable in the Company’s leases, management will use the Company’s incremental borrowing rate based on the information available at commencement date in determining the present value of future payments. The incremental borrowing rate represents the rate of interest that would be paid to borrow on a collateralized basis over a similar term. The Company determines its incremental borrowing rate using a portfolio approach based on information available as of the lease commencement date, including applicable lease terms and the current economic environment. The expected lease term includes options to extend or terminate the lease when it is reasonably certain the Company will exercise such option.
On the lease commencement date, the amount of the ROU asset consists of (i) the amount of the initial measurement of the lease liability; (ii) any lease payments made at or before the commencement date, minus any lease incentives received; and (iii) any initial direct costs incurred. The present value calculation may account for an option to extend or terminate the lease when it is reasonably certain that the Company will exercise the option.
Variable lease payments not included in the measurement of the lease liability are expensed as incurred. For leases with renewal options where the renewal is reasonably certain, the lease term, including the renewal period, is used to determine the appropriate lease classification and to compute periodic rental expense. Leases
F-16
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
with initial terms shorter than 12 months are not recognized on the consolidated balance sheets, and lease expense is recognized on a straight-line basis.
Finance lease assets and liabilities are recorded on the consolidated balance sheets. Finance lease expense is composed of amortization on the leased asset and interest on the lease liability. Additions to finance leases are included within the supplemental disclosures of non-cash information in the consolidated statements of cash flows. Many of the Company’s finance leases contain a purchase option which the Company is reasonably certain to exercise at the end of the lease term, given that the purchase option prices are typically below the estimated fair market values of the related assets.
Operating lease ROU assets and liabilities are recorded on the consolidated balance sheets, with the related lease expense recognized over the term of the lease on a straight-line basis. Operating lease expense is recorded as rent expense within general and administrative expense. Fixed costs for operating leases are composed of initial base rent amounts plus any fixed annual increases. Variable costs for operating leases consist primarily of common area maintenance expenses and taxes for facility leases.
Impairment of long-lived assets
Long-lived assets that are held and used including definite lived intangibles, are assessed for impairment whenever events or changes in circumstances indicate their carrying values may not be recoverable. Such reviews are performed in accordance with ASC 360, Property, Plant and Equipment.
Recoverability of assets is measured by a comparison of the carrying amount of an asset to future undiscounted operating cash flows expected to be generated by the asset. If such assets are considered to be impaired, the impairment to be recognized is measured by the amount by which the carrying amount of the assets exceeds the fair value of the assets. Fair values are determined by a variety of valuation methods, including appraisals, sales prices of similar assets and present value techniques. Impairment losses for assets, or asset groups, to be disposed of by sale are recognized at the lower of the carrying amount of the asset, or asset group, or fair value less cost to sell. There were no impairments of the Company’s long-lived assets in any of the periods presented.
Goodwill
Goodwill represents the excess of the purchase price over the fair value of the net tangible and intangible assets of businesses acquired in a business combination. Goodwill is evaluated for impairment annually on December 31, or when events or circumstances occur indicating goodwill might be impaired. Guidance related to goodwill impairment testing provides an option to first assess qualitative factors to determine whether it is more likely than not that the fair value of a reporting unit is less than its carrying amount. The Company considers various events and circumstances when evaluating whether it is more likely than not that the fair value of a reporting unit is less than its carrying amount. If the Company cannot support the conclusion that it is not more likely than not that the fair value of a reporting unit is less than its carrying amount, the Company would perform a quantitative impairment test for the reporting unit.
The quantitative assessment estimates the fair value of the reporting unit using income and market approaches and compares that amount to the carrying value of that reporting unit. If the carrying amount of a reporting unit exceeds its fair value, an impairment charge for the difference is recorded in the consolidated statements of operations.
F-17
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
The Company determines reporting units based on component parts of its business for which discrete financial information is available and reviewed regularly by management. The Company has determined that its operations constitute a single reporting unit. Goodwill impairment is the amount by which the Company’s single reporting unit carrying value exceeds its fair value, not to exceed the recorded amount of goodwill.
As of December 31, 2025 and 2024, there was no indication that it was more likely than not that the fair value of our reporting unit was less than its carrying amount.
Other intangible assets
Other intangible assets with definite lives, which are stated at cost or fair value if acquired in a business combination, are amortized on a straight-line basis over their estimated useful lives. The Company reviews its intangible assets for impairment and conducts impairment review when events or circumstances indicate that the carrying value of a long-lived asset may be impaired by estimating the future undiscounted cash flows to be derived from an asset to assess whether or not potential impairment exists. No impairment charge was recorded for the years ended December 31, 2025 and 2024.
Warranty
The Company provides standard assurance type warranties for projects for periods of up to two years. A provision is recorded for estimated warranty and remediation expenses in cost of revenue. The Company does not maintain general or unspecified reserves; all warranty reserves are related to specific projects and are reflected as a component of Accrued expenses and other on the consolidated balance sheets. All actual or estimated material or labor costs incurred for warranty or remediation services in subsequent periods are charged against those established reserves. While the Company periodically monitors its warranty activities and claims, if actual costs incurred were to be different from estimates, adjustments to the warranty reserves would be recognized in the period in which those differences arose or were identified.
A reconciliation of accrued warranty and related expenses is as follows (in thousands):
| December 31, | 2025 | 2024 | ||||||
| Balance, beginning of year |
$ | 6,121 | $ | 11,629 | ||||
| Accruals for warranties |
8,688 | 6,346 | ||||||
| Usage during the year |
(6,646 | ) | (11,854 | ) | ||||
| Balance, end of year |
$ | 8,163 | $ | 6,121 | ||||
Income taxes
The Company is a limited liability company treated as a pass-through entity for U.S. federal income tax purposes. As a result, members report the Company’s federal taxable income on their individual income tax returns. However, the Company is subject to income taxes in certain states in which business is conducted, and these amounts are not considered significant to the consolidated financial statements for the years ended December 31, 2025 and 2024.
Income taxes are reported in accordance with ASC 740, Income Taxes. This guidance requires the establishment of deferred tax accounts for all temporary differences between the book and tax basis of assets and liabilities. In addition, deferred tax accounts must be adjusted to reflect new rates if enacted into law. There are no
F-18
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
significant temporary differences between financial statement and income tax reporting as of December 31, 2025 and 2024. Accordingly, no deferred state income taxes are included in the accompanying consolidated financial statements.
The Company recognizes a benefit only if it is more likely than not that the tax position would be sustained in a tax examination, with a tax examination being presumed to occur. The amount recognized is the largest amount of tax benefit that is greater than 50% likely of being realized on examination. For tax positions not meeting the more-likely-than-not test, no tax benefit is recorded. As of December 31, 2025 and 2024, the Company did not have any unrecognized tax benefits recorded and does not expect any significant change in the next 12 months.
The Company recognizes interest and penalties related to income tax matters in interest and income tax expense, respectively. The Company had no material amounts accrued for interest or penalties as of December 31, 2025 and 2024.
Foreign currency translation
The functional currency of Signal Energy Australia is the Australian dollar. The financial statements of this subsidiary are translated into U.S. dollars using the exchange rate at the consolidated balance sheet date for assets and liabilities, the historical exchange rate for equity, and a weighted average exchange rate for revenues and expenses. Translation adjustments are recorded to Other comprehensive income (loss) in the consolidated statements of comprehensive income (loss).
Accrued expenses and other
As of December 31, 2025, the Company had $9.8 million of accrued compensation, $8.2 million of accrued warranty expenses, $2.5 million of accrued employee benefits, and $4.4 million of other accrued expenses. As of December 31, 2024, the Company had $2.7 million of accrued compensation, $2.7 million of accrued employee benefits, $6.1 million of accrued warranty expenses, and $3.6 million of other accrued expenses.
Debt issuance costs
Debt issuance costs include external costs incurred to obtain financing. Debt issuance costs related to the revolving credit facility are amortized over the respective term of the financing using the straight-line method.
Debt issuance costs are presented on the consolidated balance sheets along with unamortized debt discounts as a reduction to current and long-term debt.
Revenue recognition
The Company’s revenue is primarily derived from long-term contracts with customers and accounting treatment of these contracts is in accordance with ASC 606, Revenue from Contracts with Customers, as follows:
Recognition of performance obligations
A performance obligation is a promise in a contract to transfer a distinct good or service to the customer and is the unit of account in the revenue standard. The contract transaction price is allocated to each distinct performance obligation and recognized as revenue when, or as, the performance obligation is satisfied. The Company’s projects typically span between 12 to 18 months. Substantially all of the Company’s contracts have a single performance obligation as the promise to transfer the individual goods or services is not separately identifiable from other promises in the contracts and, therefore, not distinct.
F-19
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
Substantially all of the Company’s revenue is recognized over time, as performance obligations are satisfied, due to the continuous transfer of control to the customer and the Company’s continuous right to payment throughout the contracts’ duration.
Contracts where the Company provides a significant service of integrating a set of tasks and components into a single project or capability, are accounted for as a single performance obligation.
The Company recognizes revenue using the percentage-of-completion method (an input method), based on costs incurred to date compared to total estimated costs. Costs related to uninstalled materials are included in this calculation when incurred, provided that those materials have been transferred to the customer’s control, could be considered distinct performance obligations, are expected to be installed a significant amount of time after delivery, are a significant portion of the total performance obligation, and the materials are produced by a third party. This method is the most accurate measure of the Company’s contract performance because it directly measures the value of the goods and services transferred to the customer. Contract costs include all direct material, labor, subcontractor, and other costs and those indirect costs determined to relate to contract performance, such as indirect salaries and wages, equipment repairs and depreciation, insurance, legal, and payroll taxes. Provisions for estimated losses on uncompleted contracts are made in the period in which such losses are determined.
Items excluded from cost-to-cost
Pre-contract costs are generally not material and are charged to expense as incurred, but in certain cases, pre-contract cost recognition may be deferred if specific probability criteria are met.
Remaining performance obligations
Remaining performance obligations reflect the portion of the transaction price associated with customer orders for which work has not yet been completed. As of December 31, 2025 and 2024, the total transaction price allocated to these outstanding obligations was $590 million and $731 million, respectively, relating to the Company’s engineering, procurement, and construction (“EPC”) service contracts. The Company expects to recognize revenue on substantially all of these remaining obligations within the next 12 to 18 months. See Note 4—Revenue from Contracts with Customers for further discussion.
Variable consideration
Contract modifications through change orders, claims, and incentives are routine in the performance of the Company’s contracts to account for changes in the contract specifications or requirements. In most instances, contract modifications are not distinct from the existing contract due to the significant integration of services provided in the contract and are accounted for as a modification of the existing contract and performance obligation. Either the Company or its customers may initiate change orders, which may include changes in specifications or designs, manner of performance, facilities, equipment, materials, sites, and period of completion of the work. Change orders that are unapproved as to both price and scope are evaluated as claims. The Company considers claims to be amounts in excess of approved contract prices that the Company seeks to collect from its customers or others for customer-caused delays, errors in specifications and designs, contract terminations, change orders that are either in dispute or are unapproved as to both scope and price, or other causes of unanticipated additional contract costs.
The Company estimates variable consideration for a performance obligation at the most likely amount to which the Company expects to be entitled (or the most likely amount the Company expects to incur in the case of
F-20
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
liquidated damages), utilizing estimation methods that best predict the amount of consideration to which the Company will be entitled (or will incur in the case of liquidated damages). The Company includes variable consideration in the estimated transaction price to the extent it is probable that a significant reversal of cumulative revenue recognized will not occur or when the uncertainty associated with the variable consideration is resolved. The Company’s estimates of variable consideration and determination of whether to include estimated amounts in transaction price are based largely on an assessment of its anticipated performance and all information (historical, current, and forecasted) that is reasonably available to the Company.
The effect of variable consideration on the transaction price of a performance obligation is recognized as an adjustment to revenue on a cumulative catch-up basis. To the extent unapproved change orders and claims reflected in the transaction price (or excluded from the transaction price in the case of liquidated damages) are not resolved in the Company’s favor, or to the extent incentives reflected in the transaction price are not earned, there could be reductions in, or reversals of, previously recognized revenue.
Contract estimates
Accounting for long-term contracts and programs involves the use of various techniques to estimate total contract revenue and costs. For long-term contracts, the Company estimates the profit on a contract as the difference between the total estimated revenue and expected costs to complete a contract and recognizes such profit over the life of the contract. Contract estimates are based on various assumptions to project the outcome of future events that often span 12 to 18 months. These assumptions include labor productivity and availability, the complexity of the work to be performed, the cost and availability of materials and the performance of subcontractors. Changes in job performance, job conditions, and estimated profitability, including those changes arising from contract penalty provisions and final contract settlements may result in revisions to costs and income and are recognized in the period in which the revisions are determined.
Contract assets and contract liabilities
Contract assets include unbilled amounts from long-term construction projects when revenue recognized under the cost-to-cost measure of progress exceeds the amounts invoiced to customers. Contract retainages associated with contract work that has been completed and billed but not paid by its customers until the contracts are substantially complete, pursuant to contract retainage provisions under the contract, are also included in Contract assets. Uninstalled materials are materials acquired by a contractor that will be used to satisfy its performance obligations in a contract for which the cost incurred does not depict transfer to the customer. Deferred project costs are Contract assets that primarily represent costs to fulfill a contract that (1) directly relate to an existing or anticipated contract, (2) generate or enhance resources that will be used in satisfying performance obligations in the future, and (3) are expected to be recovered through the contract and are included in Contract assets. Capitalized contract costs are generally expensed to the associated contract over the period of anticipated use on the project. As of the years ended December 31, 2025 and 2024 the company recorded $0.0 and $11.0 million of uninstalled materials, respectively.
Contract liabilities from long-term construction contracts arise when amounts invoiced to customers exceed revenue recognized under the cost-to-cost measure of progress. Most projects contain milestone billing schedules that allow for billings at the commencement of projects, which can lead to material amounts billed in excess of revenue recognized. If estimates of the amount of consideration that the Company expects to receive in exchange for transferring promised goods or services to the customer and contract costs indicate a loss, a
F-21
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
provision for the entire loss on the performance obligation or the contract is made and is recorded on the consolidated balance sheets as Accrued losses on uncompleted contracts. Provisions for estimated losses on uncompleted contracts are made in the period in which such losses are determined. There were no accrued losses on uncompleted contracts for the years ended December 31, 2025 and 2024, respectively.
Equity distributions
Periodically, the Company makes cash distributions to the Parent. These distributions are recorded as reductions to members’ equity in the consolidated financial statements.
Unit-based compensation
The Company recognizes unit-based compensation expense based on the equity award’s grant date fair value. The determination of the fair value of equity awards issued to employees of the Company is based upon the underlying unit price and a number of assumptions, including volatility, performance period, risk-free interest rate and expected dividends. The Company accounts for forfeitures as they occur. The grant date fair value of each unit is amortized on a straight-line basis over the requisite service period, except for portions of the award which are contingent upon a future event occurring. The contingent portion of the award is recognized when the event becomes probable, which in the case of the Company would be upon a change of control or sale of the Company.
Risks and uncertainties
Tariffs and the possibility of additional tariffs in the future have created uncertainty in the industry. If the price of solar systems in the U.S. increases, the use of solar systems could become less economically feasible and could reduce the Company’s gross margins or reduce the demand of the Company’s services. Additionally, existing or future tariffs may negatively affect key customers and suppliers. Such outcomes could adversely affect the amount or timing of the Company’s revenue, results of operations, or cash flows, and continuing uncertainty could cause sales volatility, price fluctuations, or supply shortages or cause the Company’s customers to advance or delay their purchase of the Company’s products. It is difficult to predict what further trade-related actions governments may take, which may include additional or increased tariffs and trade restrictions, and the Company may be unable to quickly and effectively react to such actions.
Credit concentration
Financial instruments that potentially subject the Company to significant concentrations of credit risk consist primarily of cash and cash equivalents and accounts receivable as discussed within Note 12—Major Customer Concentration. The Company has no significant off balance-sheet concentrations of credit risk. The Company maintains its cash and cash equivalents in the form of interest-bearing deposits with financial institutions that are believed to be of high credit quality and has not experienced any material losses relating to any cash and cash equivalents. As of December 31, 2025, $151 million of the Company’s bank balances were uninsured and uncollateralized and exposed to potential custodial credit risk.
Fair value of financial instruments
The Company’s financial instruments consist primarily of cash and cash equivalents, trade receivables, contract assets and contract liabilities, accounts payable, accrued liabilities, and debt instruments. The carrying amounts of cash and cash equivalents, accounts receivable, contract assets and contract liabilities, accounts
F-22
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
payable, accrued liabilities, and money markets approximate their fair value due to the short maturity of such instruments. Accounting principles generally accepted in the United States of America define fair value as the exchange price that would be received for an asset or paid to transfer a liability (exit price) in the principal or most advantageous market for the asset or liability in an orderly transaction between market participants on the measurement date. Fair value is the price that would be received to sell an asset or the amount paid to transfer a liability, also referred to as the “exit price,” in the principal or most advantageous market for the asset or liability in an orderly transaction between market participants on the measurement date. Fair value measurements are determined by maximizing the use of observable inputs and minimizing the use of unobservable inputs. The hierarchy places the highest priority on unadjusted quoted market prices in active markets for identical assets or liabilities (Level 1 measurements) and gives the lowest priority to unobservable inputs (Level 3 measurements).
The three levels of inputs within the fair value hierarchy are defined as follows:
Level 1—This level consists of quoted prices (unadjusted) for identical assets or liabilities in active markets that the Company has the ability to access as of the measurement date.
Level 2—This level consists of significant other observable inputs other than Level 1 prices such as quoted prices for similar assets or liabilities; quoted prices in markets that are not active; or other inputs that are observable or can be corroborated by observable market data.
Level 3—This level consists of significant unobservable inputs that reflect the Company’s own assumptions about the assumptions that market participants would use in pricing an asset or liability.
In some cases, a valuation technique used to measure fair value may include inputs from multiple levels of the fair value hierarchy. The lowest level of significant input determines the placement of the entire fair value measurement in the hierarchy.
Non-recurring fair value measurements
The Company generally applies fair value valuation techniques on a non-recurring basis associated with (1) valuing assets and liabilities acquired in connection with business combinations and other transactions; (2) valuing potential impairment loss related to long-lived assets; and (3) valuing potential impairment loss related to goodwill and the definite-lived intangible assets.
Cost of revenue
Cost of revenue consists primarily of construction related labor, materials, subcontractor costs, and equipment rentals, which are expensed as incurred.
General and administrative expenses
General and administrative expenses consist of corporate operating expenses including office rent expense, information technology, accounting, legal, and human resources, which are expensed as incurred.
F-23
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
3. New accounting pronouncements
Recently adopted accounting pronouncements
In November 2023, the Financial Accounting Standards Board (“FASB”) issued Accounting Standards Update (“ASU”) 2023-07, Segment Reporting (Topic 280): Improvements to Reportable Segment Disclosures (“ASU 2023-07”). The update improves reportable segment disclosure requirements, primarily through enhanced disclosures about significant segment expenses that are regularly provided to the chief operating decision maker (“CODM”) and included within each reported measure of segment profit or loss. This ASU also requires disclosure of the title and position of the CODM and an explanation of how the CODM uses the reported measures of segment profit or loss in assessing segment performance and deciding how to allocate resources. Under ASU 2023-07, the disclosures that are currently required on an annual basis under Topic 280, Segment Reporting, pertaining to reportable segment profit or loss and assets will also be required for interim periods. This update is effective for fiscal years beginning after December 15, 2023, and interim periods within fiscal years beginning after December 15, 2024. Retrospective application is required. The Company adopted this update effective December 31, 2025. The Company has expanded its current segment information in accordance with this standard, refer to Note 6—Segment Information.
In December 2023, the FASB issued ASU 2023-09, Income Taxes (Topic 740): Improvements to Income Tax Disclosures (“ASU 2023-09”), which requires public entities, on an annual basis, to provide disclosure of specific categories in the reconciliation of the effective tax rate, as well as disclosure of income taxes paid, disaggregated by jurisdiction. ASU 2023-09 is effective for fiscal years beginning after December 15, 2024, with early adoption permitted. The Company adopted this ASU prospectively as of and for the year ended December 31, 2025, and its adoption only impacted the Company’s disclosures, and did not have a material effect on its consolidated financial statements or results of operations. The Company assessed the adoption of this ASU and determined it to be quantitatively and qualitatively immaterial.
In July 2025, the FASB issued ASU 2025-05, Financial Instruments—Credit Losses (Topic 326): Measurement of Credit Losses for Accounts Receivable and Contract Assets (“ASU 2025-05”). ASU 2025-05 provides a practical expedient that permits an entity to assume that conditions at the consolidated balance sheet date remain unchanged over the life of the asset when estimating expected credit losses for current accounts receivable and current contract assets. ASU 2025-05 is effective for fiscal years beginning after December 15, 2025, including interim periods within those fiscal years, with early adoption permitted. The amendments in ASU 2025-05 should be applied prospectively. The Company adopted this update effective December 31, 2025. The adoption of this ASU did not have a material impact on the financial statements or results of operations.
New accounting pronouncements not yet adopted
In November 2024, the FASB issued ASU 2024-03, Income Statement—Reporting Comprehensive Income—Expense Disaggregation Disclosures (Subtopic 220-40): Disaggregation of Income Statement Expenses (“ASU 2024-03”). ASU 2024-03 requires entities to tabularly disclose in the footnotes to the financial statements, the amounts of purchased inventory, employee compensation, depreciation, and intangible asset amortization included in each relevant expense caption. ASU 2024-03 also requires disclosure of the amount, and a qualitative description of, other items remaining in relevant expense captions that are not separately disaggregated. ASU 2024-03 is effective for fiscal years beginning after December 15, 2026, and interim periods within fiscal years beginning after December 15, 2027. Early adoption and both prospective and retrospective application are permitted. The Company is currently assessing the effect of this update.
F-24
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
In September 2025, the FASB issued ASU 2025-06, Intangibles—Goodwill and Other—Internal-Use Software (Subtopic 350-40): Targeted Improvements to the Accounting for Internal-Use Software (“ASU 2025-06”). ASU 2025-06 modernizes the accounting for internal-use software by eliminating the previous stage-based capitalization model so that the guidance is neutral to different software development methods. ASU 2025-06 is effective for fiscal years beginning after December 15, 2027, including interim periods within those fiscal years, with early adoption permitted. The amendments in ASU 2025-06 should be applied prospectively, with retrospective application or a modified transition approach permitted. The Company is currently assessing the effect of this update.
4. Revenue from contracts with customers
During the years ended December 31, 2025, and 2024, the Company recognized revenue of $119.8 million, and $44.5 million related to contract liabilities outstanding as of the end of each respective prior year.
Contract assets and liabilities consist of the following (in thousands):
| December 31, | 2025 | 2024 | 2023 | |||||||||
| Unbilled and retainages receivables |
$ | 12,485 | $ | 19,941 | $ | 27,907 | ||||||
| Total Contract assets |
$ | 12,485 | $ | 19,941 | $ | 27,907 | ||||||
| Billings in excess of costs and estimated earnings |
$ | 93,039 | $ | 123,263 | $ | 58,749 | ||||||
| Total Contract liabilities |
$ | 93,039 | $ | 123,263 | $ | 58,749 | ||||||
Contract assets and liabilities fluctuate period to period based primarily on changes in the number and size of projects in progress at period end, variability in billing and payment terms, and change orders or contract modifications.
The Company operates as a single operating and reportable segment with one primary revenue stream from EPC contracts.
5. Property and equipment, net
Property and equipment and estimated useful lives consist of the following (dollars in thousands):
| Estimated Useful Lives (Years) |
2025 | 2024 | ||||||||||
| Furniture and fixtures |
5-7 | $ | 180 | $ | 180 | |||||||
| Buildings |
39 | 1,572 | 1,572 | |||||||||
| Computer equipment |
3-5 | 194 | 41 | |||||||||
| Software |
3-5 | 461 | 450 | |||||||||
| Leasehold improvements |
* | 706 | 706 | |||||||||
| Construction equipment |
3-7 | 4,297 | 1,453 | |||||||||
| Total |
7,410 | 4,402 | ||||||||||
| Less: accumulated depreciation and amortization |
(4,014 | ) | (2,385 | ) | ||||||||
| Total, net |
$ | 3,396 | $ | 2,017 | ||||||||
| * | Lesser of estimated useful life or lease term. |
F-25
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
Depreciation expense on property and equipment was $0.8 million and $0.5 million for the years ended December 31, 2025 and 2024, respectively.
6. Segment information
The Company operates in one reportable segment which derives revenue through providing EPC services throughout the United States. The Company concludes that it operates as a single operating segment encompassing all EPC services, photovoltaic solar, high-voltage substations, switchyards, collector systems, and transmission lines. The consolidated operating results are regularly reviewed by the Chief Operating Decision Maker (“CODM”) to allocate resources or assess performance. As such, the Company reflects its financial results as one reportable segment, which reflects the consolidated performance of its business activities. The accounting policies of the reportable segment are the same as those described in the summary of significant accounting policies.
The Company has identified the President and Chief Executive Officer as the CODM.
The key measure of segment profit or loss utilized by the CODM to assess performance of and allocate resources to the Company’s operating segment is consolidated net income (loss), primarily by monitoring actual results compared to prior periods and expected results. The significant expense categories reviewed by the CODM are consistent with what appears on the face of the consolidated statements of operations. The Company’s CODM uses the consolidated balance sheet and consolidated statement of operations to assess performance and decide how to allocate resources.
7. Leases
The Company has operating leases that are predominately for office space and finance leases primarily related to equipment, and vehicles. The Company’s lease agreements do not contain any material residual value guarantees or material restrictive covenants.
The following table presents certain quantitative information related to the Company’s lease arrangements (in thousands):
| December 31, | 2025 | 2024 | ||||||||
| Lease Type |
Classification | |||||||||
| Assets |
||||||||||
| Operating lease |
Operating lease right-of-use assets | $ | 2,049 | $ | 568 | |||||
| Finance lease |
Finance lease right-of-use assets, net | 5,263 | 6,404 | |||||||
| Total assets |
$ | 7,312 | $ | 6,972 | ||||||
| Liabilities |
||||||||||
| Current: |
||||||||||
| Operating lease |
Operating lease liabilities, current portion | $ | 50 | $ | 545 | |||||
| Finance lease |
Finance lease liabilities, current portion | 1,706 | 1,951 | |||||||
| Total current |
1,756 | 2,496 | ||||||||
F-26
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
| December 31, | 2025 | 2024 | ||||||||||
| Non-current: |
||||||||||||
| Operating lease |
Operating Lease Liabilities, net of current portion | 2,083 | 50 | |||||||||
| Finance lease |
Finance lease liabilities, net of current portion | 1,430 | 1,486 | |||||||||
| Total non-current |
3,513 | 1,536 | ||||||||||
| Total liabilities |
$ | 5,269 | $ | 4,032 | ||||||||
The weighted average remaining lease term and weighted average discount rate for the Company’s operating and finance leases are as follows:
| December 31, | 2025 | 2024 | ||||||
| Weighted average remaining lease term: |
||||||||
| Operating leases |
10.3 years | 1.2 years | ||||||
| Finance leases |
1.8 years | 2.0 years | ||||||
| Weighted average discount rate: |
||||||||
| Operating leases |
18.3% | 18.3% | ||||||
| Finance leases |
14.6% | 12.9% | ||||||
As of December 31, 2025, maturities of lease liabilities are summarized as follows (in thousands):
| Year ending December 31, | Operating Leases |
Finance Leases |
||||||
| 2026 |
$ | 235 | $ | 2,013 | ||||
| 2027 |
396 | 1,418 | ||||||
| 2028 |
473 | 89 | ||||||
| 2029 |
526 | — | ||||||
| 2030 |
536 | — | ||||||
| Thereafter |
3,132 | — | ||||||
| Total future lease payments |
5,298 | 3,520 | ||||||
| Less: amount representing Interest |
(3,165 | ) | (384 | ) | ||||
| Total lease liabilities |
$ | 2,133 | $ | 3,136 | ||||
The components of lease expense are as follows (in thousands):
| Year ended December 31, | 2025 | 2024 | ||||||
| Operating lease costs: |
||||||||
| Operating lease costs |
$ | 638 | $ | 565 | ||||
| Finance lease costs: |
||||||||
| Interest on lease liabilities |
652 | 410 | ||||||
| Amortization of right-of-use assets |
2,060 | 1,575 | ||||||
| Total lease cost |
$ | 3,350 | $ | 2,550 | ||||
F-27
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
8. Goodwill and other intangible assets
In connection with the 2025 and 2024 annual goodwill assessment, management performed a qualitative impairment assessment of its reporting unit, which indicated that it was not more likely than not that the fair value of the reporting unit was less than its carrying amount including goodwill. Accordingly, a quantitative goodwill impairment test was not required, and no goodwill impairment was recognized in 2024 or 2025. There was no accumulated impairment of goodwill as of December 31, 2025 or 2024.
Other intangible assets
Other intangible assets consisted of the following (dollars in thousands):
| Estimated useful lives (Years) |
December 31, | |||||||||||
| Amortizable intangibles | 2025 | 2024 | ||||||||||
| Customer relationship |
5 | $ | 39,300 | $ | 39,300 | |||||||
| Trade name |
10 | 7,300 | 7,300 | |||||||||
| Non-compete agreements |
5 | 160 | 160 | |||||||||
| Total amortizable intangibles |
46,760 | 46,760 | ||||||||||
| Accumulated amortization: |
||||||||||||
| Customer relationship |
39,300 | 32,313 | ||||||||||
| Trade name |
3,717 | 3,001 | ||||||||||
| Non-compete agreements |
160 | 132 | ||||||||||
| Total accumulated amortization |
43,177 | 35,446 | ||||||||||
| Total other intangible assets, net |
$ | 3,583 | $ | 11,314 | ||||||||
Future amortization is as follows (in thousands):
| Year ending December 31, | ||||
| 2026 |
$ | 730 | ||
| 2027 |
730 | |||
| 2028 |
730 | |||
| 2029 |
730 | |||
| 2030 |
663 | |||
| Total |
$ | 3,583 | ||
Amortization expense on other intangible assets was $7.7 million and $8.6 million for the years ended December 31, 2025 and 2024. There was no impairment of other intangible assets recorded as of the years ended December 31, 2025 or 2024.
9. Unit-based compensation
The Company accounts for equity grants to employees as unit-based compensation under ASC 718, Compensation-Stock Compensation. These awards are issued by the Company’s ultimate parent and represent
F-28
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
equity interests in the ultimate parent. Unit-based compensation cost is measured at the grant date fair value and is recognized on a straight-line basis over the requisite service period, including those units with graded vesting, with a corresponding credit to additional paid-in capital as a capital contribution from Ultimate Parent. However, the amount of unit-based compensation at any date is equal to the portion of the grant date value of the award that is vested.
Equity grants issued to employees are measured at fair value on the grant date using an option pricing model. The Company utilizes the estimated weighted average of the Company’s expected life dependent on various exit scenarios to estimate the expected term of the awards. Expected volatility is based on the average of historical and implied volatility of a set of comparable companies, adjusted for size and leverage. The risk-free rates are based on the yields of U.S. Treasury instruments with comparable terms. Actual results may vary depending on the assumptions applied within the model.
The following table summarizes the activity of the Company’s equity grant units for the years ended December 31, 2025 and 2024:
| December 31, | 2025 | 2024 | ||||||
| Units | Units | |||||||
| Outstanding, beginning of year |
9,417 | 6,395 | ||||||
| Granted |
1,995 | 4,365 | ||||||
| Forfeited |
(359 | ) | (1,343 | ) | ||||
| Repurchased |
(2,418 | ) | — | |||||
| Cancelled |
— | — | ||||||
| Outstanding, end of year |
8,635 | 9,417 | ||||||
| Authorized, end of year |
11,160 | 11,160 | ||||||
New Class B units
In 2024, New Class B units were issued to members of the Board and key employees. These units contain vesting provisions ranging from 25% to 62.5% upon issuance, 12.5% to 50% over one to three years, and 25% upon a change of control. Vested units do not forfeit upon termination and represent a residual interest in Ultimate Parent.
In 2025, New Class B units were issued to key employees. These units contain vesting provisions ranging from 25% to 67% upon issuance, 33% to 50% over one to three years, and 0%-25% upon a change of control. Vested units do not forfeit upon termination and represent a residual interest in Ultimate Parent.
During the year ended December 31, 2025, the Company repurchased vested equity awards from certain former employees for cash consideration. The repurchased awards remain authorized but are no longer outstanding. The repurchase prices were determined pursuant to the applicable award agreements and, in certain cases, differed from the grant-date fair value used for unit-based compensation expense. The repurchases were accounted for as equity transactions.
F-29
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
The following table summarizes the significant weighted-average assumptions used in the option-pricing models to determine fair value of the units at the time of issuance:
| New Class B 2025 |
New Class B 2024 | |||
| Volatility |
54.5% | 57.9% | ||
| Expected dividend yield |
— | — | ||
| Risk-free rate |
3.87% | 4.01% | ||
| Expected term |
3 years | 3 years | ||
For the New Class B Units, the Company measured the estimated grant date fair value of $3.55 and $0.77 per unit for the year ended December 31, 2025 and 2024, respectively, using an option pricing method. The unit-based compensation expense is recorded in General and administrative expenses on the consolidated statements of operations.
For the year ended December 31, 2025, the Company recognized $0.6 million of unit-based compensation related to the New Class B units. As of December 31, 2025, the Company had $5.5 million of unrecognized compensation expense, of which $3.1 million is expected to be recognized over a weighted average period of 2.0 years, with the remaining $2.4 million being recognized upon a change in control.
For the year ended December 31, 2024, the Company recognized $2.8 million of unit-based compensation related to the New Class B units.
No amounts were capitalized as part of the cost of an asset. The Company did not recognize a material tax benefit related to unit-based compensation for the periods presented. Additionally, the total intrinsic value of options exercised, share-based liabilities paid, and the total fair value of units vested during the year were immaterial.
10. Revolving credit facility
In 2020, the Company and certain of its subsidiaries entered into a revolving credit agreement with Pinnacle Bank (the “Revolving Credit Agreement”), as amended from time to time. The Revolving Credit Agreement is secured by a first-priority lien on substantially all assets of the Company and its subsidiaries. Borrowings under the Revolving Credit Agreement bear interest at a floating rate based on the Prime Rate, subject to a floor. The agreement contains customary affirmative and negative covenants, including restrictions on indebtedness, liens, investments, affiliate transactions, mergers and asset sales, and restricted payments, as well as financial reporting requirements. The agreement also includes financial covenants requiring compliance with a maximum total net leverage ratio and a minimum liquidity threshold, each as defined in the agreement.
In December 2024, the revolving credit commitment was reduced to $40.0 million pursuant to previously established milestone provisions under the Revolving Credit Agreement.
In May 2025, the Company entered into an amendment to the Revolving Credit Agreement that extended the maturity date from June 30, 2025, to June 30, 2026, and reduced total commitments from $40.0 million to
$30.0 million.
In October 2025, the Company entered into an additional amendment that increased the letter of credit sublimit from $10.0 million to $15.0 million. Total commitments remained $30.0 million.
F-30
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
As of December 31, 2025, the Company had no revolving borrowings outstanding, $10.2 million of letters of credit outstanding, and $19.8 million of available capacity under the Revolving Credit. As of December 31, 2024, the Company had no revolving borrowings outstanding, $9.4 million of letters of credit outstanding, and $30.6 million of available capacity. Outstanding letters of credit expire at various dates in 2026.
In March 2026, the Company entered into an amendment to the Revolving Credit Facility that extended the maturity date from June 30, 2026, to June 30, 2027, and increased the total commitments to $60.0 million. The amendment also revised the interest rate from a Prime Rate-based structure to a Term SOFR-based structure, plus an applicable margin. The amended agreement continues to be secured by substantially all assets of the Company and includes customary financial and non-financial covenants, including a maximum net leverage ratio and minimum liquidity requirement.
The Company was in compliance with all financial and non-financial covenants as of December 31, 2025.
11. Commitments and contingencies
Litigation
The Company is party to claims and lawsuits as well as threatened or potential actions or claims concerning matters arising from the conduct of its business activities. The outcome of claims or litigation and the timing of ultimate resolution are inherently difficult to predict, and significant judgment may be required in the determination of both the probability of loss and whether the amount of the loss is reasonably estimable. The following factors, among others, contribute to this lack of predictability: plaintiff claims often include significant legal uncertainties, damages alleged by plaintiffs are often unspecified or overstated, discovery may not have started or may not be complete, and material facts may be disputed or unsubstantiated. The Company’s estimates are subjective and are based on the status of legal and regulatory proceedings, the merit of the Company’s defenses and consultation with internal and external legal counsel.
The Company is not always able to provide an estimate of the range of reasonably possible outcomes for each claim. An accrual for a potential litigation loss is established when information related to the loss contingency indicates both that a loss is probable and that the amount of loss can be reasonably estimated. Any such accrual is adjusted from time to time thereafter as appropriate to reflect changes in circumstances.
The assessment of whether a loss is probable or reasonably possible, and whether the loss or a range of loss is estimable, often involves a series of complex judgments about future events. In all instances, management has assessed the matter based on current information and made a judgment concerning its potential outcome, giving due consideration to the nature of the claim, the amount and nature of damages sought and the probability of success and taking into account, among other things, negotiations with claimants, discovery, settlements and payments, judicial rulings, arbitration and mediation decisions, advice of internal and external legal counsel, and other information and events pertaining to a particular matter. No proceedings are expected to have a material adverse effect on the Company’s consolidated financial position, results of operations, or cash flows. However, management’s judgment may prove materially inaccurate, and such judgment is made subject to the known uncertainties of litigation.
F-31
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to consolidated financial statements
12. Major customer concentration
The following customers each comprised 10% or more of the Company’s total revenue:
| Year ended December 31, | 2025 | 2024 | ||||||
| Percentage of revenue (%) | ||||||||
| Customer A |
20 | 51 | ||||||
| Customer B |
16 | 21 | ||||||
| Customer C |
* | 15 | ||||||
| Customer D |
20 | * | ||||||
| Customer E |
17 | * | ||||||
| * | Revenue for these customers was less than 10% of the Company’s total revenue for the year. |
The following customers each comprised 10% or more of the Company’s total Accounts receivable, net:
| December 31, | 2025 | 2024 | ||||||
| Percentage of accounts receivable, net (%) | ||||||||
| Customer A |
* | 44 | ||||||
| Customer B |
31 | * | ||||||
| Customer D |
31 | 21 | ||||||
| * | Accounts receivable, net for these customers were less than 10% of the Company’s total receivables as of the year end. |
13. Related party transactions
Distributions to parent
The Company is a wholly owned subsidiary of the Parent. The Parent is a related party of the Company.
During the year ended December 31, 2025, the Company made distributions to the Parent of $6.0 million in September 2025. The distributions were approved by the Board of Directors on the respective dates of the distributions and were funded from cash on hand. The distributions were non-interest bearing and were recorded as a reduction to members’ equity.
In January and April 2026, the Company made additional cash distributions to the Parent of approximately $8.0 million and $23.5 million, respectively.
14. Subsequent events
The Company has reviewed subsequent events through May 8, 2026, the date these consolidated financial statements were available to be issued and has identified no material subsequent events requiring disclosure other than the matters described elsewhere in the consolidated financial statements.
F-32
Table of Contents
PART I. FINANCIAL INFORMATION
ITEM 1. FINANCIAL STATEMENTS
CoVolt Holdings Group, LLC and subsidiaries
Condensed consolidated balance sheets
(in thousands, except unit amounts, unaudited)
| June 30, 2026 |
December 31, 2025 |
|||||||
| Assets |
||||||||
| Current assets: |
||||||||
| Cash and cash equivalents |
$ | 119,218 | $ | 140,590 | ||||
| Restricted cash |
4,736 | 10,494 | ||||||
| Accounts receivable, net |
50,245 | 42,929 | ||||||
| Contract assets |
5,636 | 12,485 | ||||||
| Other current assets |
26,728 | 19,320 | ||||||
| Total current assets |
206,563 | 225,818 | ||||||
| Property and equipment, net |
3,602 | 3,396 | ||||||
| Finance lease right-of-use assets, net |
4,302 | 5,263 | ||||||
| Operating lease right-of-use assets |
3,192 | 2,049 | ||||||
| Goodwill |
62,852 | 62,852 | ||||||
| Other intangible assets, net |
2,811 | 3,583 | ||||||
| Other non-current assets |
425 | 147 | ||||||
| Total assets |
$ | 283,747 | $ | 303,108 | ||||
| Liabilities and members’ equity |
||||||||
| Current liabilities: |
||||||||
| Accounts payable |
$ | 73,626 | $ | 75,572 | ||||
| Contract liabilities |
77,417 | 93,039 | ||||||
| Accrued expenses and other |
19,076 | 24,897 | ||||||
| Finance lease liabilities, current portion |
1,546 | 1,706 | ||||||
| Operating lease liabilities, current portion |
247 | 50 | ||||||
| Total current liabilities |
171,912 | 195,264 | ||||||
| Finance lease liabilities, net of current portion |
715 | 1,430 | ||||||
| Operating lease liabilities, net of current portion |
3,281 | 2,083 | ||||||
| Other non-current liabilities |
2,174 | 2,241 | ||||||
| Total liabilities |
178,082 | 201,018 | ||||||
| Commitments and contingencies (Note 7) |
||||||||
| Members’ equity |
||||||||
| Members’ equity: 100 authorized, issued, and outstanding units |
107,709 | 104,152 | ||||||
| Accumulated other comprehensive loss |
(2,055 | ) | (2,073 | ) | ||||
| Total CoVolt Holdings Group, LLC |
105,654 | 102,079 | ||||||
| Non-controlling interests |
11 | 11 | ||||||
| Total members’ equity |
105,665 | 102,090 | ||||||
| Total liabilities and members’ equity |
$ | 283,747 | $ | 303,108 | ||||
See accompanying notes to these unaudited condensed consolidated financial statements.
F-33
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Condensed consolidated statements of income
(in thousands, unaudited)
| Six Months Ended June 30, |
||||||||
| 2026 | 2025 | |||||||
| Revenue |
$ | 308,278 | $ | 451,379 | ||||
| Cost of revenue |
254,158 | 389,895 | ||||||
| Gross profit |
54,120 | 61,484 | ||||||
| General and administrative |
18,537 | 14,370 | ||||||
| Depreciation and amortization |
914 | 4,429 | ||||||
| Gain on disposal of assets |
(193 | ) | — | |||||
| Operating income |
34,862 | 42,685 | ||||||
| Other income (expense) |
||||||||
| Interest income |
1,614 | 445 | ||||||
| Interest expense |
(279 | ) | (256 | ) | ||||
| Other income (expense), net |
(837 | ) | 363 | |||||
| Total other income |
498 | 552 | ||||||
| Net income |
35,360 | 43,237 | ||||||
| Net income attributable to non-controlling interest |
— | — | ||||||
| Net income attributable to CoVolt Holdings Group, LLC |
$ | 35,360 | $ | 43,237 | ||||
See accompanying notes to these unaudited condensed consolidated financial statements.
F-34
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Condensed consolidated statements of comprehensive income
(in thousands, unaudited)
| Six Months Ended June 30, |
||||||||
| 2026 | 2025 | |||||||
| Net income |
$ | 35,360 | $ | 43,237 | ||||
| Other comprehensive income (loss) |
||||||||
| Foreign currency translation adjustment |
18 | 23 | ||||||
| Comprehensive income |
35,378 | 43,260 | ||||||
| Comprehensive income attributable to non-controlling interests |
— | — | ||||||
| Comprehensive income attributable to CoVolt Holdings Group, LLC |
$ | 35,378 | $ | 43,260 | ||||
See accompanying notes to these unaudited condensed consolidated financial statements.
F-35
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Condensed consolidated statements of changes in members’ equity
(in thousands, unaudited)
| Members’ equity |
Accumulated other comprehensive (loss) |
Non-controlling interests |
Total Equity |
|||||||||||||
| Six Months Ended June 30, 2026 |
||||||||||||||||
| Balance, January 1, 2026 |
104,152 | (2,073 | ) | 11 | 102,090 | |||||||||||
| Unit-based compensation |
210 | — | — | 210 | ||||||||||||
| Distributions to Parent |
(32,013 | ) | — | — | (32,013 | ) | ||||||||||
| Foreign currency translation adjustment |
— | 18 | — | 18 | ||||||||||||
| Net income |
35,360 | — | — | 35,360 | ||||||||||||
| Balance, June 30, 2026 |
107,709 | (2,055 | ) | 11 | 105,665 | |||||||||||
| Six Months Ended June 30, 2025 |
||||||||||||||||
| Balance, January 1, 2025 |
51,062 | (2,140 | ) | 11 | 48,933 | |||||||||||
| Unit-based compensation |
300 | — | — | 300 | ||||||||||||
| Foreign currency translation adjustment |
— | 23 | — | 23 | ||||||||||||
| Net income |
43,237 | — | — | 43,237 | ||||||||||||
| Balance, June 30, 2025 |
94,599 | (2,117 | ) | 11 | 92,493 | |||||||||||
See accompanying notes to these unaudited condensed consolidated financial statements.
F-36
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Condensed consolidated statements of cash flows
(in thousands, unaudited)
| Six Months Ended June 30, |
||||||||
| 2026 | 2025 | |||||||
| Cash flows from operating activities |
||||||||
| Net income |
$ | 35,360 | $ | 43,237 | ||||
| Adjustments to reconcile net income to net cash provided by operating activities: |
||||||||
| Depreciation and amortization |
1,484 | 4,630 | ||||||
| Amortization of finance lease ROU assets |
700 | 1,111 | ||||||
| Amortization of deferred debt issuance costs |
226 | 73 | ||||||
| Gain on sale of property and equipment |
(193 | ) | — | |||||
| Unit-based compensation |
210 | 300 | ||||||
| Changes in operating assets and liabilities: |
||||||||
| Accounts receivable |
(5,892 | ) | (42,993 | ) | ||||
| Contract assets |
5,425 | 12,352 | ||||||
| Accounts payable |
(1,945 | ) | 5,721 | |||||
| Contract liabilities |
(15,621 | ) | (67,435 | ) | ||||
| Accrued expenses and other |
(5,795 | ) | 7,951 | |||||
| Other current assets |
(7,411 | ) | 27,602 | |||||
| Other non-current assets |
(279 | ) | 34 | |||||
| Net cash provided by (used in) operating activities |
6,269 | (7,417 | ) | |||||
| Cash flows from investing activities: |
||||||||
| Purchases of property and equipment |
(763 | ) | (193 | ) | ||||
| Proceeds from sale of property and equipment |
300 | — | ||||||
| Net cash used in investing activities |
(463 | ) | (193 | ) | ||||
| Cash flows from financing activities: |
||||||||
| Payments on other non-current liability |
(68 | ) | (31 | ) | ||||
| Distributions to Parent |
(32,013 | ) | — | |||||
| Payments of finance lease liabilities |
(873 | ) | (2,122 | ) | ||||
| Net cash used in financing activities |
(32,954 | ) | (2,153 | ) | ||||
| Effect of exchange rate on cash, cash equivalents, and restricted cash |
18 | 23 | ||||||
| Net decrease in cash, cash equivalents, and restricted cash |
(27,130 | ) | (9,740 | ) | ||||
| Cash, cash equivalents, and restricted cash beginning of period |
151,084 | 84,691 | ||||||
| Cash, cash equivalents, and restricted cash end of period |
$ | 123,954 | $ | 74,951 | ||||
| Supplemental disclosure of cash flow information |
||||||||
| Cash paid during the period for interest |
87 | 169 | ||||||
| Supplemental disclosure of non-cash activities |
||||||||
| ROU assets obtained for new operating lease obligations |
500 | — | ||||||
| ROU assets obtained for new finance lease obligations |
— | 2,842 | ||||||
See accompanying notes to these unaudited condensed consolidated financial statements.
F-37
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Condensed consolidated statements of cash flows – (continued)
(in thousands, unaudited)
The table below provides a reconciliation of cash, cash equivalents, and restricted cash reported in the Condensed consolidated Balance Sheets to the amount reported in the Condensed consolidated Statement of Cash Flows for the periods presented:
| June 30, | ||||||||
| 2026 | 2025 | |||||||
| Cash and cash equivalents |
$ | 119,218 | $ | 65,230 | ||||
| Restricted cash(1) |
4,736 | 9,721 | ||||||
| Total cash, cash equivalents, and restricted cash shown in consolidated statements of cash flows |
$ | 123,954 | $ | 74,951 | ||||
| (1) | Restricted cash represents amounts pledged as collateral to support outstanding letters of credit under the Company’s revolving credit facility and is not available for general corporate purposes while pledged. |
See accompanying notes to condensed consolidated financial statements.
F-38
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to condensed consolidated financial statements
(in thousands, except unit and per unit amounts, unaudited)
Note 1—Organization and business
CoVolt Holdings Group, LLC and its subsidiaries (hereafter collectively referred to as the “Company” or “CoVolt”) is a leading provider of engineering, procurement and construction services to the power infrastructure and data center markets throughout the United States. The work is primarily performed under fixed priced contracts. We are headquartered in Houston, Texas, with secondary offices in Chattanooga, Tennessee and Albany, New York.
Note 2—Summary of significant accounting policies
Basis of accounting and presentation
The accompanying condensed consolidated financial statements include the accounts of the Company and its controlled subsidiaries which reflect all adjustments necessary to state fairly the Company’s consolidated financial position, results of operations, and cash flows in accordance with principles generally accepted in the United States of America (“U.S. GAAP”). These condensed consolidated financial statements should be read in conjunction with the consolidated financial statements and related notes for the year ended December 31, 2025, which appear elsewhere in our previously filed registration statement on Form S-1. The results for the six months ended June 30, 2026 are not necessarily indicative of the results to be expected for the full year.
The Company classifies certain assets and liabilities as current utilizing the duration of the related contract or program as the Company’s operating cycle, which is generally longer than one year. This primarily impacts Contract Assets and Contract Liabilities. The Company classifies all other assets and liabilities based on whether the asset will be realized or the liability will be paid within one year.
Principles of consolidation
The condensed consolidated financial statements include the accounts of the Company and its subsidiaries. All material intercompany balances and transactions have been eliminated during consolidation. Any minority ownership is reported as a non-controlling interest. Non-controlling interests primarily relate to the Company’s partial ownership interest in a subsidiary. For the periods presented, the activity attributable to non-controlling interests was not material.
Use of estimates
The preparation of condensed consolidated financial statements in conformity with U.S. GAAP requires management to make estimates and assumptions that affect the amounts reported in the accompanying unaudited condensed consolidated financial statements and these notes.
Actual results could differ materially from those estimates and may result in material effects on the Company’s operating results and financial position. Estimates made in preparing the accompanying condensed consolidated financial statements primarily include, but are not limited to, those related to revenue recognition, goodwill and long-lived asset valuations, impairment assessments, and unit-based compensation. Management believes that these estimates and assumptions provide a reasonable basis for the fair presentation of the condensed consolidated financial statements.
F-39
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to condensed consolidated financial statements
(in thousands, except unit and per unit amounts, unaudited)
Cash and cash equivalents
The Company considers cash and cash equivalents to include cash on hand, cash held in demand deposit accounts, and all highly liquid financial instruments purchased with an original maturity of three months or less. The Company places its cash and cash equivalents with high credit quality financial institutions. At times, such amounts may be in excess of the Federal Deposit Insurance Corporation limits.
Restricted cash
Restricted cash represents amounts pledged as collateral to support outstanding letters of credit under the Company’s revolving credit facility and is not available for general corporate purposes while pledged. Restricted cash is classified as current on the condensed consolidated balance sheets as the related letters of credit are expected to expire within the next 12 months of the condensed consolidated balance sheets date.
Income taxes
The Company is a limited liability company. As a result, members report the federal corporate taxable income on their individual income tax returns. However, the Company is subject to income taxes in certain states in which business is conducted, and these amounts are not considered significant to the condensed consolidated financial statements. For the six months ended June 30, 2026 and 2025, these amounts were not material to the condensed consolidated financial statements.
Income taxes are reported in accordance with ASC 740, Income Taxes. This guidance requires the establishment of deferred tax accounts for all temporary differences between the book and tax basis of assets and liabilities. In addition, deferred tax accounts must be adjusted to reflect new rates if enacted into law. There are no significant temporary differences between financial statement and income tax reporting as of June 30, 2026 and December 31, 2025. Accordingly, no deferred state income taxes are included in the accompanying condensed consolidated financial statements.
The Company recognizes a benefit only if it is more likely than not that the tax position would be sustained in a tax examination, with a tax examination being presumed to occur. The amount recognized is the largest amountof tax benefit that is greater than 50% likely of being realized on examination. For tax positions not meeting the more-likely-than-not test, no tax benefit is recorded. As of June 30, 2026 and December 31, 2025, the Company did not have any unrecognized tax benefits recorded and does not expect any significant change in the next 12 months.
The Company recognizes interest and penalties related to income tax matters in interest and income tax expense, respectively. The Company had no material amounts accrued for interest or penalties as of June 30, 2026 and December 31, 2025.
Note 3—New accounting pronouncements
New accounting pronouncements not yet adopted
In November 2024, the Financial Accounting Standards Board (“FASB”) issued Accounting Standards Update (“ASU”) 2024-03, Income Statement—Reporting Comprehensive Income—Expense Disaggregation Disclosures (Subtopic 220-40): Disaggregation of Income Statement Expenses (“ASU 2024-03”). ASU 2024-03 requires
F-40
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to condensed consolidated financial statements
(in thousands, except unit and per unit amounts, unaudited)
entities to tabularly disclose in the footnotes to the financial statements, the amounts of purchased inventory, employee compensation, depreciation, and intangible asset amortization included in each relevant expense caption. ASU 2024-03 also requires disclosure of the amount, and a qualitative description of, other items remaining in relevant expense captions that are not separately disaggregated. ASU 2024-03 is effective for fiscal years beginning after December 15, 2026, and interim periods within fiscal years beginning after December 15, 2027. Early adoption and both prospective and retrospective application are permitted. The Company is currently assessing the effect of this update.
In September 2025, the FASB issued ASU 2025-06, Intangibles—Goodwill and Other—Internal-Use Software (Subtopic 350-40): Targeted Improvements to the Accounting for Internal-Use Software (“ASU 2025-06”). ASU 2025-06 modernizes the accounting for internal-use software by eliminating the previous stage-based capitalization model so that the guidance is neutral to different software development methods. ASU 2025-06 is effective for fiscal years beginning after December 15, 2027, including interim periods within those fiscal years, with early adoption permitted. The amendments in ASU 2025-06 should be applied prospectively, with retrospective application or a modified transition approach permitted. The Company is currently assessing the effect of this update.
Note 4—Revenue from contracts with customers
The Company’s revenue is primarily derived from long-term contracts with customers and accounting treatment of these contracts is in accordance with ASC 606, Revenue from Contracts with Customers. Substantially all of the Company’s revenue is recognized over time, as performance obligations are satisfied, due to the continuous transfer of control to the customer and the Company’s continuous right to payment throughout the contracts’ duration.
During the six months ended June 30, 2026 and 2025, the Company recognized revenue of $83.9 million and $119.6 million related to contract liabilities outstanding as of the end of each respective preceding fiscal year.
Remaining performance obligations reflect the portion of the transaction price associated with customer orders for which work has not yet been completed. As of June 30, 2026 the Company had $565.0 million of remaining performance obligations relating to the Company’s engineering, procurement, and construction (“EPC”) service contracts. The Company expects to recognize revenue on substantially all of these remaining obligations within the next 18 months.
Contract assets and liabilities consist of the following (dollar amounts in thousands):
| June 30, 2026 |
December 31, 2025 |
|||||||
| Unbilled and retainages receivables |
$ | 5,636 | $ | 12,485 | ||||
| Total Contract assets |
5,636 | 12,485 | ||||||
| Billings in excess of costs and estimated earnings |
77,417 | 93,039 | ||||||
| Total Contract liabilities |
$ | 77,417 | $ | 93,039 | ||||
Contract assets and liabilities fluctuate period to period based primarily on changes in the number and size of projects in progress at period end, variability in billing and payment terms, and change orders or contract modifications.
F-41
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to condensed consolidated financial statements
(in thousands, except unit and per unit amounts, unaudited)
Note 5—Segment information
The Company operates in one reportable segment which derives revenue through providing engineering, procurement, and construction (“EPC”) services throughout the United States. The Company concludes that it operates as a single operating segment encompassing all EPC services, photovoltaic solar, high-voltage substations, switchyards, collector systems, and transmission lines. The consolidated operating results are regularly reviewed by the Chief Operating Decision Maker (“CODM”) to allocate resources or assess performance. As such, the Company reflects its financial results as one reportable segment, which reflects the consolidated performance of its business activities. The accounting policies of the reportable segment are the same as those described in the summary of significant accounting policies.
The Company has identified the President and Chief Executive Officer as the CODM.
The key measure of segment profit or loss utilized by the CODM to assess performance of and allocate resources to the Company’s operating segment is consolidated net income, primarily by monitoring actual results compared to prior periods and expected results. The significant expense categories reviewed by the CODM are consistent with what appears on the face of the condensed consolidated statements of income. The Company’s CODM uses the condensed consolidated balance sheets and condensed consolidated statements of income to assess performance and decide how to allocate resources.
Note 6—Revolving credit facility
In 2020, the Company and certain of its subsidiaries entered into a revolving credit agreement with Pinnacle Bank (the “Revolving Credit Agreement”), as amended from time to time. The Revolving Credit Agreement is secured by a first-priority lien on substantially all assets of the Company and its subsidiaries. Borrowings under the Revolving Credit Agreement bear interest at a floating rate based on the Prime Rate, subject to a floor. The agreement contains customary affirmative and negative covenants, including restrictions on indebtedness, liens, investments, affiliate transactions, mergers and asset sales, and restricted payments, as well as financial reporting requirements. The agreement also includes financial covenants requiring compliance with a maximum total net leverage ratio and a minimum liquidity threshold, each as defined in the agreement.
In March 2026, the Company entered into an amendment to the Revolving Credit Facility that extended the maturity date from June 30, 2026, to June 30, 2027, and increased the total commitments to $60.0 million. The amendment also revised the interest rate from a Prime Rate-based structure to a Term SOFR-based structure, plus an applicable margin. The amended agreement continues to be secured by substantially all assets of the Company and includes customary financial and non-financial covenants, including a maximum net leverage ratio and minimum liquidity requirement.
As of June 30, 2026, the Company had no revolving borrowings outstanding under the Revolving Credit Agreement, $4.7 million of letters of credit outstanding, and $55.3 million of remaining availability thereunder. The outstanding letters of credit expire at various dates during 2026.
The Company was in compliance with all financial and non-financial covenants as of June 30, 2026.
F-42
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to condensed consolidated financial statements
(in thousands, except unit and per unit amounts, unaudited)
Note 7—Commitments and contingencies
Litigation
The Company is party to claims and lawsuits as well as threatened or potential actions or claims concerning matters arising from the conduct of its business activities. The outcome of claims or litigation and the timing of ultimate resolution are inherently difficult to predict, and significant judgment may be required in the determination of both the probability of loss and whether the amount of the loss is reasonably estimable. The following factors, among others, contribute to this lack of predictability: plaintiff claims often include significant legal uncertainties, damages alleged by plaintiffs are often unspecified or overstated, discovery may not have started or may not be complete, and material facts may be disputed or unsubstantiated. The Company’s estimates are subjective and are based on the status of legal and regulatory proceedings, the merit of the Company’s defenses and consultation with internal and external legal counsel.
The Company is not always able to provide an estimate of the range of reasonably possible outcomes for each claim. An accrual for a potential litigation loss is established when information related to the loss contingency indicates both that a loss is probable and that the amount of loss can be reasonably estimated. Any such accrual is adjusted from time to time thereafter as appropriate to reflect changes in circumstances.
The assessment of whether a loss is probable or reasonably possible, and whether the loss or a range of loss is estimable, often involves a series of complex judgments about future events. In all instances, management has assessed the matter based on current information and made a judgment concerning its potential outcome, giving due consideration to the nature of the claim, the amount and nature of damages sought and the probability of success and taking into account, among other things, negotiations with claimants, discovery, settlements and payments, judicial rulings, arbitration and mediation decisions, advice of internal and external legal counsel, and other information and events pertaining to a particular matter. No proceedings are expected to have a material adverse effect on the Company’s consolidated financial position, results of operations, or cash flows. However, management’s judgment may prove materially inaccurate, and such judgment is madesubject to the known uncertainties of litigation.
Note 8—Major customer concentration
The following customers each comprised 10% or more of the Company’s total revenues:
| For the Six Months Ended June 30, | ||||||||
| 2026 | 2025 | |||||||
| Percentage of revenue (%) | ||||||||
| Customer A |
45% | * | ||||||
| Customer B |
14% | 12% | ||||||
| Customer C |
* | 26% | ||||||
| Customer D |
* | 20% | ||||||
| Customer E |
* | 22% | ||||||
| Customer F |
11% | * | ||||||
| * | Revenue for these customers was less than 10% of the Company’s total revenue for the period. |
F-43
Table of Contents
CoVolt Holdings Group, LLC and subsidiaries
Notes to condensed consolidated financial statements
(in thousands, except unit and per unit amounts, unaudited)
The following customers each comprised 10% or more of the Company’s total accounts receivable:
| June 30, 2026 |
June 30, 2025 |
|||||||
| Percentage of accounts receivable, net (%) | ||||||||
| Customer A |
74% | * | ||||||
| Customer B |
* | * | ||||||
| Customer C |
* | 21% | ||||||
| Customer D |
* | 20% | ||||||
| Customer E |
* | 27% | ||||||
| Customer F |
* | * | ||||||
| * | Accounts receivable for these customers were less than 10% of the Company’s total receivables as of period end. |
Note 9—Related party transactions
Distributions to parent
The Company is a wholly owned subsidiary of the Parent. The Parent is a related party of the Company. During the six months ended June 30, 2026, the Company made distributions to the Parent of $32 million. The distributions were approved by the Board of Directors on the respective dates of the distributions and were funded from cash on hand. The distributions were non-interest bearing and were recorded as a reduction to members’ equity. In July 2026, the Company made additional cash distributions to the Parent of approximately $30 million.
Note 10—Subsequent events
The Company has evaluated subsequent events through August 4, 2026, which is the date the condensed consolidated financial statements were available to be issued. The following event occurred subsequent to the date the condensed financial statements were available to be issued: On August 7, 2026, the Company made distributions to the Parent of $31 million.
F-44
Table of Contents
Shares
CoVolt Power
Class A Common Stock
CoVolt Power, Inc.
| J.P. Morgan | Jefferies |
| RBC Capital Markets | UBS Investment Bank |
| KeyBanc Capital Markets | Wolfe | Nomura Alliance | |
| Baird | Needham & Company | Roth Capital Partners |
Table of Contents
PART II
INFORMATION NOT REQUIRED IN THE PROSPECTUS
Item 13. Other expenses of issuance and distribution.
The following table sets forth all fees and expenses, other than the underwriting discounts and commissions payable solely by CoVolt Power in connection with the offer and sale of the securities being registered. All amounts shown are estimated except for the SEC registration fee, the Financial Industry Regulatory Authority, Inc., or FINRA, filing fee and the exchange listing fee.
| Amount to be paid | ||||
| SEC registration fee |
$ | * | ||
| FINRA filing fee |
* | |||
| Exchange listing fee |
* | |||
| Accounting fees and expenses |
* | |||
| Legal fees and expenses |
* | |||
| Printing and engraving expenses |
* | |||
| Transfer agent and registrar fees |
* | |||
| Blue sky fees and expenses |
* | |||
| Miscellaneous expenses |
* | |||
| Total |
$ | * | ||
| * | To be completed by amendment. |
Item 14. Indemnification of directors and officers.
The Texas Business Organizations Code (the “TBOC”) permits a corporation to indemnify a director who was, is or is threatened to be a named defendant or respondent in a proceeding as a result of the performance of his or her duties if such person acted in good faith and, in the case of conduct in the person’s official capacity as a director, in a manner he or she reasonably believed to be in the best interests of the corporation and, in all other cases, that the person reasonably believed his or her conduct was not opposed to the best interests of the corporation and with respect to any criminal action or proceeding, that such person had no reasonable cause to believe his or her conduct was unlawful. Subject to certain exceptions, the TBOC further permits a corporation to eliminate in its charter all monetary liability of the corporation’s directors to the corporation or its shareholders for conduct in performance of such director’s duties, but not for a breach of the director’s duty of loyalty or receipt of an improper benefit. Our amended and restated certificate of formation will provide that a director of the corporation will not be liable to the corporation or its shareholders for monetary damages for any act or omission by the director in the performance of his or her duties, except that there will be no limitation of liability to the extent the director has been found liable under applicable law for: (i) breach of the director’s duty of loyalty owed to the corporation or its shareholders; (ii) an act or omission not in good faith that constitutes a breach of duty of the director to the corporation or that involves intentional misconduct or a
II-1
Table of Contents
knowing violation of the law; (iii) a transaction from which the director received an improper benefit, regardless of whether the benefit resulted from an action taken within the scope of the director’s duties; or (iv) an act or omission for which the liability of the director is expressly provided for by an applicable statute.
Sections 8.101 and 8.103 of the TBOC provide that a corporation may indemnify a person who was, is or is threatened to be a named defendant or respondent in a proceeding because the person is or was a director only if a determination is made that such indemnification is permissible under the TBOC: (i) by a majority vote of the directors who at the time of the vote are disinterested and independent, regardless of whether such directors constitute a quorum; (ii) by a majority vote of a board committee designated by a majority of disinterested and independent directors and consisting solely of disinterested and independent directors; (iii) by special legal counsel selected by the board of directors or a committee of the board of directors as set forth in (i) or (ii); (iv) by the shareholders in a vote that excludes the shares held by directors who are not disinterested and independent; or (v) by a unanimous vote of the shareholders.
Section 8.104 of the TBOC provides that the corporation may pay or reimburse, in advance of the final disposition of the proceeding, reasonable expenses incurred by a present director who was, is or is threatened to be made a named defendant or respondent in a proceeding after the corporation receives a written affirmation by the director of his or her good faith belief that he or she has met the standard of conduct necessary for indemnification under Section 8.101 and a written undertaking by or on behalf of the director to repay the amount paid or reimbursed if it is ultimately determined that he or she has not met that standard or if it is ultimately determined that indemnification of the director is not otherwise permitted under the TBOC. Section 8.105 also provides that reasonable expenses incurred by a former director, or a present or former employee, agent, or officer of the corporation, who was, is or is threatened to be made a named defendant or respondent in a proceeding may be paid or reimbursed by the corporation, in advance of the final disposition of the action, as the corporation considers appropriate.
Section 8.105 of the TBOC provides that, subject to restrictions in its certificate of formation and to the extent consistent with other law, a corporation may indemnify and advance expenses to a person who is not a director, including an officer, employee, or agent of the corporation as provided by: (i) the corporation’s governing documents; (ii) an action by the corporation’s governing authority; (iii) resolution by the shareholders; (iv) contract; or (v) common law. As consistent with Section 8.105, persons who are not directors may seek indemnification and advancement of expenses from a corporation to the same extent that directors may seek indemnification and advancement of expenses from a corporation.
Further, our amended and restated certificate of formation and amended and restated bylaws will provide that we must indemnify our directors and officers to the fullest extent authorized by law. We are also expressly required to advance certain expenses to our directors and officers, except for claims brought by us, and carry directors’ and officers’ insurance providing indemnification for our directors and officers for some liabilities. We believe that these indemnification provisions and the directors’ and officers’ insurance are useful to attract and retain qualified directors and executive officers.
We have also entered into, or will enter into prior to the completion of this offering, indemnification agreements with each of our directors and executive officers. The indemnification agreements provide, or will provide, among other things, for indemnification to the fullest extent permitted by the TBOC and our amended and restated certificate of formation and amended and restated bylaws against (i) any and all direct and indirect liabilities and reasonable expenses, including judgments, fines, penalties, interest and amounts paid in settlement of any claim with our approval and reasonable counsel fees and disbursements and (ii) any liabilities incurred as a result of serving as a director, officer, employee, or agent (including as a trustee, fiduciary, partner, or manager or in a similar capacity) of another enterprise or an employee benefit plan at our request. The indemnification agreements also provide for, or will provide for, the advancement or payment of expenses
II-2
Table of Contents
to the indemnitee and for reimbursement to us if it is found that such indemnitee is not entitled to such indemnification under applicable law and our amended and restated certificate of formation and amended and restated bylaws or the terms of the indemnification agreements.
We expect to maintain standard policies of insurance that provide coverage (i) to our directors and officers against loss rising from claims made by reason of breach of duty or other wrongful act and (ii) to us with respect to indemnification payments that we may make to such directors and officers. The underwriting agreement provides for indemnification by the underwriters of us and our officers and directors, and by us of the underwriters, for certain liabilities arising under the Securities Act or otherwise in connection with this offering.
Insofar as indemnification for liabilities arising under the Securities Act may be permitted to directors, officers, or persons controlling us under any of the foregoing provisions, in the opinion of the SEC, such indemnification is against public policy as expressed in the Securities Act and is therefore unenforceable.
Item 15. Recent sales of unregistered securities.
Set forth below is information regarding all unregistered securities sold by the Registrant since January 1, 2023. Also included is the consideration received by the Registrant for such securities and information relating to the section of the Securities Act of 1933, as amended (the “Securities Act”), or rule of the Securities and Exchange Commission, under which exemption from registration was claimed.
Equity Grants
From January 1, 2023 through the date of this registration statement, the Ultimate Parent granted equity incentive awards in the form of membership interest units to certain of its team members, officers and directors in connection with services provided to the company. No cash consideration was received by the Ultimate Parent for such grants.
The issuances of the securities described above were deemed to be exempt from registration under the Securities Act in reliance upon Section 4(a)(2) of the Securities Act and/or Rule 506 or Rule 701 promulgated thereunder. The securities were issued directly by us and did not involve a public offering or general solicitation. The recipients of such securities represented their intentions to acquire the securities for investment purposes only and not with a view to, or for sale in connection with, any distribution thereof. None of the transactions set forth in this Item 15 involved any underwriters, underwriting discounts or commissions or any public offering. All recipients had adequate access, through their relationships with us, to information about us. The sales of these securities were made without any general solicitation or advertising.
Item 16. Exhibits and financial statements.
1. (a) Exhibits
The exhibits filed herewith are set forth on the Index to Exhibits filed as a part of this Registration Statement beginning on page II-5 hereof.
2. (b) Financial Statement Schedules
All schedules have been omitted because the information required to be set forth in the schedules is either not applicable or is shown in the financial statements or notes thereto.
II-3
Table of Contents
Item 17. Undertakings.
3. (a) The undersigned registrant hereby undertakes to provide to the underwriters at the closing specified in the underwriting agreement certificates in such denominations and registered in such names as required by the underwriters to permit prompt delivery to each purchaser.
4. (b) Insofar as indemnification for liabilities arising under the Securities Act may be permitted to directors, officers and controlling persons of the registrant pursuant to the foregoing provisions, or otherwise, the registrant has been advised that in the opinion of the SEC such indemnification is against public policy as expressed in the Securities Act and is, therefore, unenforceable. In the event that a claim for indemnification against such liabilities (other than the payment by the registrant of expenses incurred or paid by a director, officer or controlling person of the registrant in the successful defense of any action, suit or proceeding) is asserted by such director, officer or controlling person in connection with the securities being registered, the registrant will, unless in the opinion of its counsel the matter has been settled by controlling precedent, submit to a court of appropriate jurisdiction, the question whether such indemnification by it is against public policy as expressed in the Securities Act and will be governed by the final adjudication of such issue.
5. (c) The undersigned hereby further undertakes that:
(i) (1) For purposes of determining any liability under the Securities Act the information omitted from the form of prospectus filed as part of this registration statement in reliance upon Rule 430A and contained in a form of prospectus filed by the registrant pursuant to Rule 424(b)(1) or (4) or 497(h) under the Securities Act shall be deemed to be part of this registration statement as of the time it was declared effective.
(ii) (2) For the purpose of determining any liability under the Securities Act each post-effective amendment that contains a form of prospectus shall be deemed to be a new registration statement relating to the securities offered therein, and the offering of such securities at that time shall be deemed to be the initial bona fide offering thereof.
(iii) (3) For the purpose of determining liability of the registrant under the Securities Act of 1933 to any purchaser in the initial distribution of the securities, the undersigned registrant undertakes that in a primary offering of securities of the undersigned registrant pursuant to this registration statement, regardless of the underwriting method used to sell the securities to the purchaser, if the securities are offered or sold to such purchaser by means of any of the following communications, the undersigned registrant will be a seller to the purchaser and will be considered to offer or sell such securities to such purchaser:
(A) (i) Any preliminary prospectus or prospectus of the undersigned registrant relating to the offering required to be filed pursuant to Rule 424 under the Securities Act;
(B) (ii) Any free writing prospectus relating to the offering prepared by or on behalf of the undersigned registrant or used or referred to by the undersigned registrant;
(C) (iii) The portion of any other free writing prospectus relating to the offering containing material information about the undersigned registrant or its securities provided by or on behalf of the undersigned registrant; and
(D) (iv) Any other communication that is an offer in the offering made by the undersigned registrant to the purchaser.
II-4
Table of Contents
INDEX TO EXHIBITS
| † | Indicates a management contract or compensatory plan or arrangement. |
| * | To be filed by amendment. |
II-5
Table of Contents
SIGNATURES
Pursuant to the requirements of the Securities Act of 1933, as amended, CoVolt Power has duly caused this registration statement to be signed on its behalf by the undersigned, thereunto duly authorized, in Houston, Texas on August 21, 2026.
| CoVolt Power | ||
| By: |
/s/ Robert L. Tabb | |
| Robert L. Tabb Chief Executive Officer | ||
II-6
Table of Contents
KNOW ALL PERSONS BY THESE PRESENTS, that each person whose signature appears below constitutes and appoints Robert L. Tabb and Ronnie V. Shields, and each one of them, as his or her true and lawful attorneys-in-fact and agents, with full power of substitution and resubstitution, for him or her and in their name, place and stead, in any and all capacities, to sign any and all amendments (including post-effective amendments) to this registration statement, and to sign any registration statement for the same offering covered by this registration statement that is to be effective on filing pursuant to Rule 462(b) under the Securities Act of 1933, as amended, and all post-effective amendments thereto, and to file the same, with all exhibits thereto and other documents in connection therewith, with the Securities and Exchange Commission, granting unto said attorneys-in-fact and agents, and each of them, full power and authority to do and perform each and every act and thing requisite and necessary to be done in connection therewith, as fully to all intents and purposes as he or she might or could do in person, hereby ratifying and confirming all that said attorneys-in-fact and agents or any of them, or his or her substitute or substitutes, may lawfully do or cause to be done by virtue hereof.
Pursuant to the requirements of the Securities Act of 1933, as amended, this registration statement on Form S-1 has been signed by the following persons in the capacities set forth opposite their names and on the date indicated above.
| Signature |
Title |
Date | ||
| /s/ Robert L. Tabb Robert L. Tabb |
Chief Executive Officer and Director (Principal Executive Officer) | August 21, 2026 | ||
| /s/ Ronnie V. Shields Ronnie V. Shields |
Chief Financial and Accounting Officer (Principal Financial Officer and Principal Accounting Officer) | August 21, 2026 | ||
| /s/ Avinash Kripalani Avinash Kripalani |
Director | August 21, 2026 | ||
| /s/ Sean K. Coleman Sean K. Coleman |
Director | August 21, 2026 | ||
| /s/ Matthew Kimble Matthew Kimble |
Director | August 21, 2026 | ||
| /s/ Rebekah B. Le Rebekah B. Le |
Director | August 21, 2026 | ||
| /s/ Louis Littman Louis Littman |
Director | August 21, 2026 | ||
| /s/ Stephen W. Atkins Stephen W. Atkins |
Director | August 21, 2026 | ||
II-7